
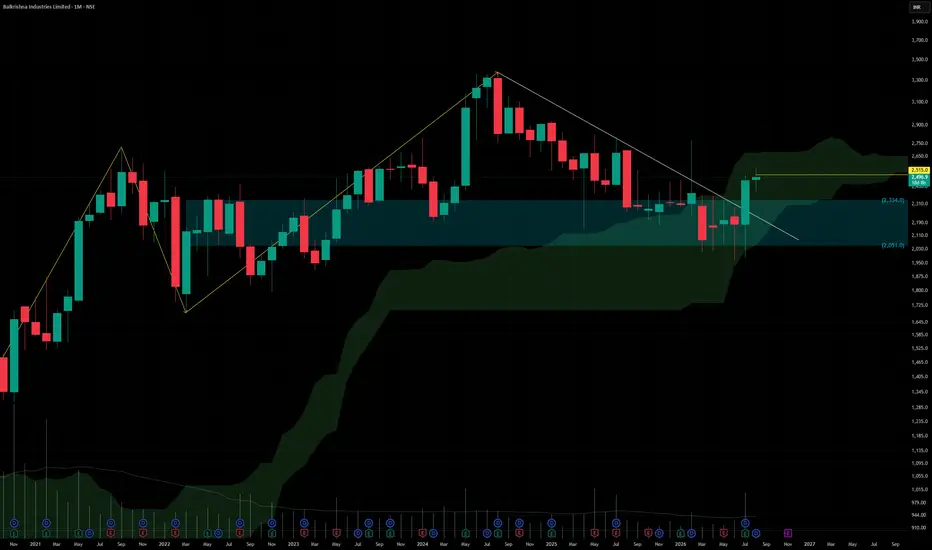
Balkrishna Industries Ltd. (CMP ₹2,496.00, NSE: BALKRISIND)
The SmartWay Research Desk | 13 August 2026
A Mumbai‑based tire manufacturer, incorporated in 1961. Balkrishna Industries (BKT) is India’s leading producer of off‑highway tires (OHT), catering to agriculture, construction, mining, and industrial equipment markets, with strong exports to over 160 countries.
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹10,842 Cr vs ₹9,612 Cr in FY25 (+12.8% YoY). → Good
Net Profit: FY26 PAT ₹1,812 Cr vs ₹1,612 Cr in FY25 (+12.4% YoY). → Good
Operating Margin: FY26 EBITDA ₹2,812 Cr, margin 25.9% vs 25.2% last year (+70 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹12.00/share declared for FY26. → Good
Asset Building: Investments in greenfield plants, carbon black expansion, and R&D for radial OHT tires. → Good
Sales: Strong demand from agriculture and mining equipment exports. → Good
Expense: Raw material cost pressures (natural rubber, crude derivatives) remain. → Neutral/Good
EPS: FY26 EPS ₹94.25 vs ₹83.80 last year (+12.5%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: ~58.3% (no pledges)
FII Holding: ~20.1%
DII Holding: ~15.6%
Retail & Others: ~6.0%
Strategic Moves & Innovations
Expansion in carbon black production for cost efficiency.
Focus on radial OHT tires for global markets.
Partnerships with OEMs in agriculture and mining sectors.
Diversification into sustainable tire technology and recycling initiatives.
Cash Flow & Balance Sheet Strength
Market cap ~₹48,200 Cr.
Debt‑to‑equity ratio ~0.32 (moderate leverage).
Book value per share ₹412.00; P/B ~6.1.
EPS (TTM) ₹94.25; P/E ~26.5.
Risk Factors
Moderate P/E ratio ~26.5, valuations fair.
Dependence on global OHT demand cycles.
Exposure to commodity price volatility (rubber, crude).
Competition from MRF, Apollo Tyres, and JK Tyre.
Investor Takeaway
Balkrishna Industries has delivered steady FY26 performance, supported by export growth, carbon black expansion, and radial tire innovation. With strong promoter backing, dividend payouts, and leadership in off‑highway tires, BKT remains a large‑cap specialty tire play. At CMP ₹2,496.00, valuations are reasonable (P/E ~26.5, P/B ~6.1), reflecting growth expectations with manageable risks.
The SmartWay Research Desk | 13 August 2026
A Mumbai‑based tire manufacturer, incorporated in 1961. Balkrishna Industries (BKT) is India’s leading producer of off‑highway tires (OHT), catering to agriculture, construction, mining, and industrial equipment markets, with strong exports to over 160 countries.
FY22–FY26 Snapshot
Revenue Growth: FY26 revenue ₹10,842 Cr vs ₹9,612 Cr in FY25 (+12.8% YoY). → Good
Net Profit: FY26 PAT ₹1,812 Cr vs ₹1,612 Cr in FY25 (+12.4% YoY). → Good
Operating Margin: FY26 EBITDA ₹2,812 Cr, margin 25.9% vs 25.2% last year (+70 bps). → Good
Equity Capital: Stable, face value ₹2. → Good
Dividend Policy: Dividend ₹12.00/share declared for FY26. → Good
Asset Building: Investments in greenfield plants, carbon black expansion, and R&D for radial OHT tires. → Good
Sales: Strong demand from agriculture and mining equipment exports. → Good
Expense: Raw material cost pressures (natural rubber, crude derivatives) remain. → Neutral/Good
EPS: FY26 EPS ₹94.25 vs ₹83.80 last year (+12.5%). → Good
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: ~58.3% (no pledges)
FII Holding: ~20.1%
DII Holding: ~15.6%
Retail & Others: ~6.0%
Strategic Moves & Innovations
Expansion in carbon black production for cost efficiency.
Focus on radial OHT tires for global markets.
Partnerships with OEMs in agriculture and mining sectors.
Diversification into sustainable tire technology and recycling initiatives.
Cash Flow & Balance Sheet Strength
Market cap ~₹48,200 Cr.
Debt‑to‑equity ratio ~0.32 (moderate leverage).
Book value per share ₹412.00; P/B ~6.1.
EPS (TTM) ₹94.25; P/E ~26.5.
Risk Factors
Moderate P/E ratio ~26.5, valuations fair.
Dependence on global OHT demand cycles.
Exposure to commodity price volatility (rubber, crude).
Competition from MRF, Apollo Tyres, and JK Tyre.
Investor Takeaway
Balkrishna Industries has delivered steady FY26 performance, supported by export growth, carbon black expansion, and radial tire innovation. With strong promoter backing, dividend payouts, and leadership in off‑highway tires, BKT remains a large‑cap specialty tire play. At CMP ₹2,496.00, valuations are reasonable (P/E ~26.5, P/B ~6.1), reflecting growth expectations with manageable risks.

Sucrit.D.Patil
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Sucrit.D.Patil
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.