
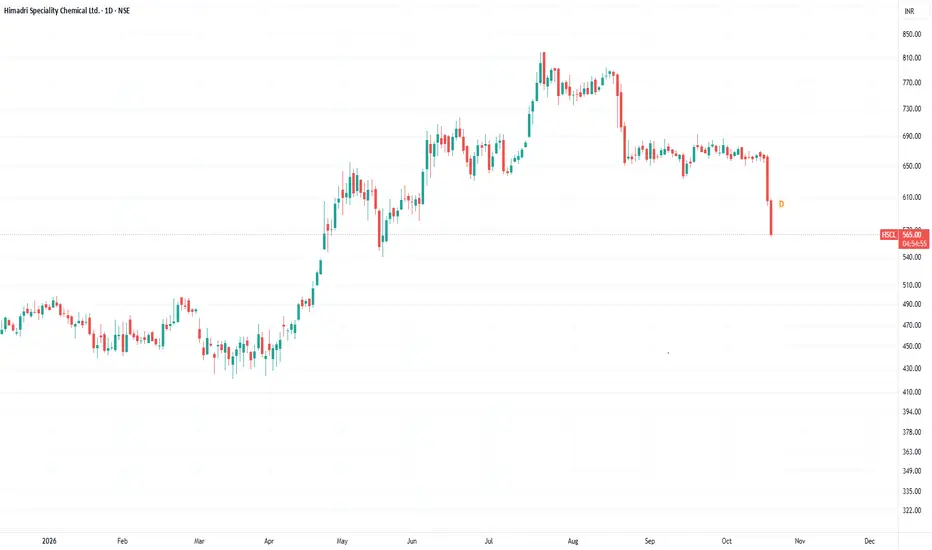
### 📈 Key Highlights
- **Revenue:** ₹1,691 crore | **+57.9% YoY | +18.1% QoQ**
- **Net Profit:** ₹231 crore | **+31.3% YoY | +1.3% QoQ**
- **EPS:** ₹4.60, up 28.5% YoY.
- **EBITDA:** Approximately ₹303 crore, down 3.2% QoQ.
- **EBITDA Margin:** Fell to 17.9% from 22.2% a year ago.
- **Net Profit Margin:** Declined to 13.68% from 16.45% YoY.
### ✅ Positives
- Strong revenue growth and healthy annual profit expansion.
- Increasing scale of operations.
- Long-term opportunities in speciality chemicals, advanced materials and battery materials.
### ⚠️ Key Concerns
- Operating expenses grew faster than revenue.
- Sequential EBITDA declined despite strong sales growth.
- Material costs and margin compression remain important risks.
- Expansion initiatives require successful execution to deliver returns.
### 🔍 What Should Investors Watch?
The key question is whether HSCL can **restore margins while sustaining revenue growth**. Strong sales are encouraging, but slowing sequential profit growth highlights the importance of earnings quality.
**Verdict:** Strong business growth, but mixed profitability. Margin recovery will be crucial for the next phase of performance.
- **Revenue:** ₹1,691 crore | **+57.9% YoY | +18.1% QoQ**
- **Net Profit:** ₹231 crore | **+31.3% YoY | +1.3% QoQ**
- **EPS:** ₹4.60, up 28.5% YoY.
- **EBITDA:** Approximately ₹303 crore, down 3.2% QoQ.
- **EBITDA Margin:** Fell to 17.9% from 22.2% a year ago.
- **Net Profit Margin:** Declined to 13.68% from 16.45% YoY.
### ✅ Positives
- Strong revenue growth and healthy annual profit expansion.
- Increasing scale of operations.
- Long-term opportunities in speciality chemicals, advanced materials and battery materials.
### ⚠️ Key Concerns
- Operating expenses grew faster than revenue.
- Sequential EBITDA declined despite strong sales growth.
- Material costs and margin compression remain important risks.
- Expansion initiatives require successful execution to deliver returns.
### 🔍 What Should Investors Watch?
The key question is whether HSCL can **restore margins while sustaining revenue growth**. Strong sales are encouraging, but slowing sequential profit growth highlights the importance of earnings quality.
**Verdict:** Strong business growth, but mixed profitability. Margin recovery will be crucial for the next phase of performance.

Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.