
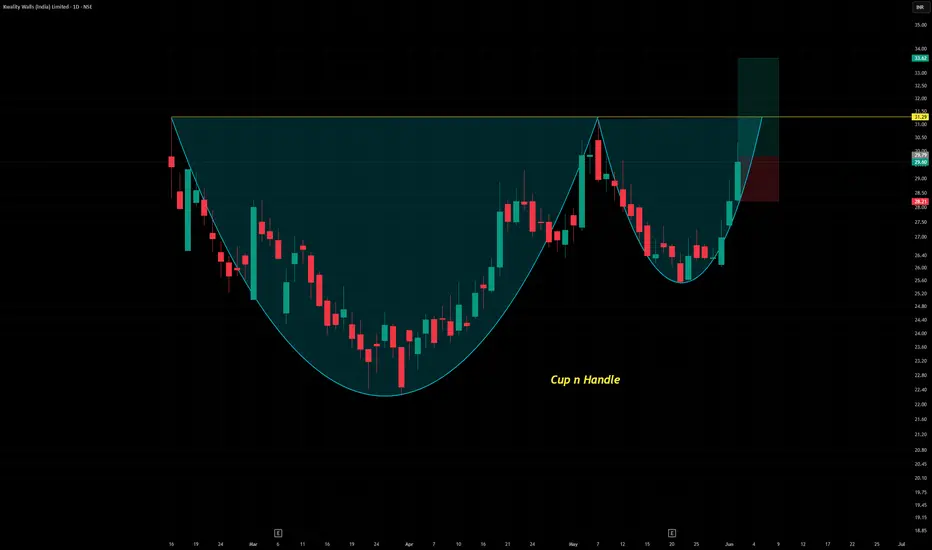
Kwality Walls (India) Ltd. (CMP ₹29.60, NSE: KWIL)
Prepared by Sucrit Patil | The SmartWay Research Desk | 3 June 2026
A frozen desserts and FMCG company, originally part of Hindustan Unilever Ltd., now majority owned by The Magnum Ice Cream Company N.V. (Netherlands) after its 2025 acquisition. Kwality Walls operates across India, South Asia, and Southeast Asia, with a strong brand presence in frozen desserts and ice creams.
Promoter Holding (Mar 2026): Magnum Ice Cream Company — 61.90% stake (no pledges)
FY22–FY26 Snapshot
Revenue Growth: FY25 revenue ₹6,954 Cr vs ₹6,215 Cr in FY24 (+11.9% YoY) → Good
Net Profit: FY25 PAT ₹182 Cr vs ₹156 Cr in FY24 (+16.7% YoY) → Good
Operating Margin: FY25 EBITDA ₹312 Cr, margin 14.1% vs 13.2% last year (+90 bps) → Good
Equity Capital: Stable, face value ₹1 → Good
Dividend Policy: No dividend declared; reinvestment focus → Neutral/Weak
Asset Building: Expansion into South Asia and ASEAN frozen dessert markets → Good
Sales: Strong demand from urban retail and quick-commerce platforms → Good
Expense: Raw material cost pressures (milk, sugar) remain → Neutral
EPS: FY25 EPS -₹3.14 (loss-making year) → Weak
Institutional Interest & Ownership Trends (Mar 2026)
Promoter Holding: 61.90% (no pledges)
FII Holding: 0.45%
DII Holding: 0.05%
Retail & Others: 37.60%
Strategic Moves & Innovations
Expansion into premium frozen desserts and plant-based ice creams.
Strengthening distribution through e-commerce and quick-commerce platforms.
Focus on ASEAN regional growth (Thailand, Singapore, Malaysia).
Partnerships with local dairy suppliers for cost optimization.
Cash Flow & Balance Sheet Strength
Market Cap: ~₹6,954 Cr
Debt: Debt-free balance sheet
Book Value Per Share: ₹0.23
P/B Ratio: ~128.7x
EPS (TTM): -₹3.14
P/E: Not meaningful due to losses
Risk Factors
Loss-making despite revenue growth.
Extremely high P/B valuation.
Dependence on discretionary consumer spending.
Competition from established players in ice cream and frozen desserts.
Raw material cost volatility impacting margins.
Investor Takeaway
Kwality Walls is a well-known consumer brand with strong market presence and expansion plans across Asia. Revenue growth remains healthy, supported by premium products and modern distribution channels. However, profitability remains a key concern, with the company still reporting negative EPS and trading at very rich asset-based valuations.
The investment case currently hinges on a successful profitability turnaround rather than earnings strength. Investors should closely monitor margin improvement, operating leverage, and the company's ability to convert revenue growth into sustainable profits before assigning premium valuations.

Sucrit.D.Patil
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Sucrit.D.Patil
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.