
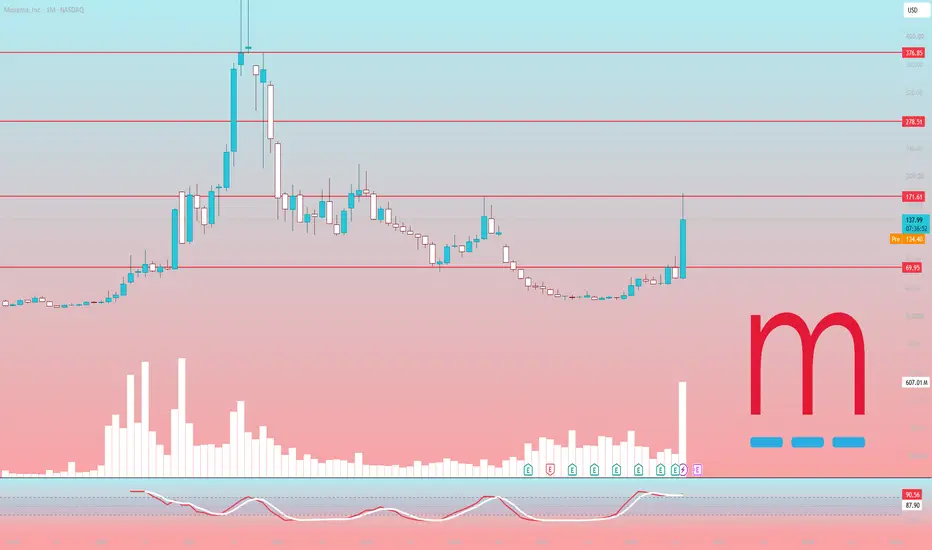
Moderna’s story is shifting from a COVID vaccine company toward a broader mRNA platform, and the biggest potential catalyst is its personalized cancer immunotherapy
The concept is built around identifying mutations unique to a patient’s tumor, creating a personalized neo antigen, and using mRNA to instruct the patient’s own cells to produce that target. The immune system can then recognize and attack cancer cells carrying that specific marker
🧬The Technology Is Powerful, But It Isn’t New
The market is treating Moderna’s cancer program as something almost entirely revolutionary, but that deserves some skepticism. Neo antigen immunotherapy has been studied for decades, with hundreds of trials exploring different cancer types, delivery methods, dosing strategies and combinations. Moderna’s potential advantage is its mRNA delivery system, which could make personalized treatments faster and more practical to manufacture
💰 The Real Opportunity Is Scale
This is where the Moderna bull case gets interesting. Personalized cancer treatment sounds enormously expensive, but the underlying process may ultimately be far cheaper than the headline prices suggest. DNA sequencing and much of the computational work are becoming inexpensive, while mRNA could allow the therapeutic component to be produced without manufacturing large quantities of the protein outside the body
If Moderna can turn that process into a repeatable, scalable platform, the addressable market could extend well beyond one cancer type
⚠️ But the Market May Be Pricing in Too Much Too Soon
Here is the problem for MRNA shareholders, a promising technology is not the same thing as a commercially dominant drug. Moderna still has to prove that its approach works consistently across cancers, demonstrate safety, optimize combinations and dosing, and ultimately establish that personalized manufacturing can work at scale
also if similar neo antigen treatments can eventually be produced outside Moderna’s ecosystem, the company may not have the monopoly investors currently imagine
The Moderna bull thesis isn't simply “cancer vaccine = stock goes higher.” The real thesis is that Moderna could transform its mRNA technology from a COVID era product into a broader therapeutic platform, with personalized oncology potentially becoming its most valuable application. But after the stock's dramatic repricing on positive cancer data, investors need to separate the scientific breakthrough from the economic moat
If Moderna can prove that personalized mRNA immunotherapy is safe, scalable and commercially defensible, the upside could be enormous. If competitors can reproduce the process cheaply, however, today's enthusiasm could prove far ahead of the actual economics.
The concept is built around identifying mutations unique to a patient’s tumor, creating a personalized neo antigen, and using mRNA to instruct the patient’s own cells to produce that target. The immune system can then recognize and attack cancer cells carrying that specific marker
🧬The Technology Is Powerful, But It Isn’t New
The market is treating Moderna’s cancer program as something almost entirely revolutionary, but that deserves some skepticism. Neo antigen immunotherapy has been studied for decades, with hundreds of trials exploring different cancer types, delivery methods, dosing strategies and combinations. Moderna’s potential advantage is its mRNA delivery system, which could make personalized treatments faster and more practical to manufacture
💰 The Real Opportunity Is Scale
This is where the Moderna bull case gets interesting. Personalized cancer treatment sounds enormously expensive, but the underlying process may ultimately be far cheaper than the headline prices suggest. DNA sequencing and much of the computational work are becoming inexpensive, while mRNA could allow the therapeutic component to be produced without manufacturing large quantities of the protein outside the body
If Moderna can turn that process into a repeatable, scalable platform, the addressable market could extend well beyond one cancer type
⚠️ But the Market May Be Pricing in Too Much Too Soon
Here is the problem for MRNA shareholders, a promising technology is not the same thing as a commercially dominant drug. Moderna still has to prove that its approach works consistently across cancers, demonstrate safety, optimize combinations and dosing, and ultimately establish that personalized manufacturing can work at scale
also if similar neo antigen treatments can eventually be produced outside Moderna’s ecosystem, the company may not have the monopoly investors currently imagine
The Moderna bull thesis isn't simply “cancer vaccine = stock goes higher.” The real thesis is that Moderna could transform its mRNA technology from a COVID era product into a broader therapeutic platform, with personalized oncology potentially becoming its most valuable application. But after the stock's dramatic repricing on positive cancer data, investors need to separate the scientific breakthrough from the economic moat
If Moderna can prove that personalized mRNA immunotherapy is safe, scalable and commercially defensible, the upside could be enormous. If competitors can reproduce the process cheaply, however, today's enthusiasm could prove far ahead of the actual economics.

Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.