
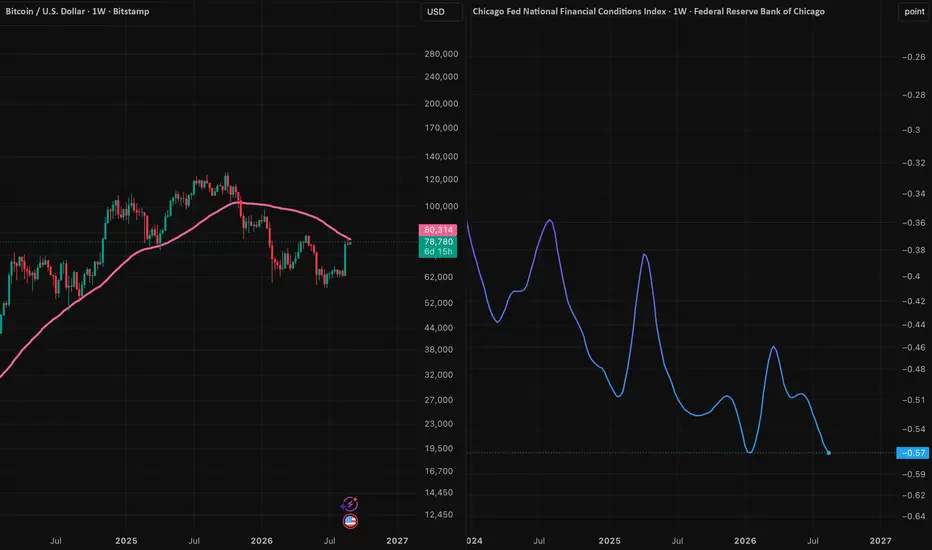
On the chart I have the NFCI on one side and Bitcoin with the 50 week SMA on the other.
The gap between these two is what this idea is about.
Policy right now is restrictive. That is not a guess, it is what the Fed keeps telling us. At Jackson Hole on the 28th of August, Warsh said inflation is still above the 2% target and policy can stay restrictive if price pressures persist. Yields moved up and risk assets sold off into the weekend.
But financial conditions do not look restrictive at all. The NFCI is still below zero at -0.57, which means conditions are looser than the historical average. At the same time the S&P has printed an intraday record of 7,814.88 and has closed at an all time high 25 times this year.
So the market is pricing easy money while the institution that sets the price of money is saying the opposite. One of those two has to give.
What I think is being missed is that Bitcoin has already taken its punishment. Price is roughly 38% below the October 2025 high of 126,209 and it printed 57,950 on the 1st of July, a 21 month low. Equities have had no equivalent event. Crypto priced the tightening, stocks did not.
Since that low we have rallied about 40%, tagging around 81,455 on the 28th of August before reversing back under 78,000. That number should look familiar to anyone who traded 2022. Back then BTC rallied around 43% off a June low into an August high, made a lower high, and bottomed in November.
On the bottom indicators, the picture is split and I would be careful with anyone telling you the low is already in.
Supply in profit has broken the trend line that marked lows in every previous cycle. Exchange reserves are at multi year lows. Short term holder SOPR is under 1, so recent buyers are underwater. Those have fired.
But MVRV Z-Score never reached the deep value zone below zero that marked 2018 and 2022, and price has not traded below realized price, which sits around 53,600.
The equity side deserves the same look. Breadth has actually improved this year, around 52% of S&P members are outperforming the index which is the best reading since 2016, and roughly two thirds are higher on the year. I am not going to pretend otherwise.
But breadth and concentration are different things and only one of them improved. The top ten names are still about 40.6% of the index, above the dot com peak. Earnings growth is carried by a handful of AI and semiconductor names. And the average S&P member has had a maximum drawdown of about 21% this year while the index itself never had an official correction. The highs are covering real damage underneath.
Bitcoin is below the 50 week SMA at $80,310 and for this idea to hold it needs to stay there. A sustained weekly close above it invalidates what I am saying here. So I would treat a reclaim as my Q4 idea being dead rather than the bull being back.
In conclusion, if the NFCI turns up towards zero and equities correct into Q4, I would expect Bitcoin to make a lower low with it and I think that would be the cycle bottom. Q4 also lines up with where the low has formed in previous cycles, but also lines with market corrections in mid term years for stocks.
This view is not contrarian at all, Galaxy has a Q4 bottom in the 40k to 46k region and Cowen, CryptoQuant and Brandt are all clustered around September to October.
The question for me is whether the correction will come, as these market conditions can last a long time. In addition if it comes later will that be enough to put a new low in. Despite speculation if BTC dips below the65k mark I will be buying.
The gap between these two is what this idea is about.
Policy right now is restrictive. That is not a guess, it is what the Fed keeps telling us. At Jackson Hole on the 28th of August, Warsh said inflation is still above the 2% target and policy can stay restrictive if price pressures persist. Yields moved up and risk assets sold off into the weekend.
But financial conditions do not look restrictive at all. The NFCI is still below zero at -0.57, which means conditions are looser than the historical average. At the same time the S&P has printed an intraday record of 7,814.88 and has closed at an all time high 25 times this year.
So the market is pricing easy money while the institution that sets the price of money is saying the opposite. One of those two has to give.
What I think is being missed is that Bitcoin has already taken its punishment. Price is roughly 38% below the October 2025 high of 126,209 and it printed 57,950 on the 1st of July, a 21 month low. Equities have had no equivalent event. Crypto priced the tightening, stocks did not.
Since that low we have rallied about 40%, tagging around 81,455 on the 28th of August before reversing back under 78,000. That number should look familiar to anyone who traded 2022. Back then BTC rallied around 43% off a June low into an August high, made a lower high, and bottomed in November.
On the bottom indicators, the picture is split and I would be careful with anyone telling you the low is already in.
Supply in profit has broken the trend line that marked lows in every previous cycle. Exchange reserves are at multi year lows. Short term holder SOPR is under 1, so recent buyers are underwater. Those have fired.
But MVRV Z-Score never reached the deep value zone below zero that marked 2018 and 2022, and price has not traded below realized price, which sits around 53,600.
The equity side deserves the same look. Breadth has actually improved this year, around 52% of S&P members are outperforming the index which is the best reading since 2016, and roughly two thirds are higher on the year. I am not going to pretend otherwise.
But breadth and concentration are different things and only one of them improved. The top ten names are still about 40.6% of the index, above the dot com peak. Earnings growth is carried by a handful of AI and semiconductor names. And the average S&P member has had a maximum drawdown of about 21% this year while the index itself never had an official correction. The highs are covering real damage underneath.
Bitcoin is below the 50 week SMA at $80,310 and for this idea to hold it needs to stay there. A sustained weekly close above it invalidates what I am saying here. So I would treat a reclaim as my Q4 idea being dead rather than the bull being back.
In conclusion, if the NFCI turns up towards zero and equities correct into Q4, I would expect Bitcoin to make a lower low with it and I think that would be the cycle bottom. Q4 also lines up with where the low has formed in previous cycles, but also lines with market corrections in mid term years for stocks.
This view is not contrarian at all, Galaxy has a Q4 bottom in the 40k to 46k region and Cowen, CryptoQuant and Brandt are all clustered around September to October.
The question for me is whether the correction will come, as these market conditions can last a long time. In addition if it comes later will that be enough to put a new low in. Despite speculation if BTC dips below the65k mark I will be buying.

Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.