
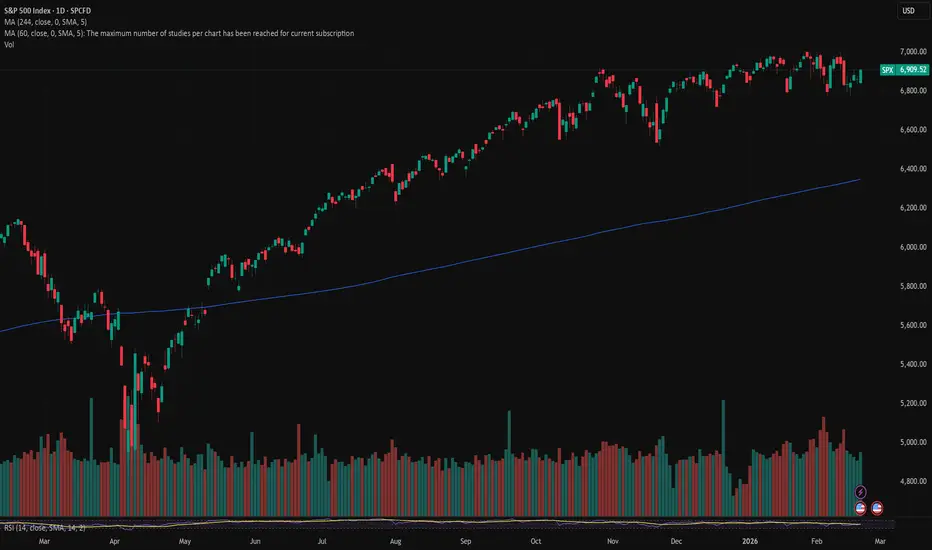
Although investors were negatively surprised with the latest PCE and GDP growth data, still, the markets closed Friday positively, considering the U.S. court decision which ruled out imposed trade tariffs by the current US Administration. The S&P 500 gained over 1% on Friday, closing the week at the level of 6.909. Still, analysts are questioning whether the 7K limit could be broken in the coming period, considering still a lot of insecurities prevailing on the market, from AI large spending and geopolitical topics. In addition, relatively weak PCE and GDP data for December are imposing a question whether the US economy is heading again toward the stagflation. The PCE Price Index in December, at the level of 2,9% y/y was by 0,1pp higher from anticipated. However, GDP Growth for Q4 reached 1.4% q/q, while the market expectations were moving around 3% q/q.
During the week the index was under modest pressure considering news from geopolitics. However, Friday brought a rebound in market sentiment, due to the Decision of the Supreme Court on trade tariffs. Big tech and e-commerce stocks, including Amazon and Alphabet and other large companies included in the index, helped lead the gains. Nvidia was a key market mover mid-week, with its stock rising after announcing a multiyear AI-chip supply deal with Meta Platforms. However, speaking about separate names, investors remained cautious to mixed economic data and ongoing geopolitical uncertainty, with volatility still evident among many S&P 500 companies. Broader tech stocks, including Microsoft, Amazon, and other “Magnificent Seven” names have faced recent valuation pressure as investors debate whether massive AI spending will translate into profits.
Although the week ahead is not bringing too much currently important macro data, still one of the biggest weekly events will be posting of Nvidia quarterly results, scheduled for Wednesday, February 25th. Still, it should be considered that the market remains sensitive to any news related to geopolitical or trade tariffs topics.
During the week the index was under modest pressure considering news from geopolitics. However, Friday brought a rebound in market sentiment, due to the Decision of the Supreme Court on trade tariffs. Big tech and e-commerce stocks, including Amazon and Alphabet and other large companies included in the index, helped lead the gains. Nvidia was a key market mover mid-week, with its stock rising after announcing a multiyear AI-chip supply deal with Meta Platforms. However, speaking about separate names, investors remained cautious to mixed economic data and ongoing geopolitical uncertainty, with volatility still evident among many S&P 500 companies. Broader tech stocks, including Microsoft, Amazon, and other “Magnificent Seven” names have faced recent valuation pressure as investors debate whether massive AI spending will translate into profits.
Although the week ahead is not bringing too much currently important macro data, still one of the biggest weekly events will be posting of Nvidia quarterly results, scheduled for Wednesday, February 25th. Still, it should be considered that the market remains sensitive to any news related to geopolitical or trade tariffs topics.

Penerbitan berkaitan
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Penerbitan berkaitan
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.