ZigZag ATR Pct
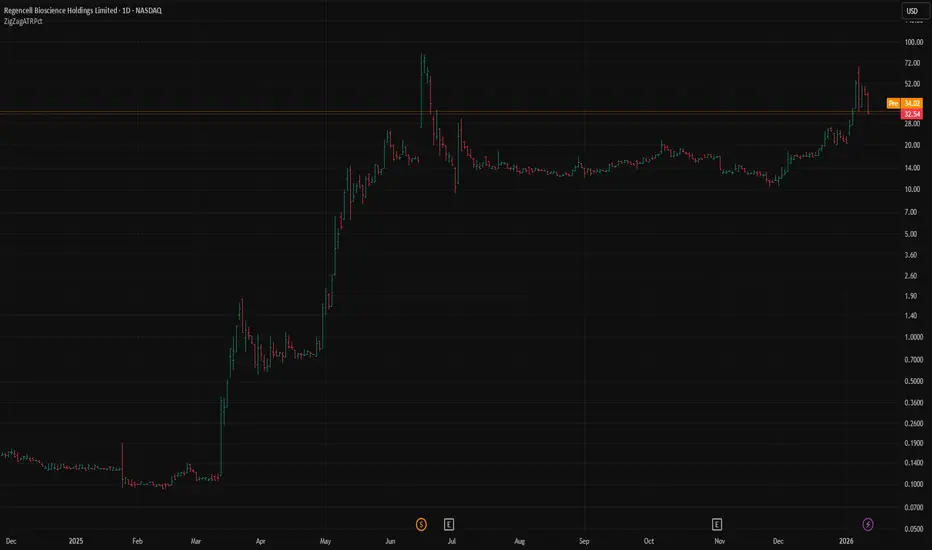
ZigZag ATR % Library
A PineScript v6 library for detecting price pivots based on ATR percentage change (volatility shifts) rather than fixed ATR multiples.
How It Works
Traditional ZigZag indicators use a fixed price threshold to detect pivots. This library takes a different approach: pivots are detected when volatility is changing significantly.
The ATR % change measures how much the Average True Range has shifted over a lookback period:
Pine Script®
Pivots form when |ATR %| exceeds your threshold, capturing turning points during volatility transitions.
Exported Types
Exported Functions
Usage Example
Pine Script®
Parameters
Use Cases
A PineScript v6 library for detecting price pivots based on ATR percentage change (volatility shifts) rather than fixed ATR multiples.
How It Works
Traditional ZigZag indicators use a fixed price threshold to detect pivots. This library takes a different approach: pivots are detected when volatility is changing significantly.
The ATR % change measures how much the Average True Range has shifted over a lookback period:
- Positive ATR % = Volatility expanding (market becoming more volatile)
- Negative ATR % = Volatility contracting (market calming down)
Pivots form when |ATR %| exceeds your threshold, capturing turning points during volatility transitions.
Exported Types
- Settings - Configuration (ATR length, lookback, threshold, display options)
- Pivot - Pivot point data (price, time, direction, volume, ATR %)
- ZigZag - Main state container
Exported Functions
- newInstance(settings) - Create a new ZigZag instance
- update(zz, atr, atrPct) - Update on each bar
- getLastPivot(zz) - Get the most recent pivot
- getPivot(zz, index) - Get pivot at specific index
- getPivotCount(zz) - Get total number of pivots
- calcTR() - Calculate True Range
- calcATR(length) - Calculate ATR using EMA
- calcATRPct(atr, atrPrev) - Calculate ATR % change
- calcPricePct(startPrice, endPrice) - Calculate price % change
Usage Example
Parameters
- ATR Length - Period for ATR calculation (default: 14)
- ATR Lookback - Bars to look back for ATR % change (default: 14)
- ATR % Threshold - Minimum |ATR %| to trigger pivot detection (default: 5.0)
- Depth - Minimum bars between pivots (default: 10)
Use Cases
- Identify reversals during volatility regime changes
- Filter noise during low-volatility consolidation
- Detect breakout pivots when volatility expands
- Build volatility-aware trading systems
This library detects when the market's behavior is changing, not just how much price has moved.

Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.
Penafian
Maklumat dan penerbitan adalah tidak bertujuan, dan tidak membentuk, nasihat atau cadangan kewangan, pelaburan, dagangan atau jenis lain yang diberikan atau disahkan oleh TradingView. Baca lebih dalam Terma Penggunaan.