
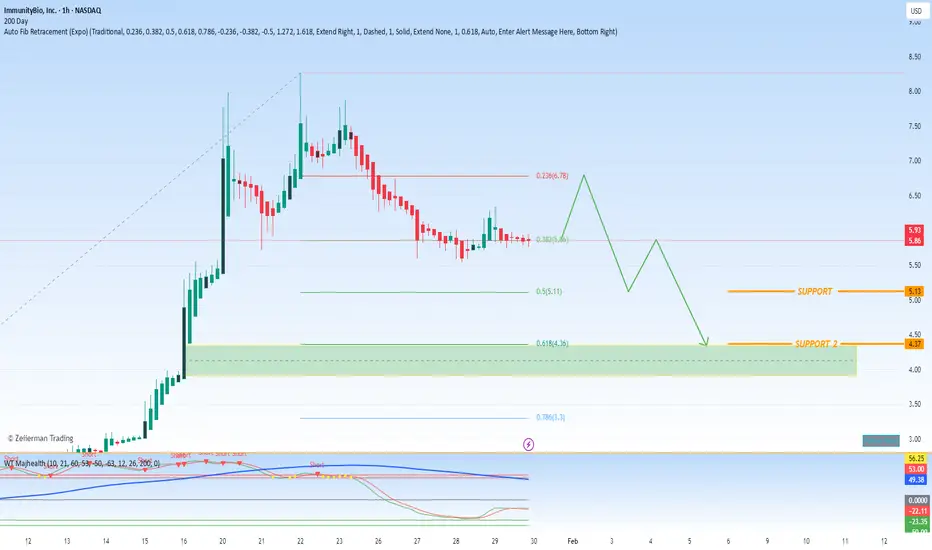
Snapshot of Current Situation
Recent Performance: IBRX experienced an explosive 271% gain in January 2025, driven by strong Anktiva sales data and positive clinical trial momentum. This was followed by a predictable profit-taking pullback, with the stock declining for three consecutive sessions.
Catalyst Ahead: The company is poised to announce detailed results from its QUILT-3.078 Phase 2 study in glioblastoma (GBM), a high-need area with limited treatment options. Early data (19 of 23 patients alive, manageable safety) is promising but preliminary.
Divergent Expert Views: A stark contrast exists between the market's bullish reaction and the caution from figures like Jim Cramer, who has historically criticized the company's long-term losses despite its recent massive rally.
Critical Factors for Investors to Consider
The Bull Case: Transformational Potential
Commercial Acceleration: A 700% year-over-year jump in Anktiva sales signals successful commercialization and strong market uptake for its approved bladder cancer therapy.
Pipeline Catalysts: The upcoming GBM data is a major binary event. Positive results could significantly expand the addressable market and validate the platform's potential in solid tumors.
Technical Momentum: The sheer scale of the recent rally indicates powerful institutional and retail interest, which can be self-reinforcing in the biotech sector.
The Bear Case & Significant Risks
Profitability Concerns: Cramer's central critique—"they've been losing money forever"—remains valid. The company must translate soaring sales into a sustainable path to profitability.
"Buy the Rumor, Sell the News": The stock may have already priced in significant optimism. The GBM data release is a high-risk event; even good data could trigger a sell-off if it doesn't exceed heightened expectations.
Volatility & Valuation: After such a parabolic rise, the stock is highly susceptible to sharp corrections. Valuation metrics are stretched, making it vulnerable to any negative news.
Synthesizing the Cramer Commentary
Cramer's advice embodies a classic trading approach to high-flying biotech stocks:
May 2025: His dismissal of IBRX as "not a great stock" was based on fundamental financials (chronic losses). The market subsequently proved this view too narrow, as it focused on clinical and commercial catalysts.
Recent Take: His current advice to "take profits in some of that, not all of it" is a pragmatic response to the massive run-up. It acknowledges the stock's momentum while advising risk management against a potential steep pullback.
Conclusion: A High-Stakes Balancing Act
ImmunityBio presents a classic biotech dichotomy: spectacular near-term catalyst-driven momentum versus long-term fundamental financial risk.
For existing holders, Cramer's advice to take partial profits is a prudent strategy to lock in gains while maintaining exposure to the upcoming GBM data catalyst.
For potential new investors, entering at this level is highly speculative. It amounts to a leveraged bet on the GBM data exceeding expectations and the company's ability to sustain its commercial growth to eventually justify its valuation.
The immediate future hinges almost entirely on the detailed GBM data. The market will scrutinize not just overall survival, but progression-free survival, quality of life metrics, and the depth of response. Strong data could reignite the rally, while ambiguous or disappointing data could lead to a severe correction.
In essence, IBRX is no longer a story of "if" its therapy works—Anktiva's sales prove it does. The story is now about "how big" the opportunity can become and "how soon" the company can turn transformative science into sustainable profits. The next few weeks will be critical in answering those questions.

Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.
Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.