
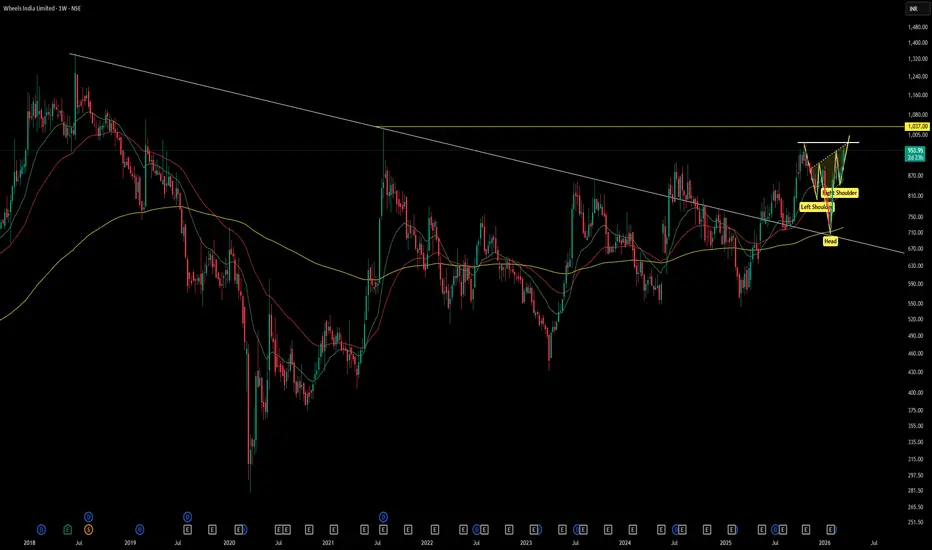
Wheels India Ltd. (NSE: WHEELS) is a mid‑cap company in the auto ancillary sector, specializing in steel wheels, castings, air suspension systems, and precision components for commercial vehicles, passenger cars, tractors, and industrial equipment. Incorporated in 1960, it is part of the TVS Group.
Promoter: TVS Group (Promoter Family) – 57.54% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~8–9% over FY22–FY26, driven by auto demand recovery. → Good
Net Profit: FY26 PAT ~₹210 Cr, reflecting steady growth. → Good
Operating Margin: Maintained ~9–11%, moderate efficiency. → Neutral
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Yield ~1.6% (FY26), consistent payouts. → Good
Asset Building: Expansion of wheel and suspension manufacturing facilities. → Good
Sales: FY26 revenue crossed ₹4,800 Cr. → Good
Expense: Raw material and energy costs remain high. → Neutral
EPS: ~₹95.4 in FY26, reflecting consistent profitability. → Good
Institutional Interest & Ownership Trends
Largest Promoter: TVS Group – 57.54%
Largest FII: Collective foreign institutional investors – ~4.2%
Largest DII: Mutual funds (SBI, HDFC, ICICI) – ~12.1% combined
Retail & Others: ~26.2%
Strategic Moves & Innovations
Expansion into air suspension systems and precision components.
Focus on exports of wheels and castings to Europe and North America.
Investment in automation and advanced manufacturing technologies.
Strengthening OEM partnerships in commercial vehicles and tractors.
Cash Flow & Balance Sheet Strength
Operating cash flows supported by auto sector demand.
Debt levels moderate, manageable with steady profits.
Profit growth supports dividend payouts and reinvestment.
Risk Factors
Dependence on auto demand cycles.
Margin sensitivity to steel and raw material prices.
Competition from global wheel manufacturers.
Export risks due to global trade fluctuations.
Investor Takeaway
Wheels India Ltd. is a key auto ancillary player with strong promoter backing and healthy institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor raw material costs and auto demand cycles, but overall the outlook remains positive for long‑term holders.

Sucrit.D.Patil
Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.
Sucrit.D.Patil
Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.