OPEN-SOURCE SCRIPT
Kalman Trend State [forexobroker]
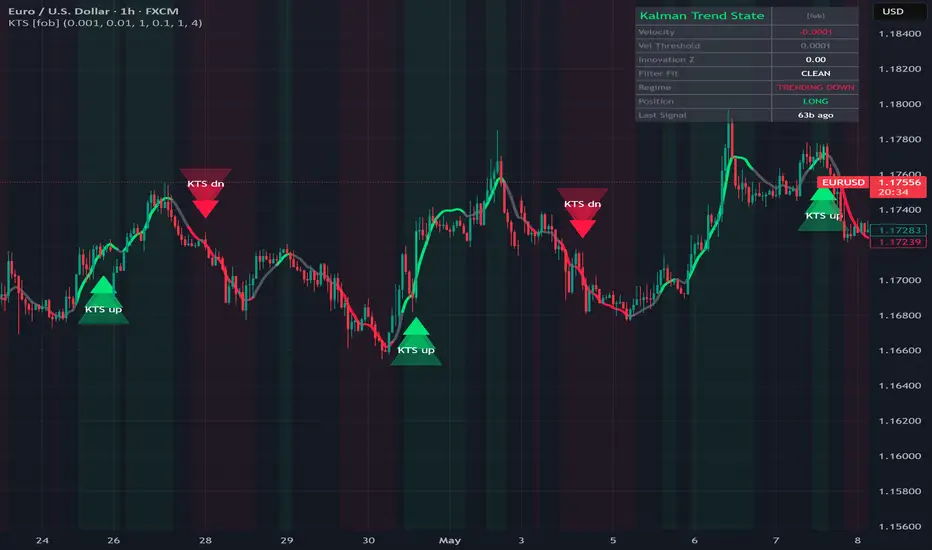
Kalman Trend State applies a recursive Kalman filter to price, treating the unobserved trend as a hidden state with two components: instantaneous price level and per-bar velocity. Unlike a moving average, the filter's smoothing gain updates bar-by-bar from the residuals (innovation), so it adapts to volatility automatically without any length knob.
🔶 ALGORITHM
1. State [px, vx] tracks price and velocity. Transition F = [[1,1],[0,1]] (constant-velocity model).
2. Process noise Q is ATR-adaptive: Q = q_base + q_scale * (ATR / close). Higher volatility = larger Q = faster adaptation.
3. Measurement noise R is fixed (user input). Higher R = filter trusts the model more, smoother output.
4. At each bar: predict (px, P) -> measure close -> update gain K = P_pred * H' / S where S = P_pred[0,0] + R -> correct (px, vx, P).
5. The innovation z-score (close - prediction) / sigma quantifies how well the filter is tracking.
🔶 SIGNAL LOGIC
- Buy: velocity > k * ATR AND |innovation z| <= sigma gate AND close crosses Kalman line up AND not already long AND cooldown elapsed AND barstate.isconfirmed.
- Sell: mirror with velocity < -k * ATR.
- Position-lock state machine prevents same-side over-firing.
🔶 INPUTS
- Process Noise Base Q (default 0.001)
- Q ATR-Pct Scale (default 0.01)
- Measurement Noise R (default 1.0)
- Velocity Threshold x ATR (default 0.10)
- Innovation Sigma Gate (default 1.0)
- Cooldown Bars (default 4)
- Visual: 3-layer glow toggle, Kalman line toggle, dashboard toggle, buy / sell colors
🔶 ALERTS
KTS Buy, KTS Sell, KTS Any Signal, KTS Trend Up Start, KTS Trend Down Start, KTS Clean Fit, KTS Cross Up, KTS Cross Down, KTS Webhook JSON.
🔶 LIMITATIONS
- Kalman is optimal under linear-Gaussian assumptions; price is heavy-tailed, so the filter occasionally lags during regime breaks.
- Warm-up: about 14 bars (ATR seed). Earlier bars have NaN-guarded fallbacks but signals stay flat.
- Defaults tuned for liquid majors and indices on 5m-1H. Re-tune R for tick-driven micro-instruments.
- Velocity threshold scales with ATR but the filter itself does not change shape; for highly seasonal assets, a session-aware variant may help.
Skrypt open-source
W zgodzie z duchem TradingView twórca tego skryptu udostępnił go jako open-source, aby użytkownicy mogli przejrzeć i zweryfikować jego działanie. Ukłony dla autora. Korzystanie jest bezpłatne, jednak ponowna publikacja kodu podlega naszym Zasadom serwisu.

🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.
Skrypt open-source
W zgodzie z duchem TradingView twórca tego skryptu udostępnił go jako open-source, aby użytkownicy mogli przejrzeć i zweryfikować jego działanie. Ukłony dla autora. Korzystanie jest bezpłatne, jednak ponowna publikacja kodu podlega naszym Zasadom serwisu.
🔵Gain access to our powerful tools : kestutisbalciunas.com/tradingview/
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
🔵Join our free telegram for updates : t.me/algotradingedge
All scripts & content provided by Forexobroker are for informational & educational purposes only.
Wyłączenie odpowiedzialności
Informacje i publikacje nie stanowią i nie powinny być traktowane jako porady finansowe, inwestycyjne, tradingowe ani jakiekolwiek inne rekomendacje dostarczane lub zatwierdzone przez TradingView. Więcej informacji znajduje się w Warunkach użytkowania.