

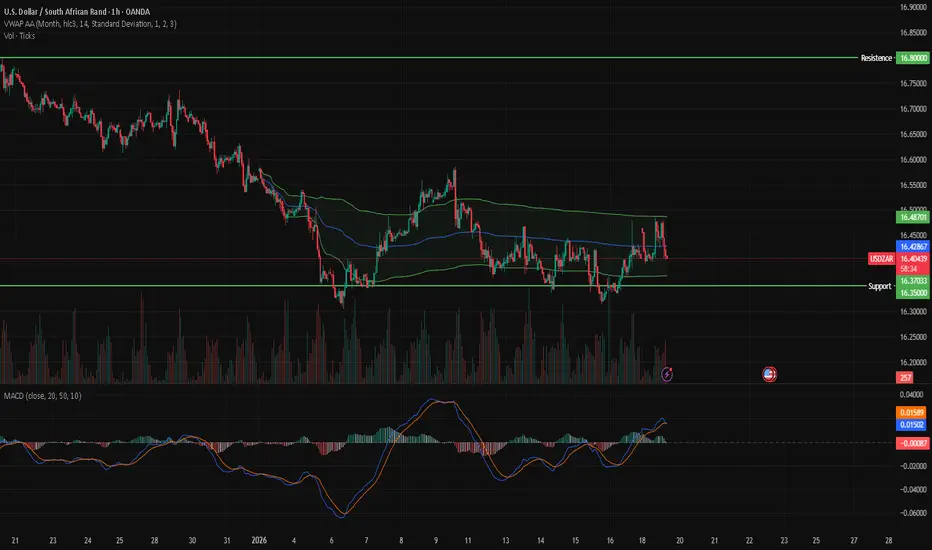
While spot USDZAR remains range-bound, the forward curve continues to price in persistent and stable risk premia beyond the short end, with only marginal week-on-week adjustments. The implication is unchanged: value resides in hedge structuring and tenor selection rather than in directional spot calls.
1. Spot USDZAR: Current Context
USDZAR enters the week trading around 16.41, little changed from last week’s 16.42, reinforcing the view that the market remains in a consolidation regime rather than a trending one.
Key spot reference ranges (week ahead):
Support: 16.35 - 16.45
Resistance: 16.65 - 16.80
Narrative risk level: sustained break above 17.00
From a corporate perspective, the lack of spot momentum continues to argue against aggressive directional positioning and in favour of structured, forward-led hedging strategies.
2. Forward Curve Analysis: Key Signals (Week-on-Week)
2.1 Front-End (0–3 Months): Stable Carry, No Stress Signal
The 1-month forward reference line eased marginally:
Previous 1M: 271 forward points
Current 1M: 249 forward points
This small compression reflects stable interest-rate differentials rather than any material shift in perceived risk. Short-dated forwards remain dominated by policy carry and liquidity, not fear.
Implication:
Short-dated forwards remain efficient execution tools for transactional exposure. There is no evidence of near-term stress being priced into the curve.
2.2 Medium-Term (6-12 Months): Risk Premium Remains Intact
The 12-month reference line edged lower, but the change is minimal:
Previous 12M: 4,537 forward points
Current 12M: 4,472 forward points
Importantly, the curve slope between 1M and 12M remains virtually unchanged:
Previous curve slope: 4,267 forward points
Current curve slope: 4,223 forward points
This suggests the market has not repriced medium-term uncertainty, even as spot prices remain calm.
Implication:
The forward curve continues to reward exporters for hedging medium-term USD receipts.
Importers who delay hedging beyond the short end still face a structural cost, not a temporary mispricing.
2.3 Long-End (2–5 Years): Structural Risk Is Sticky
Structural risk metrics are effectively unchanged week-on-week:
Structural risk premium:
Previous: 21,502 forward points
Current: 21,514 forward points
Risk premium per year:
Previous: 5,376 forward points
Current: 5,379 forward points
Risk premium intensity: steady at 5
This stability is important. It confirms that long-dated forward pricing is not reacting to short-term noise and continues to reflect persistent structural uncertainty rather than cyclical volatility.
Implication:
Long-dated forwards remain:
Attractive for exporters seeking long-term revenue certainty
Expensive for importers, unless certainty is operationally critical
3. Forward-Implied Premiums and Carry Profile
Forward-implied annualised premiums continue to rise gradually with tenor, with no material week-on-week distortion. The dip in the 1-2 month zone remains intact, while the premium curve steepens steadily beyond 6 months.
This configuration signals:
Confidence in near-term stability
Ongoing compensation for long-horizon uncertainty
The curve is therefore pricing time risk, not imminent stress.
4. Implications for Importers (USD Payables)
Importers continue to face an asymmetric curve:
Near-term forwards are efficient and relatively cheap
Medium- and long-term forwards embed persistent structural risk premia
Framework approach:
0-3 months: Hedge a high proportion of known exposure using forwards
3-6 months: Layer hedges opportunistically on spot strength
Beyond 6 months: Consider partial hedging or optionality rather than full cover
Key risk: sudden global risk-off moves can reprice USDZAR spot faster than forward curves adjust.
5. Implications for Exporters (USD Receivables)
Exporters remain structurally advantaged by the forward curve.
Framework approach:
0–3 months: Maintain flexibility
6–12 months: Increase hedge ratios as risk premia accumulate
12–24 months: Attractive zone for strategic hedging and revenue certainty
6. Indicative Spot-Equivalent Action Zones
Importers: 16.45 – 16.60
Importers (defensive): above 16.80
Exporters: 16.65 – 16.85
Exporters (strategic): focus on 6–12 month forwards
7. Importer vs Exporter FX Playbook (Unchanged Bias, Reinforced by Data)
A. Importer FX Playbook (USD Payables)
Core Objective
Protect ZAR cost certainty without overpaying for long-dated structural risk.
Key Update This Week
The absence of curve repricing confirms that delaying hedges does not improve economics beyond the front end.
Strategy
Execute short-dated forwards confidently
Avoid over-hedging beyond 6 months unless margins demand certainty
Risk Triggers
Sustained break above 17.00
Sharp global risk-off events
Domestic credibility setbacks
B. Exporter FX Playbook (USD Receivables)
Core Objective
Lock in forward-curve risk premia while preserving near-term flexibility.
Key Update This Week
Structural premia remain firm and stable, reinforcing the attractiveness of 6–12 month tenors.
Strategy
Gradually raise hedge ratios in the medium term
Use long-dated forwards selectively for budget-critical flows
Opportunity Triggers
USDZAR trading above 16.65–16.85
Further steepening in forward points without spot depreciation
Volatility spikes where forwards adjust faster than spot
This report does not constitute financial advice. The information presented reflects research-based findings, and the analysis is subject to change without notice.
1. Spot USDZAR: Current Context
USDZAR enters the week trading around 16.41, little changed from last week’s 16.42, reinforcing the view that the market remains in a consolidation regime rather than a trending one.
Key spot reference ranges (week ahead):
Support: 16.35 - 16.45
Resistance: 16.65 - 16.80
Narrative risk level: sustained break above 17.00
From a corporate perspective, the lack of spot momentum continues to argue against aggressive directional positioning and in favour of structured, forward-led hedging strategies.
2. Forward Curve Analysis: Key Signals (Week-on-Week)
2.1 Front-End (0–3 Months): Stable Carry, No Stress Signal
The 1-month forward reference line eased marginally:
Previous 1M: 271 forward points
Current 1M: 249 forward points
This small compression reflects stable interest-rate differentials rather than any material shift in perceived risk. Short-dated forwards remain dominated by policy carry and liquidity, not fear.
Implication:
Short-dated forwards remain efficient execution tools for transactional exposure. There is no evidence of near-term stress being priced into the curve.
2.2 Medium-Term (6-12 Months): Risk Premium Remains Intact
The 12-month reference line edged lower, but the change is minimal:
Previous 12M: 4,537 forward points
Current 12M: 4,472 forward points
Importantly, the curve slope between 1M and 12M remains virtually unchanged:
Previous curve slope: 4,267 forward points
Current curve slope: 4,223 forward points
This suggests the market has not repriced medium-term uncertainty, even as spot prices remain calm.
Implication:
The forward curve continues to reward exporters for hedging medium-term USD receipts.
Importers who delay hedging beyond the short end still face a structural cost, not a temporary mispricing.
2.3 Long-End (2–5 Years): Structural Risk Is Sticky
Structural risk metrics are effectively unchanged week-on-week:
Structural risk premium:
Previous: 21,502 forward points
Current: 21,514 forward points
Risk premium per year:
Previous: 5,376 forward points
Current: 5,379 forward points
Risk premium intensity: steady at 5
This stability is important. It confirms that long-dated forward pricing is not reacting to short-term noise and continues to reflect persistent structural uncertainty rather than cyclical volatility.
Implication:
Long-dated forwards remain:
Attractive for exporters seeking long-term revenue certainty
Expensive for importers, unless certainty is operationally critical
3. Forward-Implied Premiums and Carry Profile
Forward-implied annualised premiums continue to rise gradually with tenor, with no material week-on-week distortion. The dip in the 1-2 month zone remains intact, while the premium curve steepens steadily beyond 6 months.
This configuration signals:
Confidence in near-term stability
Ongoing compensation for long-horizon uncertainty
The curve is therefore pricing time risk, not imminent stress.
4. Implications for Importers (USD Payables)
Importers continue to face an asymmetric curve:
Near-term forwards are efficient and relatively cheap
Medium- and long-term forwards embed persistent structural risk premia
Framework approach:
0-3 months: Hedge a high proportion of known exposure using forwards
3-6 months: Layer hedges opportunistically on spot strength
Beyond 6 months: Consider partial hedging or optionality rather than full cover
Key risk: sudden global risk-off moves can reprice USDZAR spot faster than forward curves adjust.
5. Implications for Exporters (USD Receivables)
Exporters remain structurally advantaged by the forward curve.
Framework approach:
0–3 months: Maintain flexibility
6–12 months: Increase hedge ratios as risk premia accumulate
12–24 months: Attractive zone for strategic hedging and revenue certainty
6. Indicative Spot-Equivalent Action Zones
Importers: 16.45 – 16.60
Importers (defensive): above 16.80
Exporters: 16.65 – 16.85
Exporters (strategic): focus on 6–12 month forwards
7. Importer vs Exporter FX Playbook (Unchanged Bias, Reinforced by Data)
A. Importer FX Playbook (USD Payables)
Core Objective
Protect ZAR cost certainty without overpaying for long-dated structural risk.
Key Update This Week
The absence of curve repricing confirms that delaying hedges does not improve economics beyond the front end.
Strategy
Execute short-dated forwards confidently
Avoid over-hedging beyond 6 months unless margins demand certainty
Risk Triggers
Sustained break above 17.00
Sharp global risk-off events
Domestic credibility setbacks
B. Exporter FX Playbook (USD Receivables)
Core Objective
Lock in forward-curve risk premia while preserving near-term flexibility.
Key Update This Week
Structural premia remain firm and stable, reinforcing the attractiveness of 6–12 month tenors.
Strategy
Gradually raise hedge ratios in the medium term
Use long-dated forwards selectively for budget-critical flows
Opportunity Triggers
USDZAR trading above 16.65–16.85
Further steepening in forward points without spot depreciation
Volatility spikes where forwards adjust faster than spot
This report does not constitute financial advice. The information presented reflects research-based findings, and the analysis is subject to change without notice.

Отказ от ответственности
Информация и публикации не предназначены для предоставления и не являются финансовыми, инвестиционными, торговыми или другими видами советов или рекомендаций, предоставленных или одобренных TradingView. Подробнее читайте в Условиях использования.
Отказ от ответственности
Информация и публикации не предназначены для предоставления и не являются финансовыми, инвестиционными, торговыми или другими видами советов или рекомендаций, предоставленных или одобренных TradingView. Подробнее читайте в Условиях использования.