Liquidity Hunter | SMC System - Full Suite
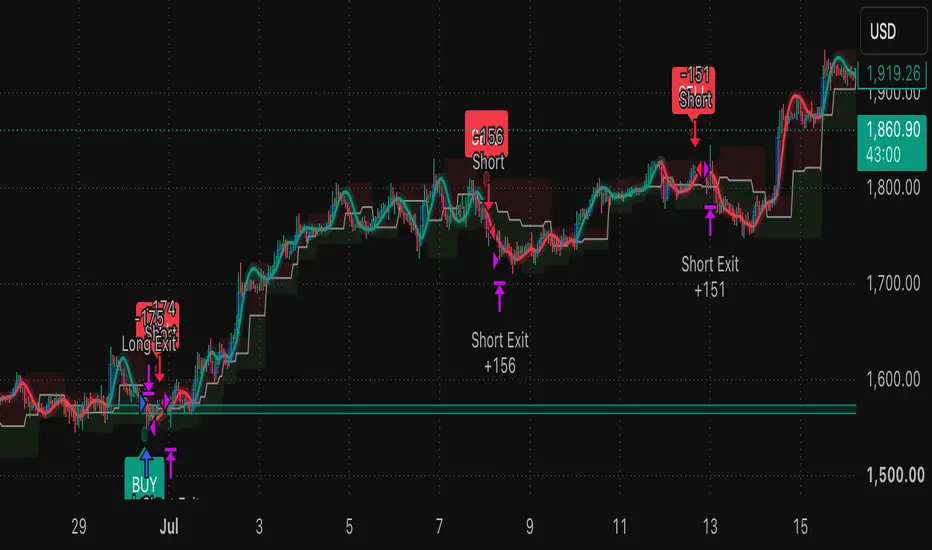
A full-sequence Smart Money Concepts strategy that trades the way institutional order flow moves — liquidity sweep, displacement, structure break, and a confirmed retest.
This strategy chains them into the complete institutional sequence: a real liquidity pool gets taken, an impulsive displacement candle breaks structure, a correctly-identified order block gets frozen at that exact moment, and only a genuine retest with confirmation triggers the entry.
Features
The Full SMC Sequence
Real Liquidity Pool Tracking
Displacement Filter
Frozen-Zone Retest Logic
Configurable Confirmation Filters
Higher Timeframe Bias
FVG Confluence Option
Liquidity-Target Take Profit
Risk-Based Position Sizing
Realistic Cost Modeling
Notes
This strategy chains them into the complete institutional sequence: a real liquidity pool gets taken, an impulsive displacement candle breaks structure, a correctly-identified order block gets frozen at that exact moment, and only a genuine retest with confirmation triggers the entry.
Features
The Full SMC Sequence
- HTF Bias → Liquidity Pool Taken → Sweep → Displacement Candle → BOS/CHoCH → FVG → Return to OB → Confirmation → Entry — every stage gated on the one before it, so entries reflect genuine confluence rather than a single coincidental signal.
Real Liquidity Pool Tracking
- Tracks multiple historical swing highs/lows simultaneously (not just the most recent one), so a sweep can trigger off any untaken pool — mirroring how liquidity actually accumulates at equal highs/lows and older structure.
Displacement Filter
- Structure breaks only count as valid if the breaking candle's body exceeds a configurable ATR multiple — filters out slow grinds through a level that aren't genuine institutional impulses.
Frozen-Zone Retest Logic
- Once an OB forms, its boundaries are locked/frozen at that moment. Entries reference this frozen snapshot, not a live, potentially-mutated box — with an overlap-based touch test (not a strict "price must sit inside the zone" test) for realistic retest detection.
Configurable Confirmation Filters
- After a retest touch, choose from: no confirmation, rejection candle, engulfing candle, close back through the OB, or a break of the retest candle's high/low — tune entry strictness to your risk tolerance.
Higher Timeframe Bias
- Optional HTF trend filter ensures you're only taking setups aligned with the dominant trend on a higher timeframe.
FVG Confluence Option
- Optionally require that the structure break actually creates a fair value gap — an added imbalance-based confluence layer before a setup is even considered.
Liquidity-Target Take Profit
- Choose a fixed R-multiple target, or let the strategy aim at the nearest untaken liquidity pool in the trade's direction — closer to how institutional targets are actually theorized to work.
Risk-Based Position Sizing
- Size trades by % risk per trade (scaled to actual stop distance) or flat % of equity, with a hard position-size cap.
Realistic Cost Modeling
- Commission and slippage built into the backtest engine from the start.
Notes
- Start with requireOBRetest = true and confirmationMode = "None" to validate the base sequence produces trades before layering on stricter confirmation modes.
- HTF Bias and FVG Confluence are off by default — each meaningfully reduces trade frequency in exchange for higher-conviction setups; enable incrementally and check trade count after each change.
- Works on any intraday or swing timeframe — the sequence logic (sweep → displacement → BOS → retest) is timeframe-agnostic, though displacement thresholds and pool aging windows may need retuning per timeframe.
- "Nearest Liquidity Pool" take-profit mode requires active, untaken pools in the trade's direction to function — falls back to the R-multiple target if none exist.

Отказ от ответственности
Информация и публикации не предназначены для предоставления и не являются финансовыми, инвестиционными, торговыми или другими видами советов или рекомендаций, предоставленных или одобренных TradingView. Подробнее читайте в Условиях использования.
Отказ от ответственности
Информация и публикации не предназначены для предоставления и не являются финансовыми, инвестиционными, торговыми или другими видами советов или рекомендаций, предоставленных или одобренных TradingView. Подробнее читайте в Условиях использования.