Индикатор

RedK Multi-Modal TrailingStop (RedK MMTStop)█ RedK MMTStop - Release Notes
Introduction & background
RedK MMTStop is a Multi-Modal Trailing Stop indicator - Let's quickly explore the "trailing stop" concept first as a refresher - then explain what a multi-modal trailing stop indicator does.
A "Trailing Stop" is what helps traders avoid giving back profit because they held an open position for too long. A trailing stop follows (trails) the price movement in the trade direction - never moves in the opposite direction - as long as the position moves in the trade direction, the trader is watching a growing "unrealized profit".
The Trailing Stop will then alert the trader when the move is weakening, or is over (reversing). The position is then closed (automatically if the platform provides that feature, or manually by the trader) to "realize" the maximum profit.
Read more about this concept in TradingView's own support guide on Trailing Stops
A Trailing Stop is a core function for effective position & risk management, and there are various methods to implement a trailing stop. Regardless of the trailing stop method, the basic premise is the same: this mechanism is what enables the trader to maximize their position profit, and is the key to avoiding situations where profitable positions reverse into losses - which can happen to any trader, regardless of experience level - it's just the nature of trading. For that reason, there are so many Trailing Stop indicators out there, and many of them are of high quality.
What makes RedK Multi-Modal TrailingStop (RedK MMTStop) different, is that it provides traders with 5 of the most-common trailing stop methods, and packages these 5 methods into the same insights, visuals and alerts engines - in an attempt to deliver maximum trade management support with the utmost flexibility in the choice of trailing stop method - The result is a tool that can work for any style of trading (scalping, swing, position/trend...), for any timeframe, and for any traded instrument, be it FOREX, Crypto, Futures, Stocks, CFDs ...etc.
█ RedK MMTStop: Indicator Components
Below we explore the 5 trailing stop methods, the trader's insights (info panel), the visuals (the safe zone / bands) and the alerts.
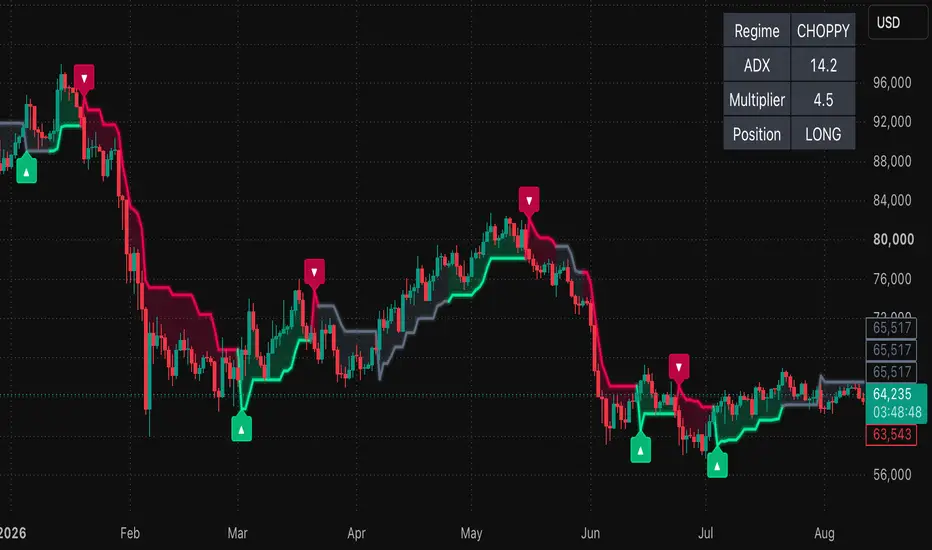
The below screenshot shows the main elements of the RedK MMTStop
🔷1. The 5 Trailing Stop Methods
ATR / Supertrend: trails a volatility-based distance from price. The classic all-purpose stop.
Chandelier: hangs an ATR distance off the recent swing high (long) or low (short).
Donchian: trails to the recent swing low (long) or high (short). Turtle-style, structure-based.
StdDev Channel: trails a standard-deviation / statistical (Bollinger-style) distance.
Fixed %: trails a set percentage of price. Simple and predictable.
Switching method never changes the insights, the visuals or the alerts. Every method feeds the same stop line, the same flip logic, and the same five alerts — so your setup keeps working as you adjust to find the method that works best for a specific setup.
🔷 2. The Critical & Safe Zones
The stop line tells you where to exit. The Status line (along with the Critical / Safe bands) tells you how close you are.
The "Status Line" measures the gap between price and the stop in ATR units, then colors it:
🟢 Safe — plenty of room. Let it run.
🟡 Watch — getting close. Pay attention.
🔴 Critical — price is near the stop line. Decide now.
The colored bands sit between the stop and price on the chart. Band borders can be shown or hidden separately from the colored fill. The Safe Zone is calculated based on (user-adjustable) ATR value, so it is "volatility-aware" - It uses its own ATR setting (regardless of the selected Trailing Stop method) to ensure it works the same across all five methods — including the ones with no ATR setting of their own.
🔷3. The Info Panel
A compact panel showing the live state at a glance (some elements will update in real time):
Active trailing stop method and its key setting - color coded for direction
Current stop price and trade side
Distance from price to stop
Color-coded Status Line (Safe / Watch / Critical) with distance to stop in ATR units
The exact prices where the colors (zones) transition
For the Info Panel, text size (Small / Normal / Large) and position (Top / Middle / Bottom Right) are selectable.
🔷4. RedK MMTStop Alerts
There are 5 alerts introduced in this version to help maximize the use of the RedK MMTStop - These alerts work the same regardless of which trailing stop method is selected and the associated settings - They will also work regardless of the visual or the info panel settings.
Trend flipped up
Trend flipped down
Close crossed below the stop
Close crossed above the stop
Price entered the Critical zone
Note: A numeric flip signal is also exposed in the Data Window for use with the Pine Screener.
The below screenshot shows the 5 alerts provided by RedK MMTStop
==================================================================================
█ RedK MMTStop Indicator Settings & Usage Examples
The screenshot below shows the RedK MMTStop indicator settings box, split into 3 sections, and what each section does.
The below screenshot shows a "position trader" using RedK MMTStop on 1D timeframe to manage 5% -based trailing stops on NASDAQ:NVDA - showing examples for both a long and a short positions and how to use the indicator to identify critical zones for exit.
The below screenshot shows a swing trader using RedK MMTStop on 30min timeframe to track an ATR / SuperTrend -based trailing stop on an open long position in OANDA:XAUUSD - the position is getting an amber "Watch" alert in the Info Panel
With the way RedK MMTStop is built, the scenarios are unlimited - Please note that while every effort was made to provide the most commonly used settings for each method as default - they are not suggestions or advice - You need to adjust your trailing stop method and settings to what suits your style of trading, your timeframe and your own risk tolerance. This is critical for the proper use of this, or any other, indicator.
==================================================================================
📝 Notes on Use and Limitations
==================================================================================
This is an analysis and risk-management tool, not a signal service and not trade advice. Also a trailing stop is a mechanism that helps you manage an existing position — it does not tell you what or when to buy or sell. Test any settings on your own instruments and timeframes before trading them.
The markers and alerts here describe price action readings. They are not advice to enter or exit any position, and the indicator does not claim predictive accuracy.
==================================================================================
⚠️ Important Notes & Disclaimer
==================================================================================
Using this indicator means you have read and agreed to the following:
Not Advice. This indicator, and other work of this author, represent analytical studies of price and volume behavior. No parts should be considered buy/sell recommendations or signals — “Bulls” and “Bears” describe measured states only. Nothing here is financial, investment, or trading advice.
Risk & Responsibility. Trading involves substantial risk of loss and is not for everyone. All decisions, interpretation, and risk and money management are yours alone. Past behavior does not predict future results. The author accepts no liability for any loss or consequence arising from use of this tool.
Indicator Provided As-Is. Feature requests are welcome and can be shared with the author, but whether or when any request is implemented cannot be promised or guaranteed.
Индикатор

Daily Swing Trader PRO v3.2 # Daily Swing Trader PRO
**Daily Swing Trader PRO** is a rules-based swing-trading indicator designed primarily for traders who use the **daily chart** and want a simple way to combine trend, momentum, volume, volatility, entry quality, and risk management into one TradingView script.
The indicator is built around a **trend + pullback/breakout + confirmation** approach. Instead of relying on a single indicator, it combines several commonly used technical tools to identify higher-quality swing-trading setups.
## Main Features
Daily Swing Trader PRO includes:
* 10 EMA
* 21 EMA
* 50 SMA
* 200 SMA
* SuperTrend
* RSI
* Relative Volume (RVOL)
* ATR and ATR %
* Bullish pullback detection
* Bullish breakout detection
* Bearish breakdown detection
* Bearish failed-rally detection
* BUY signals
* STRONG BUY signals
* SELL signals
* STRONG SELL signals
* Automatic entry level
* Automatic stop-loss level
* Configurable reward/risk target
* TAKE PROFIT signals
* STOP LOSS signals
* Detailed TradingView alerts
* Daily Swing dashboard
* Signal notification panel
* Automatic light/dark chart theme support
## Trading Philosophy
The indicator follows a simple principle:
**Trend first → Price action second → Volume and momentum confirmation → Risk/reward → Trade**
Indicators are used as confirmation rather than as standalone reasons to enter a trade.
The goal is to avoid weak setups, avoid chasing extended stocks, and focus on trades where multiple technical factors are aligned.
# How to Use Daily Swing Trader PRO
## Recommended Timeframe
The indicator is designed primarily for the:
**1-Day / Daily chart**
The default settings are optimized around daily-chart swing trading.
## Bullish Trend Requirements
The script looks for a bullish environment when:
* Price is above the 50 SMA
* Price is above the 200 SMA
* Price is above the 21 EMA
* 10 EMA is above the 21 EMA
* 21 EMA is rising
* SuperTrend is bullish
* RSI is above 50
* Relative volume meets the selected minimum
* ATR volatility meets the minimum requirement
* Price is not excessively extended above the 21 EMA
These conditions help reduce signals that occur during weak or sideways trends.
## BUY Signal
A **BUY** signal can occur when the bullish trend requirements are satisfied and one of the following setups appears:
### Pullback Setup
Price pulls back toward the 10 EMA or 21 EMA and then shows bullish confirmation.
Typical confirmation includes:
* Price holding the EMA support area
* Bullish daily candle
* Close above the previous day's high
* Price closing back above the 10 EMA and 21 EMA
* Adequate relative volume
This setup attempts to enter an existing trend after a controlled pullback instead of chasing price.
### Breakout Setup
A breakout setup occurs when price closes above the highest price of the selected breakout lookback period.
The indicator also requires bullish trend, momentum, volume, and volatility conditions before generating the signal.
## STRONG BUY Signal
A **STRONG BUY** requires the normal BUY conditions plus stronger confirmation.
Default requirements include:
* Bullish trend
* Valid pullback or breakout
* RSI approximately 55–70
* RVOL of at least 1.20
* Strong bullish candle close
* Price not excessively extended
* Bullish SuperTrend
STRONG BUY is intended to identify the highest-quality bullish setups produced by the system.
## SELL Signal
SELL is the bearish counterpart to BUY.
The script looks for:
* Price below the 50 SMA
* Price below the 200 SMA
* Price below the 21 EMA
* 10 EMA below the 21 EMA
* Falling 21 EMA
* Bearish SuperTrend
* RSI below 50
* Adequate relative volume and volatility
A SELL signal may occur after either a bearish breakdown or a failed rally into resistance.
For traders who only trade long positions, SELL can also be used as a warning that bullish conditions have deteriorated.
## STRONG SELL Signal
A **STRONG SELL** requires additional bearish momentum and volume confirmation.
It is designed to identify the strongest bearish setups and may be useful for traders evaluating short positions or long-put option setups.
# Entry, Stop and Take Profit
When a new trade signal appears, the script automatically calculates:
**Entry:** Signal candle closing price
**Stop Loss:** Based on the recent swing high or swing low plus an ATR buffer
**Take Profit:** Based on the selected reward/risk multiple
The default target is:
**2R — approximately 2:1 reward/risk**
Example:
Entry: $100
Stop: $95
Risk: $5
2R Take Profit: $110
The reward/risk target can be adjusted in the indicator settings.
## Stop-Loss Logic
For long trades, the stop is placed below a recent swing low.
For bearish trades, the stop is placed above a recent swing high.
An ATR buffer is added to reduce the chance of being stopped out by normal price movement.
## Take-Profit Logic
When price reaches the calculated target, the indicator produces a:
**TAKE PROFIT**
signal.
The script also tracks STOP LOSS events.
Because a daily candle only provides open, high, low, and close information, if both the stop and profit target are touched on the same daily candle, the script uses the conservative assumption that the stop was reached first.
# Avoiding Extended Trades
One of the most important filters in Daily Swing Trader PRO is the **maximum extension from the 21 EMA**.
The default is:
**2 ATR**
If price becomes too extended above or below the 21 EMA, new entries are filtered out.
This is designed to reduce late entries after unusually large price moves.
# Relative Volume
Relative Volume compares current volume with average recent volume.
Default values:
Normal signal: **RVOL ≥ 1.00**
Strong signal: **RVOL ≥ 1.20**
Higher RVOL generally indicates stronger participation behind the move.
# RSI
RSI is used as a momentum filter rather than simply as an overbought/oversold indicator.
For bullish trades, the script generally looks for RSI above 50.
STRONG BUY signals typically require RSI in the stronger momentum zone of approximately:
**55–70**
Bearish signals use the opposite momentum structure.
# ATR
ATR is used for several purposes:
* Measuring volatility
* Preventing trades in stocks with insufficient movement
* Measuring price extension
* Calculating stop buffers
* Helping evaluate swing-trading opportunity
The dashboard displays both ATR and ATR as a percentage of price.
# Dashboard
The **Daily Swing Dashboard** appears in the top-right corner of the chart.
It displays information such as:
* Current trend
* Trade status
* Last signal
* Setup type
* RSI
* RVOL
* ATR
* ATR %
* Entry
* Stop
* Profit target
The **Signal Notification Panel** appears in the bottom-right corner and displays the most recent trading event.
# TradingView Alerts
The indicator includes individual alert conditions for:
* STRONG BUY
* BUY
* STRONG SELL
* SELL
* TAKE PROFIT
* STOP LOSS
Detailed alerts can include:
* Ticker
* Current price
* Entry
* Stop
* Take-profit target
* Reward/risk
* RSI
* RVOL
* ATR
* ATR %
For daily swing trading, alerts are best evaluated after the daily candle has closed so that the setup is confirmed.
# Suggested Workflow
A practical workflow is:
1. Start with stocks already showing a strong trend.
2. Use the daily chart.
3. Wait for BUY or STRONG BUY rather than chasing large candles.
4. Check nearby support and resistance.
5. Confirm that the profit target has enough room before major resistance.
6. Review earnings and major market-event risk.
7. Enter only if the chart still offers acceptable reward/risk.
8. Use the calculated stop rather than widening the stop after entering.
9. Take profit at the target or manage the position with your own trailing-stop rules.
For conservative use, traders may choose to treat:
**STRONG BUY / STRONG SELL = potential trade signals**
and
**BUY / SELL = watchlist or early-warning signals**
# Default Settings
The default settings are intended as a starting point:
10 EMA: 10
21 EMA: 21
50 SMA: 50
200 SMA: 200
SuperTrend ATR: 10
SuperTrend Factor: 3.0
RSI: 14
RVOL Lookback: 20
Normal RVOL: 1.00
Strong RVOL: 1.20
ATR: 14
Maximum Extension: 2 ATR
Swing Stop Lookback: 5 bars
Take Profit: 2R
Different securities and market conditions may require different settings.
# Important Notes
Daily Swing Trader PRO is not designed to predict the market.
No technical indicator can guarantee profitable trades. Signals should be combined with proper position sizing, risk management, market context, support and resistance, earnings awareness, and individual trading judgment.
Historical signals do not guarantee future performance.
This indicator is provided for educational and informational purposes only and should not be considered financial or investment advice.
Индикатор

Split ATRSplit ATR cuts every bar at two ATR envelopes — one around the open, one around the close — and draws the result as stacked candles. Hue is the bar’s volume change; lightness is whether each slice closed up or down; chroma is how surprising that slice is relative to those envelopes.
A sibling of Split VWAP. Same overdraw, same volume-hue coloring. The cut is different. Chroma is the new channel.
The cut
ATR is read from a lower timeframe so one chart bar contains several sub-bars. Auto is one-fifth of the chart: 1 minute on a 5-minute chart, 3 minutes on a 15-minute chart. The ATR length is a chart-bar window, scaled onto that subseries, so 14 on a 5-minute chart is 70 one-minute bars — the same span of time as ATR(14) on the chart.
Two values come off that series:
Open ATR — ATR on the first sub-bar of this chart bar
Close ATR — ATR on the last sub-bar of this chart bar
Those make two intervals, then the four endpoints are sorted in price order:
Open ± Open ATR
Close ± Close ATR
The four prices make five bands. A cut past the bar clamps onto the near extreme and collapses the empty band. A bar with no ATR yet is drawn whole and colored as the unsurprising core.
On the bar still forming, the first and last sub-bar start as the same bar, so open ATR equals close ATR until a second sub-bar appears. Open ATR then freezes; close ATR keeps updating.
What the slices mean
Each band is a slice of the bar. Membership of the slice midpoint decides how surprising it is:
In both envelopes — consensus core. Within typical reach of where the bar began and where it ended. Surprise 0.
Open only — departed. The bar left this zone behind. Surprise 0.5.
Close only — arrived. The bar moved into this zone. Surprise 0.5.
In neither, between them — the gap. Only exists when the two intervals are disjoint. Surprise 1.
In neither, outside both — excursion. Wick territory neither envelope accounts for. Surprise 1.
Color
Hue is the whole bar’s volume change. Red when volume fell, green when it held, blue when it rose. Every slice of the bar shares that hue. A symbol with no volume (an index) still splits; hue sits on the unchanged-volume green, and surprise and price lightness still color the slices.
Chroma is ATR surprise. The core is washed toward gray (Unsurprising chroma, default 0.25). Gap and excursion keep the full chroma. Departed and arrived sit halfway.
Lightness is closed-up / closed-down: each slice against the previous bar’s same-index close. An up close is the anchor color; a down (or unchanged) close is the same hue a step darker.
Up bodies are hollow. Wick and border stay opaque so the overdraw still hides the dash under a hollow middle.
The script draws in front of the chart’s own bars and covers them, so you do not need to hide the symbol by hand. Open ATR and Close ATR are what the status line and Data Window report.
Settings
Lower timeframe — Auto (1/5 of chart), or Custom. Must be shorter than the chart.
ATR length — chart-bar window (default 14). Scaled onto the lower timeframe.
ATR multiplier — scales both ATR values before the cuts are placed.
Unsurprising chroma — how much color the consensus core keeps.
Price down darkening — how much darker a down slice is than an up slice.
Volume-hue anchors — falling / unchanged / rising volume.
Built around a 5-minute chart with Auto (or Custom 1). Color conversions use the OKLCh library. Индикатор

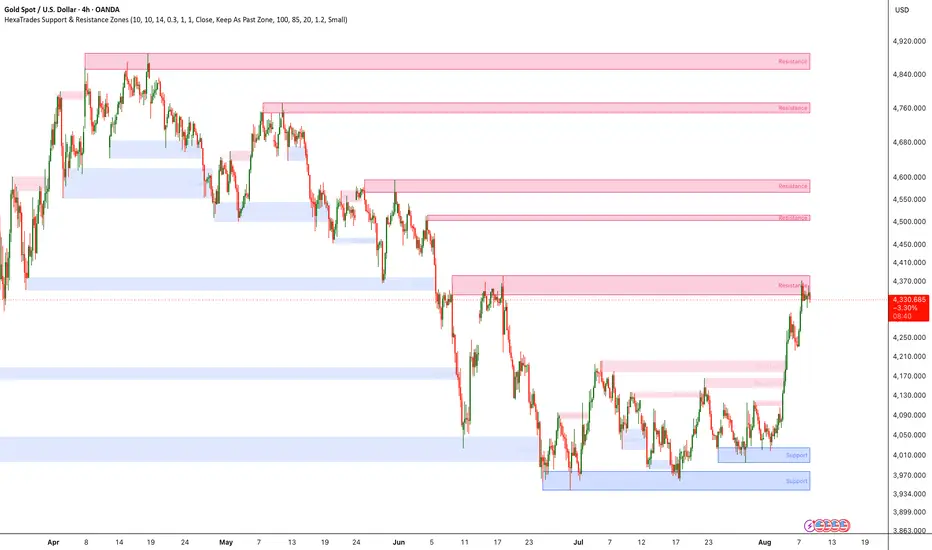
Range Breakout by AVRange Compression Breakout
Volatility compression and expansion system
Range Compression Breakout automatically detects periods of low-volatility consolidation, draws and maintains the range in real time, and signals when price transitions into expansion.
How it works
Compression is measured relative to the market's own recent behavior rather than a fixed price distance. In Adaptive Percentile mode, a range qualifies when its high-low span sits among the quietest percentile of its recent history — so the same settings work across futures, FX, crypto, and equities without retuning. ATR Multiple mode is also available for a fixed volatility-based threshold.
Once a range is detected, the box is dynamic. While price stays contained, the box expands to absorb new highs and lows, capturing the full churn of the consolidation instead of resetting on every probe.
Signals
Break — price closes decisively beyond the boundary plus a buffer, with optional multi-bar confirmation and an optional volume-spike filter.
Wick Long / Wick Short — a failed probe outside the range that closes back inside on a long wick, confirmed by the following bar, indicating mean reversion toward the midline.
A cooldown period after each break prevents the box from immediately reforming on the expansion move.
Settings
Four preset profiles — Tight Ranges for low-timeframe scalping, Normal Ranges for intraday, Swing Trading for multi-day consolidations, and Options Selling for extended sideways chop — each configuring lookback, tightness, minimum bars, confirmation, and cooldown. Custom mode exposes all parameters. Box fill, borders, midline, and signal colors are fully adjustable, and each signal type toggles independently.
Alerts
Range Detected, Range Breakout, Breakout with Volume Confirmation, and Range Reversal.
Notes
Volume confirmation should be left off on spot FX and other symbols reporting tick-based volume. Diagnostic values including the range-to-ATR ratio and compression state are available in the Data Window for calibration. Индикатор

Индикатор

Sweep & Reverse | Liquidity Sweep Reversal StrategyThis strategy trades the liquidity-sweep reversal pattern: price wicks through a prior swing high or low — clearing out the stops resting there — then closes back inside the range, suggesting the move beyond that level was a stop-hunt rather than a genuine breakout.
How it works:
Confirmed swing highs and lows (via pivot detection) are stored as watched levels.
A sweep triggers when a bar wicks past a level but closes back on the other side.
Longs enter on swept lows, shorts on swept highs. The stop sits just beyond the sweeping wick (with an ATR buffer); the target is set from your chosen reward:risk ratio.
Levels expire if left untouched for too long, and new levels too close to an existing one (relative to ATR) are skipped to keep zones from cluttering.
Features:
Optional volume-spike filter — only counts sweeps backed by above-average volume
Optional rejection-wick filter — requires the sweeping wick to be meaningfully larger than the bar's body, filtering out weak/low-conviction sweeps
Optional next-bar confirmation — waits one bar past the sweep and only enters if price actually continues in the reversal direction, reducing whipsaw entries
Optional session window filter (defaults to the London/NY overlap, the highest-liquidity window)
Adjustable stop distance, minimum stop size, and reward:risk ratio
Breakeven stop management once a trade moves partway to target
Long/short can be toggled independently
Every trade's entry/SL/TP lines persist on the chart after the trade closes (auto-expiring after a configurable number of bars), so past trades stay visible for review
Styled performance dashboard: trade count, win rate, net profit, live position state
Warnings:
This is fundamentally a mean-reversion pattern. In strongly trending markets, sweeps frequently continue rather than reverse — no combination of filters here eliminates that risk.
Backtest results are sensitive to pivot length, stop distance, and which filters are enabled. A high win rate on a small number of trades is not statistically meaningful — test across multiple instruments and timeframes, and evaluate profit factor and max drawdown alongside net profit, not net profit alone.
Past performance in a backtest, including this one, does not guarantee future results. This is not financial advice. Стратегия

TF: Trend Participation Monitor (TPM)TradingFlow: Trend Participation Monitor (TPM)
TradingFlow: Trend Participation Monitor (TPM) combines price behavior and relative volume in a separate pane to show recent directional pressure and whether that pressure is improving or deteriorating relative to its recent average.
TPM is designed to track relatively short-term changes in price/volume pressure. The time horizon depends on the chart timeframe and lookback settings.
TPM separates the level of pressure from the change in pressure. Positive pressure can be weakening, while negative pressure can be recovering. This helps traders distinguish the direction of recent price/volume behavior from changes in its strength.
TPM is a pressure monitor, not a predictive reversal indicator or a standalone entry and exit system.
Price and Participation Model
The model combines two components with equal weight: directional price efficiency and relative-volume-weighted bar pressure.
Price efficiency compares net price movement with the total distance traveled by consecutive closes. Bar pressure combines the close-to-close move, normalized by the previous bar's ATR, with the close's position within the candle range. Close-to-close movement includes gaps; closing near the high after a gap down does not automatically make the bar positive.
Relative volume compares each bar's volume with the average of preceding bars. Its contribution is capped to limit the influence of isolated volume spikes. The result is smoothed into a pressure score bounded between -100 and +100. This is a price/volume proxy, not actual buy/sell volume or measured capital flows.
Pressure and Reference Lines
The blue line shows pressure. Values above zero indicate positive pressure within the model, while values below zero indicate negative pressure. The gray line is a slower average of that pressure, providing a reference for recent change.
Recent Change Histogram
The histogram equals half the difference between pressure and its reference. It measures pressure relative to its recent average, rather than price direction or the change from just one bar ago.
With default settings, a change score must remain at or above +5, or at or below -5, for two consecutive bars to receive a confirmed directional color.
Four-Shade Color System
Purple represents confirmed improvement; gold represents confirmed deterioration.
Gray: the threshold or confirmation requirement has not been met.
Darker shades indicate columns growing away from zero; lighter shades indicate columns shrinking toward zero or remaining unchanged, compared with the preceding bar. Gray does not mean price is stable, and a lighter gold column can still represent confirmed deterioration even as its magnitude decreases.
Compact Dashboard and Activity Context
The compact table shows the displayed bar status, recent condition, and pressure/change values. The optional detailed view adds volume, rolling relative volume, estimated stock traded value, optional free-float turnover, and data status.
Estimated traded value uses typical price multiplied by volume. Turnover requires a manually supplied free-float figure in millions of shares. Both are stock-only context measurements and do not contribute additional votes to the pressure score. A fixed float figure may not represent historical share counts accurately.
Closed-Bar Display and Alerts
By default, the indicator holds the last completed bar's readings while the current candle forms. Disabling this option displays provisional live values and colors that may change before the bar closes. Alerts remain restricted to bar close and identify newly confirmed improvement or deterioration. They confirm observed pressure changes; they do not identify the start of a price trend.
Volume Data Handling
Missing or invalid volume, a zero-volume evaluated bar, and insufficient usable activity suppress pressure output and alerts. The pressure window needs at least two bars with usable positive volume weights. After missing data, a valid recovery window is required before output resumes. Small positive volume is supported, but thin trading can still produce noisy readings.
How to Read the Chart
Positive pressure with purple columns means pressure is positive and sufficiently above its reference. Positive pressure with gold columns means it remains positive but has weakened relative to that reference.
Negative pressure with purple columns indicates recovery within negative pressure, not a confirmed bullish reversal. A histogram near zero means pressure is close to its reference; it does not establish a sideways price trend.
Flexible Configuration
Users can adjust the activity baseline, pressure window, smoothing, reference length, ATR length, volume cap, change threshold, confirmation period, histogram colors, and dashboard display.
The defaults are intended as a starting point for daily stock charts. All lengths count chart bars. On intraday charts, relative volume uses a rolling-bar comparison, not a same-time-of-day comparison, so session openings, closings, and extended hours can affect readings. Use standard candles and consider the meaning of the symbol's volume feed.
Practical Use
TPM is best approached as a short-term reference when considering entry and exit timing. Its relatively responsive readings can change frequently within an ongoing move, so using every change to reassess an open position may encourage unnecessary second-guessing. For holding decisions, give greater weight to your trading timeframe, broader price structure, and original trade plan. A change in TPM alone is not a reason to enter or exit.
TPM can help assess changes in price/volume pressure during advances, pullbacks, and consolidations. Read it alongside price structure and market context. Smoothing and confirmation introduce delay; faster settings can increase noise. Scores are not probabilities, and TPM does not guarantee future price direction or trading profitability.
---
TradingFlow: Trend Participation Monitor (TPM)
TradingFlow: Trend Participation Monitor (TPM) 結合價格行為與相對成交量,在獨立窗格中呈現近期的方向性壓力,以及壓力相對於近期平均值正在改善還是惡化。
TPM 著重觀察相對短期的量價壓力變化,實際涵蓋的時間範圍取決於圖表週期與回看設定。
TPM 將「壓力的正負」與「壓力的變化」分開呈現。正向壓力可能正在減弱,負向壓力也可能正在回升,讓交易者能區分近期量價表現的方向與強弱變化。
TPM 是壓力觀察工具,並非預測反轉的指標,也不是獨立的進出場系統。
價格與成交參與模型
模型以相同權重結合兩個部分:價格方向效率,以及相對成交量加權的單根 K 線壓力。
價格方向效率比較價格淨變化與連續收盤價的總移動距離。單根 K 線壓力則結合「以前一根 ATR 標準化的收盤價變化」與「收盤價在當根高低區間中的位置」。收盤價之間的變化包含跳空,因此向下跳空後收在當根高點附近,不一定會得到正向判定。
相對成交量比較當根成交量與先前數根 K 線的平均成交量,並限制其權重上限,避免單次爆量過度主導結果。模型經平滑後形成介於 -100 至 +100 的壓力分數。這是根據量價推算的數值,並非實際買賣方成交量或資金流入流出。
壓力線與參考線
藍線代表壓力。高於零表示模型中的正向壓力,低於零則表示負向壓力。灰線是壓力的較慢平均值,用來比較近期變化。
近期變化柱狀圖
柱狀圖等於壓力與參考線差值的一半。它衡量壓力相對近期平均值的位置,並非直接表示價格方向,也不只是與上一根 K 線相比的變化。
預設情況下,變化分數需要連續兩根達到 +5 或以上,或 -5 或以下,才會顯示已確認的方向顏色。
四色深淺設計
紫色代表已確認的改善;金色代表已確認的惡化。
灰色:尚未符合門檻或連續確認條件。
與前一根相比,較深色表示柱體朝遠離零軸的方向增長;較淺色表示柱體朝零軸縮短或持平。灰色不代表價格穩定;淺金色即使正在縮短,仍可能處於已確認的惡化狀態。
精簡資訊表與成交背景
精簡資訊表顯示目前採用的 K 線狀態、近期狀況,以及壓力與變化分數。詳細模式另顯示成交量、滾動相對成交量、股票估算成交額、可選的流通股換手率與資料狀態。
估算成交額以典型價格乘以成交量計算。換手率需手動輸入流通股數,單位為百萬股。這兩項僅提供股票的成交背景,不會額外加入壓力分數,避免重複計入成交量。固定的流通股數也未必能準確反映歷史股數變化。
收盤顯示與提醒
預設在當根 K 線形成期間,維持上一根已收盤 K 線的讀值。關閉此選項後,會顯示即時數值與顏色,兩者在當根收盤前都可能改變。提醒仍只在收盤時觸發,用來通知新確認的改善或惡化。這些提醒確認的是已發生的壓力變化,不代表價格趨勢剛剛開始。
成交量資料處理
當成交量缺失或無效、被評估的 K 線成交量為零,或有效成交活動不足時,指標會停止顯示壓力讀值並抑制提醒。壓力窗口內至少需要兩根具有有效正成交量權重的 K 線。資料缺失後,需累積完整的有效恢復窗口才會重新輸出。極小的正成交量仍可計算,但交投清淡時的讀值可能較嘈雜。
如何閱讀圖表
正向壓力搭配紫色柱,表示壓力為正,且已充分高於參考線。正向壓力搭配金色柱,表示壓力仍為正,但相對參考線已轉弱。
負向壓力搭配紫色柱,代表負向壓力正在回升,並非已確認的多頭反轉。柱狀圖接近零,代表壓力接近參考線,不代表價格必然處於橫盤。
彈性設定
可調整成交量基準期、壓力窗口、平滑期、參考期、ATR 週期、成交量權重上限、變化門檻、確認根數、柱狀圖顏色與資訊表顯示方式。
預設參數以股票日線作為起點,所有週期均按圖表的 K 線根數計算。日內相對成交量採用滾動比較,並非與過往相同時段比較,因此開盤、收盤與延長交易時段可能影響讀值。請使用標準 K 線,並留意商品所提供的成交量資料類型。
實際使用方式
TPM 的定位較適合作為評估進出場時機的短期輔助參考。由於反應較快,即使同一段走勢仍在延續,讀值也可能頻繁變化;持倉期間若每次變化都重新判斷是否續抱,容易反覆猶豫,打亂原有節奏。是否繼續持有,應更重視自己的交易週期、較大範圍的價格結構與原先的交易計畫,不宜僅因 TPM 的變化就決定進出場。
TPM 可協助觀察上漲、回調與整理期間的量價壓力變化,適合搭配價格結構與市場背景使用。平滑與確認機制會帶來延遲;較快的設定也可能增加雜訊。分數並非機率,TPM 不保證未來價格方向或交易獲利。
---
TradingFlow: Trend Participation Monitor (TPM)
TradingFlow: Trend Participation Monitor (TPM) は、値動きと相対出来高を組み合わせ、直近の上昇・下落圧力と、その圧力が最近の平均に対して改善しているか、悪化しているかを別のペインに表示するインジケーターです。
TPM は、価格と出来高から読み取れる比較的短期の圧力変化を捉えることを目的としています。対象となる時間の長さは、チャートの時間足と計算期間の設定によって変わります。
圧力の水準と、その変化を分けて見ることで、プラス圏にありながら勢いが弱まっている状態や、マイナス圏から持ち直している状態を把握できます。
TPM は圧力の変化を観察するためのツールです。反転を予測するものではなく、単独で売買のタイミングを判断するためのシステムでもありません。
価格と出来高を組み合わせたモデル
モデルは「値動きの方向効率」と「相対出来高で加重した各足の圧力」を、同じ比率で組み合わせています。
値動きの方向効率は、期間中の始点と終点の価格差を、終値が上下に動いた距離の合計と比較します。各足の圧力は、前の足の ATR で調整した終値の変化と、その足の高値・安値の範囲内での終値の位置から計算します。終値間の変化には窓開けも含まれるため、下に窓を開けた後にその足の高値付近で引けても、必ずしもプラスの評価にはなりません。
相対出来高は、各足の出来高をそれ以前の足の平均出来高と比較したものです。単発の出来高急増に左右されすぎないよう、計算に使う重みには上限を設けています。計算結果を平滑化し、-100 から +100 の圧力スコアとして表示します。このスコアは価格と出来高に基づく推定値であり、実際の買い・売り別出来高や資金流出入を測定したものではありません。
圧力ラインと基準ライン
青いラインは圧力スコアです。ゼロより上はモデル上の上昇圧力、ゼロより下は下落圧力を示します。グレーのラインは圧力をより長い期間で平均したもので、直近の変化を判断する基準になります。
直近の変化を示すヒストグラム
ヒストグラムは、圧力スコアと基準ラインの差を 2 で割った値です。価格そのものの方向や、単純な前の足との差ではなく、圧力が最近の平均に対してどの位置にあるかを示します。
初期設定では、変化スコアが 2 本連続で +5 以上、または -5 以下になると、条件成立を示す色が付きます。
色と濃淡の見方
紫は改善条件の成立、ゴールドは悪化条件の成立を示します。
グレーは、しきい値または連続確認の条件を満たしていない状態です。
前の足と比べてゼロから離れる方向に棒が伸びると濃い色、ゼロに向かって縮むか横ばいになると薄い色で表示します。グレーは価格が安定していることを意味しません。また、薄いゴールドの棒がゼロに向かって縮んでいても、悪化の判定条件は引き続き満たしている場合があります。
コンパクトな情報テーブル
通常表示では、表示対象の足の状態、直近の判定、圧力スコアと変化スコアを確認できます。詳細表示では、出来高、相対出来高、株式の推定売買代金、任意設定の浮動株回転率、データの状態も表示します。
推定売買代金は、代表価格(高値・安値・終値の平均)に出来高を掛けて計算します。浮動株回転率を表示するには、浮動株数を百万株単位で手入力してください。いずれも株式向けの参考情報であり、圧力スコアには加算しません。なお、固定の浮動株数では、過去の株数の変化を正確に反映できない場合があります。
確定足の表示とアラート
初期設定では、現在の足が形成されている間も、直前の確定足の値を表示します。この設定をオフにすると、リアルタイムの値と色を表示しますが、どちらも足が確定するまでは変わる可能性があります。アラートは設定にかかわらず足の確定時にのみ発生し、改善または悪化の条件が新たに成立したことを通知します。すでに生じた圧力変化を確認するものであり、価格トレンドの始まりを示すものではありません。
出来高データの扱い
出来高の欠損・無効値、判定対象の足の出来高がゼロの場合、または計算に使える取引データが不足している場合は、圧力の表示とアラートを停止します。圧力の計算期間内には、有効な正の出来高ウェイトを持つ足が少なくとも 2 本必要です。データ欠損後は、所定の期間にわたって有効なデータがそろうと表示を再開します。ごく少量の出来高でも計算できますが、取引が少ない銘柄では値が不安定になることがあります。
チャートの読み方
圧力がプラスで紫の棒が出ている場合は、圧力がプラス圏にあり、基準ラインを十分に上回っている状態です。圧力がプラスでもゴールドの棒が出ている場合は、プラス圏を維持しながらも、基準ラインに対して弱まっていることを示します。
圧力がマイナスで紫の棒が出ている場合は、マイナス圏からの持ち直しを示します。上昇トレンドへの転換が確定したわけではありません。ヒストグラムがゼロ付近にある場合は、圧力が基準ラインに近い状態であり、価格が横ばいであるとは限りません。
カスタマイズ
出来高の比較期間、圧力の計算期間、平滑化期間、基準ラインの期間、ATR の期間、出来高ウェイトの上限、変化のしきい値、確認本数、ヒストグラムの色、テーブルの表示を調整できます。
初期設定は株式の日足を想定しています。各期間は、チャート上の足の本数で数えます。日中足の相対出来高は直前の一定本数との比較であり、過去の同じ時間帯との比較ではありません。そのため、寄り付き・引け・時間外取引の影響を受けます。通常のローソク足で使用し、対象銘柄の出来高データが何を表しているかも確認してください。
活用方法
TPM は、エントリーや決済のタイミングを検討する際の、短期的な補助指標としての利用を想定しています。比較的反応が速く、一つの値動きが続いている途中でも表示が頻繁に変わることがあります。保有中にその変化を追いすぎると、判断がぶれたり、当初の売買計画を必要以上に見直したりする原因になりかねません。保有を続けるかどうかは、ご自身の取引時間軸、より大きな値動きの流れ、当初の売買計画を軸に判断し、TPM の変化だけを理由に売買しないことが大切です。
TPM は、上昇局面、押し目、もみ合いの中で、価格と出来高から読み取れる圧力がどう変化しているかを確認するのに役立ちます。高値・安値の位置関係や相場全体の状況と併せて判断してください。平滑化と確認処理には遅れが伴い、反応を速くする設定ではノイズが増えることがあります。スコアは確率ではなく、将来の値動きや取引の利益を保証するものではありません。
Индикатор

Relative Volume Candles & Narrow RangesRelative Volume Candles & Narrow Ranges brings volume and price contraction directly onto the chart. Five candle color-levels reveal volume dry-ups, normal participation, and expanding activity, while selective dots identify unusually narrow ranges. Together, they help swing traders assess consolidations, pullbacks, and price moves at a glance.
Low-volume and narrow-range clusters can be valuable areas to monitor because a tightening consolidation or quiet pullback may precede a sharp price expansion.
HOW IT WORKS
Relative Volume Candles & Narrow Ranges makes it easy to see how much trading activity supports each price candle. Rather than requiring a separate volume pane, the script translates relative volume into five bullish and bearish color shades.
These five levels distinguish volume dry-up from normal volume and explosive volume. On a dark chart, low-volume candles use the lightest shades. On a light chart, they use the darkest shades (see below). This makes quiet, low-participation candles easier to find.
Dots above candles identify narrow ranges. Their frequency adapts to the symbol’s recent range behavior, and users can make these dots more or less selective or disable them entirely.
The script was designed primarily for equities on the daily timeframe, with swing traders, position traders, and active investors in mind. You may find the same volume and range relationships helpful on other markets and timeframes.
FEATURES
The indicator combines relative-volume candles with selective narrow-range markers in one chart-level view.
Five relative-volume levels: Separates low volume from normal volume and more explosive volume.
Bullish and bearish palettes: Our defaults retain normal price colors while showing relative-volume levels in different shades, but you can choose more distinctive coloring as well.
Narrow-range dots: Highlights candles with particularly compressed price ranges.
Adjustable dot frequency: Controls how selective the narrow-range markers are, from Very High to Very Low, with an option to disable them.
Dark and Light color schemes: Reverses the shade order so volume dry-ups stand out against either background.
Customizable appearance: Includes editable candle colors, dot color, dot size, and brightness adjustments.
USE CASES
Finding quiet consolidations
Low-volume colors reveal where participation is drying up. Narrow-range dots help locate the tightest candles within the consolidation. Together, they can draw attention to areas where price and volume are becoming increasingly quiet. In our humble opinion, this is where our script shines.
Assessing pullbacks
A pullback occurring on declining relative volume can carry a different character from one accompanied by expanding participation. Narrow ranges can provide additional context when the pullback begins to stabilize or tighten.
Monitoring potential entries
Some of the strongest price expansions begin after a quiet cluster of low-volume, narrow-range candles. The indicator helps make those conditions visible, allowing traders to monitor them alongside price structure, support and resistance, and their own entry criteria.
Evaluating price moves
Expanded volume colors show when participation is increasing. This can help traders assess whether a breakout, rally, decline, or reversal attempt is attracting noticeably greater activity.
SETTINGS
Relative Volume
RVOL Lookback: Number of recent bars used to calculate average volume. The current bar is excluded.
Profound Dry-Up Below: Sets the upper boundary for the lowest relative-volume level. These candles use the lightest color on dark charts and the darkest color on light charts.
Constructive Dry-Up Below: Sets the upper boundary for the second-lowest relative-volume level. These candles use the second-lightest color on dark charts and the second-darkest color on light charts.
Expanded Volume Above: Sets the point above which volume is treated as expanded. These candles use the second-darkest color on dark charts and the second-lightest color on light charts.
Telling Volume Above: Sets the point above which volume is treated as telling. These candles use the darkest color on dark charts and the lightest color on light charts.
Volume between the Constructive Dry-Up and Expanded Volume thresholds is treated as normal.
Range Context
ADR Length: Number of recent bars used to calculate the average price range. The current bar is excluded.
Range Dot Frequency: Selects the narrowest ranges relative to the symbol’s recent history. Lower frequencies produce fewer, more exceptional dots.
Range Dot Size: Sets the size of the narrow-range dots to Tiny, Small, or Normal.
Range Dot Color: Sets the color of the narrow-range dots.
Main Color Settings
Color Scheme: Selects the palette order designed for either a Dark or Light chart background.
Dark Scheme Dimming (%): Makes the Dark scheme darker with positive values or lighter with negative values.
Light Scheme Dimming (%): Makes the Light scheme darker with positive values or lighter with negative values.
Relative Volume Colors (Light to Dark)
This section contains five editable bullish and bearish color pairs, ordered from lightest to darkest. The selected color scheme determines how these shades correspond to the five relative-volume levels. Индикатор

Volatility Regime Engine [TRADION]Volatility Regime Engine is a multi-layer market regime analysis framework designed to identify changes in volatility structure, expansion/compression cycles, directional pressure, and continuation quality.
Rather than treating volatility as a single measurement, the engine evaluates multiple dimensions of market behavior to determine whether price is transitioning into compression, expansion, continuation, exhaustion, or a potentially unstable regime.
The objective is not simply to detect high or low volatility, but to identify how volatility is evolving, whether directional participation supports the move, and whether the current regime has sufficient quality to persist.
CORE ARCHITECTURE
The engine combines several analytical components into a unified regime model:
Volatility Regime
Evaluates the current volatility environment and classifies market conditions according to contraction and expansion behavior.
Fast & Confirmed Scores
Two-stage scoring separates early regime detection from confirmed conditions.
The Fast Score reacts more quickly to developing volatility changes, while the Confirmed Score provides a more stable assessment of established conditions.
This architecture is designed to balance responsiveness with confirmation.
ATR Regime
Measures volatility behavior relative to the instrument's recent range structure, helping distinguish subdued conditions from elevated or extreme volatility environments.
Bandwidth Analysis
Tracks contraction and expansion in the underlying price distribution to identify volatility compression and developing expansion phases.
Relative Volume (RVOL)
Provides participation context by comparing current activity with its historical baseline.
Directional & Setup Bias
Evaluates whether the developing volatility structure favors bullish or bearish conditions.
Bull and Bear Setup Scores quantify the relative strength of each side, while Dominance summarizes the resulting directional imbalance.
Cycle Engine
The Cycle Bias and Cycle State components classify the current phase of the volatility cycle.
Possible conditions include developing ignition, expansion, continuation and exhaustion phases.
This allows the indicator to distinguish between a market that is merely volatile and one that may be entering a structured directional expansion.
Ignition Detection
Ignition logic searches for early evidence that volatility is beginning to transition from a dormant or compressed state into directional expansion.
Bull Ignition and Bear Ignition events are designed as regime-transition signals, not standalone trade entries.
Release Quality
When volatility begins to release, the engine evaluates the quality of that transition.
Release Quality, Quality Grade and Follow Through help determine whether an expansion is developing sufficient structural confirmation or losing momentum.
Macro Continuation
Continuation logic reduces repetitive signaling once a directional regime has already been established.
This allows the engine to distinguish between:
initial ignition,
confirmed release,
established continuation,
and potential exhaustion.
Higher-Timeframe Context
Higher-timeframe regime information is incorporated into the scoring architecture to determine whether the active regime is supported or opposed by broader volatility conditions.
The HTF Quality Modifier adjusts regime quality according to this alignment.
False Expansion Risk
Not every volatility expansion develops into a sustainable move.
The False Expansion Risk model evaluates contextual conditions that may indicate a weak or unstable expansion and classifies the risk accordingly.
This component is intended to provide an additional layer of caution when volatility increases without sufficient structural support.
VISUAL ENGINE
The lower oscillator provides a compact visualization of regime behavior.
Histogram structure represents changes in volatility state and regime intensity, while the accompanying momentum structure helps visualize directional pressure and developing transitions.
Background regime zones provide additional context for compression, expansion and directional phases.
Event markers highlight significant transitions such as:
BULL IGNITION
Potential bullish volatility ignition.
BEAR IGNITION
Potential bearish volatility ignition.
BULL RELEASE
Bullish expansion gaining confirmation.
BEAR RELEASE
Bearish expansion gaining confirmation.
EXHAUST
Potential exhaustion of an extended volatility phase.
Continuation states are intentionally filtered to reduce unnecessary signal repetition.
DASHBOARD
The integrated dashboard provides a real-time summary of the engine, including:
Regime
Fast Score
Confirmed Score
ATR Regime
Bandwidth State
RVOL
Direction
Setup Bias
Bull / Bear Setup
Dominance
Breakout Memory
Cycle Bias
Cycle State
Ignition Score
Macro Continuation
Release Quality
Quality Grade
Follow Through
HTF Regime
HTF Quality Modifier
Risk Adjustment
False Expansion Risk
Active Event
The dashboard is designed to provide a compact overview of the current volatility environment without requiring interpretation of every individual component.
HOW TO USE
Volatility Regime Engine is designed primarily as a market-context and regime-analysis tool.
It can be used to:
identify volatility compression before potential expansion,
detect early bullish or bearish ignition,
evaluate the quality of developing volatility releases,
distinguish expansion from established continuation,
identify potential exhaustion conditions,
compare directional setup strength,
evaluate higher-timeframe regime alignment,
and assess the risk of unstable or false expansion.
The indicator should not be interpreted as a mechanical buy/sell system. Signals represent changes in volatility structure and should be evaluated together with price action, market structure, trend context, support/resistance and appropriate risk management.
NON-REPAINTING DESIGN
The engine is designed around confirmed-bar calculations for signal generation. Historical signals are not intentionally repositioned after confirmation.
Higher-timeframe information is handled with confirmation-oriented logic to minimize look-ahead bias.
IMPORTANT
Volatility expansion does not necessarily imply bullish price movement. Expansion can occur in either direction.
The primary purpose of the engine is to determine when the volatility environment is changing, which side currently has structural dominance, and whether that transition has sufficient quality to develop into continuation.
Volatility Regime Engine is intended for technical analysis, research and educational purposes only. It does not constitute financial or investment advice. Индикатор

Trinity ATR LevelsTrinity ATR Levels
Is an open-source overlay that draws volatility levels from the previous period close and a period ATR, then adds a session-aware signal layer on top of those levels.
Credit
The level map is a derivative of Saty ATR Levels by satymahajan, published open-source on TradingView in 2022.
Original:
What this script keeps from Saty:
Previous period close as the anchor
Trigger at a user-set share of ATR (default 0.236)
38.2, 50, 61.8, 78.6, ±1 ATR, and the same extension stack
Day / Multiday / Swing / Position / Long-term period selector
Optional "Use Current Close" switch
8-21-34 ribbon used only to color the small range/ATR info table
What this script adds:
Three modes that change when a signal may fire, not the level math
Confirmed-close ENTER and EXIT through the trigger
Golden Gate open at 38.2 percent, with 61.8 percent as the gate target
Optional pullback markers: trigger pullback (T-PB) and 10-minute EMA8
Optional first-hour previous-close reclaim on 10-minute closes
Session clock for regular hours, premarket, or 24-hour markets
Entry budget, cooldown, debounce, gap-safe open, and an optional entry buffer that does not move the stop
A dashboard that states location, action, targets, stop, and why nothing is firing
Historical percentages that appear only on the exact sample they were measured on
Alerts for the mechanical events above
This is not a republish of Saty ATR Levels with new colors. The ruler is Saty's. The traffic lights, session clock, and scoped percentages are new. Source is open so both parts can be inspected.
What the levels are
Every line is the chosen period's reference close plus or minus a fraction of that period's ATR.
PDC — previous period close. The anchor. Nothing is measured from live price unless you turn "Use Current Close" on.
Call / Put trigger — default 23.6 percent of ATR either side of PDC. A confirmed close through this line is the entry gate. A confirmed close back through it is the exit.
38.2 percent — the Golden Gate opens.
50 percent — midpoint of the gate. The script treats fresh entries here as poor reward versus the stop at the trigger.
61.8 percent — the gate target. Scale out is the intended action.
78.6 percent and ±1 ATR — extension and full-range lines. Rare on a single day. The script does not treat them as add-on zones.
Leave "Use Current Close" OFF for trading. When it is ON, the forming close becomes the anchor, the levels drift with price, the trigger boxes cannot arm correctly, and none of the historical percentages apply. The only intended use is a last-minutes preview of the next period's map. Note the numbers, then switch it back OFF.
The three modes
The levels are the same in every mode. Mode only changes signal timing, re-entry policy, and whether percentages print.
MILKMAN — default. Day period forced. Regular-hours previous close and ATR. Signals only on a 3-minute chart during regular hours. One long and one short trigger entry per session. No entry buffer. Three-bar cooldown after an exit. Percentages print only when the chart is SPY or SPX, 3-minute, Day period, regular session. That is the only configuration those figures were compiled for. On any other symbol they hide.
UNIVERSAL — same structure on any market and timeframe. Signals on every bar. Unlimited re-entries with a longer cooldown. 1 percent ATR entry buffer. Percentages hidden everywhere. They were not measured outside SPY regular hours, so the script does not show SPY numbers on other markets.
CUSTOM — every control under "Signal Rules" applies. Use this only when you know which rule you are changing and why.
How a signal is taken
A wick does not count. The script waits for a confirmed bar close.
Long trigger entry: confirmed close above the call trigger, session and timeframe allowed, entry budget remaining, cooldown finished, and the close beyond any buffer you set.
Long exit: confirmed close back below the call trigger. The stop does not use the buffer.
Short side is the mirror.
After the Golden Gate is open, two extra entries can print: a pullback that tags the trigger again (T-PB), and a pullback to the 10-minute EMA8 inside the gate. The 10-minute EMA8 is requested from the 10-minute timeframe. It is not your chart's own 8 EMA. Above a 10-minute chart that line is only an approximation and those signals are suppressed. The Status row says so.
PDC reclaim is a first-hour 10-minute close back through the previous close after price started the session on the other side of it. It is not a trigger entry. It is a flip warning. It is also suppressed above 10 minutes.
Historical percentages
When they are visible they are historical frequencies from SPY, regular session 09:30-16:00 ET, 3-minute confirmed closes, sample window 2000-2025, compiled as "Milkman stats v2026-08-29". Examples the dashboard and labels may show:
Confirmed call close through the trigger: 73.6 percent reached 38.2 percent the same day. If price then closed back below the trigger, that fell to 59.5 percent.
Median time from a winning call trigger to 38.2 percent: 18 minutes. That is a median, not a deadline.
Trigger day to 38.2 percent: 78.5 percent bull, 79.0 percent bear.
38.2 percent to 61.8 percent: 62.7 percent bull, 65.5 percent bear.
Gate completion from a trigger day: 62.5 percent bull (n=3,421), 65.4 percent bear (n=3,196).
Full ±1 ATR on any day: 13.8 percent up, 16.1 percent down.
The 3-minute close study that produced the 73.6 / 59.5 pair was run on calls only. The script says so on the put trigger. Do not apply that pair to shorts.
These figures are not a win rate for your account, not a forecast, and not valid on QQQ, ES, BTC, a 5-minute chart, weekly levels, or extended-hours closes. If the dashboard says stats are hidden, believe it. The mechanics still run. The percentages do not.
Bilbo
Bilbo is a 1-hour Phase Oscillator state used as context, not as an entry trigger. It can only be read cleanly on a chart of 60 minutes or less. On higher timeframes the dashboard drops the intraday rows rather than inventing a value. Outer-zone states were associated with higher gate-completion frequencies in the same SPY sample. Treat that as sample context, not a filter you must wait for.
How to use it
For the published configuration: AMEX:SPY or SPCFD:SPX , 3-minute, regular hours, Mode = MILKMAN, Level Period left on Day, Use Current Close OFF.
Wait for a confirmed close through the trigger, or for GG / T-PB if you take those.
Stop is a confirmed close back through the same trigger.
Primary target is 61.8 percent. Scale at least half there. Trail remaining size. Do not add at 50 percent.
Read STATUS before you assume the script is broken. It will say if you are on the wrong timeframe, in cooldown, out of entries, or still short of the level.
On crypto, FX, futures, or a 4-hour chart, switch to UNIVERSAL or CUSTOM and ignore percentages.
Swing or Position level periods rebuild the same map from monthly or quarterly ATR. Use a 4-hour or daily chart for those. They are structure, not a 3-minute day-trade signal.
Alerts
Alert text is mechanical on purpose. TradingView freezes alertcondition text at compile time, so the message cannot know your mode or symbol. Percentages live on the dashboard, which does know the scope.
Limitations
Not financial advice. You are responsible for orders, risk, and venue rules.
Percentages describe one historical sample on one product. They can fail going forward.
10-minute EMA8, PDC reclaim, and 1-hour Bilbo are wrong or suppressed above their native timeframes.
Milkman stats require an exact ticker match. SPYG and SPYD do not inherit SPY figures.
A buffer, if set, moves only the entry. You can be in a trade and not yet stopped. The dashboard prints both prices when a buffer is on.
This script plots levels and discrete events. It does not place orders and it is not a strategy report.
Originality
Saty published the close ± ATR fib map and the period selector. This publication keeps that map, credits it, and adds a separate signal and session layer plus scoped historical labels. Code is open so the split is visible. If you only need the original lines, use Saty ATR Levels.
Published under the Mozilla Public License 2.0, subject to TradingView Script Publishing Rules, which take precedence for what may appear in the public library.
Full user guide: What this tool is
Trinity ATR Levels is a map of where the current period sits inside yesterday’s (or last week’s, month’s, quarter’s, year’s) volatility, plus a set of rules for when a bar is allowed to count as an entry or an exit.
It does not know your account size, your options expiry, or whether the next bar will continue. It answers four questions:
Where is price relative to the previous close and the ATR grid?
Has a confirmed close gone through the trigger?
Is the Golden Gate open?
If nothing is printing, why?
If you treat the percentages as a promise, you will misuse it. If you treat the lines as a fixed map and the markers as timestamps of confirmed events, it does what it was built to do.
### What you need on the chart
Add the script to a standard candlestick chart. Do not use Heikin Ashi, Renko, Kagi, line break, point and figure, or range bars if you care about the signals. Those charts change the close that the engine tests.
For the configuration the historical numbers belong to:
Open SPY or SPX.
Set the chart to 3 minutes.
Use regular trading hours for the Milkman mode. Turn extended hours on only if you also want premarket high and low drawn. Premarket lines stay blank without extended hours.
Leave Mode on MILKMAN.
Leave Level Period on Day. Milkman forces Day even if you change the input.
Leave Use Current Close OFF.
Leave Trigger at 0.236 unless you have a reason to move it. Every label reads that input, so the text will follow you if you change it.
If you are on QQQ, ES, NQ, a single name, FX, or crypto, switch Mode to UNIVERSAL before you look at the dashboard. The lines will still draw. The percentages should not.
### The map, from the middle outward
All distances are a fraction of the selected period’s ATR, measured from the previous period close (PDC).
PDC is the spine. On a Day period in Milkman mode it is yesterday’s regular-session close, not last night’s extended print and not the live price.
The call trigger sits 0.236 ATR above PDC. The put trigger sits 0.236 ATR below it. These two lines are the only entry gate and the only mechanical stop. Price touching them is not an event. A confirmed candle close through them is.
38.2 percent of ATR beyond PDC is where the Golden Gate opens. From there to 61.8 percent is the corridor the script treats as the trade. 61.8 percent is the gate target, not a suggestion to hold for a full ATR.
50 percent is halfway through that corridor. The script’s labels tell you not to start a new position there. Reward left to 61.8 is smaller than the risk back to the trigger. If you are already in, you hold and you still use the trigger as the stop.
78.6 percent is past the gate. The intended action on arrival is to trail, not to add.
±1 ATR is the full daily range relative to PDC. In the SPY sample a complete +1 ATR day happened on 13.8 percent of days and a complete −1 ATR day on 16.1 percent of days. Treat it as rare air, take remaining profits, and do not invent a second system beyond it.
Extensions past 1 ATR (1.236, 1.618, 2.0, and so on) are optional. Simple Mode hides them. They are orientation, not entries.
Previous period high and low, and premarket high and low, are extra structure. They are not part of the trigger rule. Premarket needs the 04:00–09:30 window (exchange time) and extended hours enabled.
The 10-minute EMA8 is pulled from the 10-minute timeframe so it is the same line on a 1-minute, 3-minute, or 10-minute chart. Confirmed mode steps every 10 minutes. That staircase is the real completed value. Live mode is smoother and it moves inside the bar. Signals test the confirmed value.
### Confirmed close is the whole mechanic
Saty’s original script drew the lines and stopped. Trinity adds a rule: the event is the close of a finished bar that is allowed to speak.
Allowed to speak means three things at once.
The chart timeframe is allowed. In Milkman that is 3 minutes only. On a 1-minute or 5-minute chart in Milkman, signals stay off and STATUS will say so.
The session is allowed. In Milkman that is regular hours only. Overnight bars do not arm the trigger.
The bar is confirmed. A live wick through the trigger during the forming bar is not an entry.
Exit is the same test in reverse: a confirmed close back through the trigger ends the setup. That invalidation is the filter. In the call-side 3-minute sample, a confirmed close above the trigger reached 38.2 percent the same day 73.6 percent of the time. If price then closed back below the trigger, that dropped to 59.5 percent. The numbers are history. The rule is: if the trigger gives the close back, you are out.
Wicks do not count on the way in and they do not count on the way out.
### The markers you will see
ENTER under or over a bar is a trigger entry. Long is a confirmed close above the call trigger. Short is a confirmed close below the put trigger.
EXIT is the invalidation close back through that same trigger.
GG is the Golden Gate opening: a confirmed close that first reaches 38.2 percent with the trade already allowed. That bar can also be painted gold if you leave gate coloring on.
T-PB is a pullback to the trigger after the gate is already open. The script ranks this as the best expected-value add or re-entry in the sample it displays. It is not a second daily trigger budget item in the same way as ENTER. It is a pullback event.
EMA8 is a pullback to the 10-minute EMA8 while price is inside the gate. Off by default because it prints often. It is suppressed above a 10-minute chart.
PDC is a first-hour reclaim or loss of the previous close on a 10-minute close. First hour means sixty minutes from the session start the mode is using. On SPY in Milkman that is 09:30–10:30 Eastern. It is a flip warning, not an order.
If markers are missing, read STATUS before you hunt through settings. The usual causes are: not 3 minutes, not regular hours, already used the one entry per direction, still inside the cooldown after an EXIT, or the chart is coarser than 10 minutes so EMA8 and PDC reclaim are disabled.
### How to take a long, step by step
Set Milkman on SPY 3-minute before the cash open if you can, so the levels are fixed and you can mark the call trigger and 38.2 / 61.8 before price gets there.
Do nothing in the trigger box except watch. The box is the space between PDC and the call trigger. Occupying it is common. It is not a signal.
When a 3-minute candle closes above the call trigger during regular hours, that is ENTER. In Milkman you get one of those per direction per session. After that, further longs come from T-PB, GG, or EMA8, not from another raw trigger fire.
Stop is already defined: a later 3-minute close back below the call trigger. You do not trail that stop until the gate target is reached. You do not move it to 50 percent. You do not use a wick.
If price reaches 38.2 percent, the gate is open. You may already be in from the trigger. You may enter there immediately. You may wait for a pullback to the trigger. The sample ranked those options in that order of expected value, with a fresh entry at 50 percent last and negative. Use that ranking as context, not as a second strategy.
At 61.8 percent, scale out at least half. Trail what is left. If price continues to 78.6 percent, trail again; do not add. If a full ATR prints, the script’s guidance is to finish the position. Mean reversion toward PDC is the next map, not a reason to press the same trade.
If you get stopped and the session still has time, Milkman will not give you another raw ENTER in that direction. That is intentional. A stop-out is the invalidation. Chasing a second trigger fire is how the 73.6 percent figure becomes the 59.5 percent figure.
Shorts are the mirror image. One extra warning: the 73.6 / 59.5 pair is call-side only. Bear-side labels use the bear frequencies (trigger to 38.2, gate completion, hold rates) and they say so. Do not quote the call study on a put.
### The three modes in practice
MILKMAN is the published study shape. Use it when you want the script to behave like the sample: SPY or SPX, cash session, 3-minute closes, daily ATR, one bite per side. If you take it to TSLA or to a 5-minute chart and wonder why stats vanished or signals died, that is the mode working.
UNIVERSAL is the same ruler on a market that has no cash open. Crypto and FX should live here. Signals run all day. Re-entries are unlimited. A 1 percent ATR buffer sits beyond the trigger so a messy close through the line does not count until price clears it. The stop stays on the trigger, so there is a band where you can be in and not yet stopped. The dashboard prints both prices when that buffer is on. Percentages stay off. Showing 73.6 percent on BTC would be invented evidence.
CUSTOM is a workshop. Every item under Signal Rules starts to matter: which timeframe may fire, which session, how many entries, how many bars of cooldown, how large a buffer, whether pullbacks fire once or on every linger, whether an overnight gap through the trigger still counts, and whether stats hide off the SPY 3-minute Day RTH scope. Change one thing at a time. If you do not know why you are changing it, stay on Milkman or Universal.
### Reading the dashboard
Full layout is the operator panel. Compact keeps the six lines you act on and shortens the wording. Off removes the panel and leaves levels and markers. Above a 1-hour chart the script drops the intraday rows instead of leaving them marked inactive, because the 3-minute entry rules and the 1-hour Bilbo state cannot be evaluated there.
The Mode row is a one-line reminder of which preset is live and whether stats are on.
Location is where price sits on the map: still inside the trigger box, through the trigger, inside the gate, past 61.8, or out at a full ATR.
Watch and Entry tell you what would have to happen next. If the next event is “need a confirmed close above 612.40,” that is the instruction. If the next event is “cooldown, 2 bars left,” that is also the instruction.
Targets and Stop reprint 61.8 and the trigger so you do not have to hunt labels during a fast bar.
Stall guidance is what to do when price is inside the gate and not moving. The default answer is hold until a trigger close against you or a 61.8 print.
Bilbo is the 1-hour Phase Oscillator context: high or low zone, rising or falling. In the same SPY sample, outer-zone states came with higher gate-completion frequencies, with Low+Falling the strongest bear-side figure in that set. You do not wait for Bilbo to take a trigger. You use it to decide how hard you lean on a runner.
Context and Timing cover session phase, first hour, and how the sample behaved in similar locations. Distance prints how far you are from the trigger, 38.2, and 61.8 in price and in percent of ATR, and how far an open trade has traveled through the gate.
STATUS is the line to trust when the chart looks dead. It will say signals are gated off, the timeframe is degraded, the daily budget is spent, cooldown is running, or you are simply waiting and how far the level still is. If STATUS and your eyes disagree, STATUS wins. The script is telling you which rule blocked the print.
The smaller range/ATR info table is Saty’s original idea: period name, how much of the ATR the current period has already used, and the two trigger prices. Green / orange / red on that range reading is utilization, not a signal. A day that has already spent most of its ATR has less room left to the full-range line. That does not forbid a trigger trade. It tells you the remaining runner is smaller.
### Bilbo, without mystique
Bilbo is not a person and it is not an extra level. It is a classification of the last completed 1-hour Phase Oscillator reading into high/low and rising/falling.
The script can only request that 1-hour series cleanly when your chart is 60 minutes or finer. On a 4-hour or daily chart the value you would get is not the completed hour the sample used, so the script stops showing the row.
Use it as a weight, not a gate. A call trigger with High+Rising or High+Falling in the sample completed the gate more often than the unfiltered baseline. A put trigger with Low+Falling was the strongest cell in that grid. None of those cells are 100 percent. None of them override a confirmed close back through the trigger.
### Historical numbers, and how not to lie to yourself
When stats are on, labels and the dashboard splice in frequencies from one compiled block: SPY, regular hours, 3-minute confirmed closes, 2000–2025, version tag Milkman stats v2026-08-29.
A few more figures you will see in Detailed labels, so they are not a surprise:
Trigger day reaching 38.2 percent: 78.5 percent bull, 79.0 percent bear.
38.2 to 61.8: 62.7 percent bull, 65.5 percent bear.
61.8 to 78.6: 68.9 percent bull, 74.7 percent bear.
78.6 to full ATR: 60.9 percent bull, 66.9 percent bear.
Gate completion from the trigger day: 62.5 percent bull, 65.4 percent bear.
Expected-value ranking in that sample put trigger pullback first, immediate 38.2 second, 10-minute EMA8 third, and a fresh 50 percent entry last and negative.
First-hour 10-minute PDC reclaim then reaching a trigger: 73.0 percent in that sample. Reclaim then reaching the gate: 49.0 percent.
Those are counts of past days that did a thing after another thing. They are not the probability of your next trade. They disappear the moment you leave SPY/SPX, leave 3 minutes, leave Day levels, or leave the regular-session close. SPYG is not SPY. The script checks the ticker exactly.
If you publish commentary, quote the scope in the same sentence as the number. “73.6 percent of confirmed SPY 3-minute call closes through the trigger reached 38.2 percent the same day in the 2000–2025 regular-hours sample” is honest. “This setup wins 74 percent of the time” is not.
### Settings that change behavior versus settings that only change paint
Mode, Level Period, ATR length, Trigger share, PDC/ATR session, and Use Current Close change the map or the clock.
Signal Rules change who is allowed to fire. They are ignored unless Mode is CUSTOM, except that Milkman and Universal already stamp their own values onto those same internal switches.
Display, colors, Simple Mode, dashboard position and size, legend, and label detail change what you see. Simple Mode keeps PDC, both triggers, 38.2, and 61.8, and hides 50, 78.6, extensions, prior high/low, and premarket. That is the right first view if the chart is unreadable.
Chart Markers turn ENTER, EXIT, GG, T-PB, EMA8, PDC, and gate-candle color on or off one at a time. Turning markers off does not turn the logic off. Alerts can still fire.
The colour-blind palette replaces gold/green pairs that collapse under deuteranopia. Use it if you cannot separate the default gate and trigger colors.
Runner Target under Trend & Runner is a discretionary extra line at 1.0, 1.236, 1.618, 2.0, 2.618, or 3.0 ATR. It is not the researched gate target. If both tags are on, 61.8 is the gate, the runner tag is optional greed. Do not confuse them.
Alert checkboxes only enable the long or short trigger alerts. The other alertconditions still exist in the script’s alert list when you create an alert on the chart.
### Alerts
Create the alert from this script on the chart, not from a second copy. Pick the condition by name.
ENTER Long / ENTER Short: confirmed close through the trigger.
EXIT Long / EXIT Short: confirmed close back through it.
Gate Open: first 38.2 event.
T-PB: pullback to the trigger with the gate already open.
EMA8 Pullback: 10-minute EMA8 tag inside the gate.
Gate Complete: confirmed close through 61.8.
PDC Reclaim: first-hour 10-minute close back through PDC.
The message body is mechanics only. It will not paste a SPY percentage onto a Bitcoin alert. That is deliberate. Read the dashboard for numbers.
### Timeframes other than 3 minutes
The levels will draw on any chart because they come from a higher-timeframe request. The signals will not always draw.
On 1 minute in Milkman, the engine refuses to fire because the study used 3-minute closes. Switch to Custom and “Any chart timeframe” only if you accept that you have left the sample.
On 5 or 15 minutes the Day levels still sit in the right place. A 15-minute close through the trigger is a different event from a 3-minute close through the trigger. Do not quote the 73.6 percent figure there.
On 1 hour and above, EMA8 pullback, PDC reclaim, and Bilbo are degraded or removed. STATUS and the swing layout of the dashboard are the honest view: location, targets, stop, distance.
On Swing or Position periods the same fibs are built from monthly or quarterly ATR. That is a multi-week map. Read it on a 4-hour or daily chart of a liquid name. Thin small-cap crypto can travel several of those ATRs in a session and then go dead. Daily period is safer there.
### The one setting that breaks the tool
Use Current Close ON rebuilds every line from the live close. Price is then sitting on the anchor by definition. The trigger box is “price between the close and a trigger,” which can never be true when the close is the live price. The gate cannot open. History on the chart becomes look-ahead because each past day is drawn from that day’s own close. The Milkman percentages assume a locked prior close. Turn this on only after the session, to preview tomorrow, then turn it off.
### What this script will not do
It will not size the position.
It will not know your option delta or your expiry.
It will not place the Webull or broker order.
It will not stay honest if you show it on Heikin Ashi and take the signals.
It will not carry SPY frequencies onto another product.
It will not keep a trade alive after a confirmed close back through the trigger just because 38.2 “usually” gets reached.
It will not replace Saty ATR Levels if all you wanted was the quiet fib grid. Use Saty’s script for that. Use Trinity when you want the grid and a clock that says when a close counts.
### A simple daily routine
Before 09:30 Eastern on SPY, load the 3-minute chart, Milkman, current close off. Write down PDC, call trigger, put trigger, upper 38.2, upper 61.8, lower 38.2, lower 61.8.
During the first hour, note whether price is stuck in a box, already through a trigger, or reclaiming PDC on a 10-minute close.
Take at most one raw trigger per side. Prefer a close, not a poke. Put the stop on the other side of that same line as a close, not as a tick.
If the gate opens, manage to 61.8. If it fails back through the trigger, flatten and stop trading that direction on the raw trigger for the rest of the session.
After 16:00, if you want tomorrow’s sketch, flip Use Current Close on for one minute, write the projected levels, flip it off.
If STATUS ever says you are out of scope, you are. Change product or mode on purpose, not by accident.
That is the whole tool: Saty’s ruler, a confirmed-close clock, a gate from 38.2 to 61.8, and a dashboard that tells you when the clock is not allowed to tick. Индикатор

Индикатор

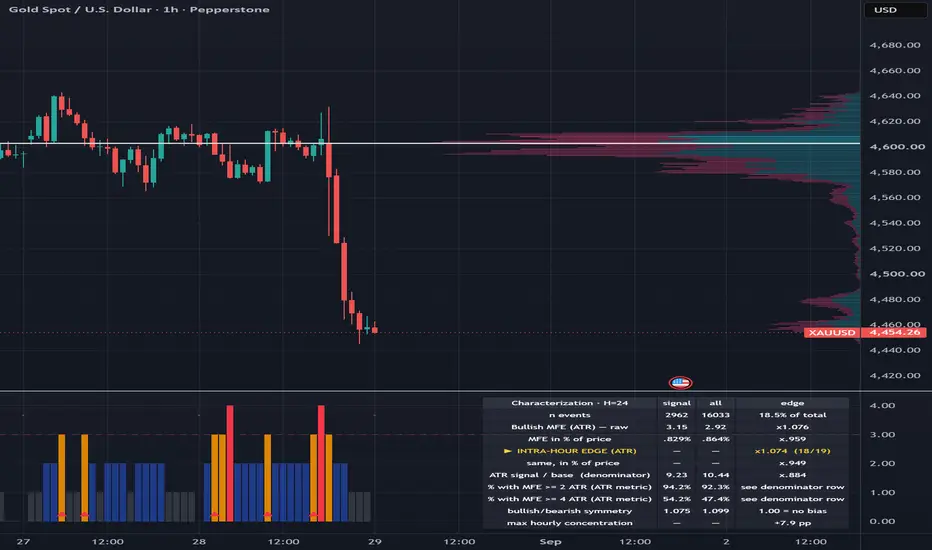
Volatility Expansion Score (0-4) v2.2 [TotoMazter]Volatility Expansion Score (0-4)
WHAT IT IS
This indicator detects one specific market state: a compressed market whose calm is starting to break. It scores every closed bar from 0 to 4, one point per condition:
Compressed regime — ATR% in the lower tercile of its own last 500 bars
Expansion starting — ATR% higher than on the previous bar
Narrow Bollinger Bands — band width in the lower tercile of its last 120 bars
Volume waking up — tick volume above its 100-bar mean (z-score > 0)
Score 3 (orange) is the signal threshold; score 4 (red) is a full trigger. Everything is self-normalized (rolling percentiles and z-scores, no absolute levels), so the indicator needs no recalibration across price regimes: in our research it behaved the same with gold at 1,800 and at 4,800.
WHAT IT DOES NOT DO — READ THIS FIRST
It does NOT predict direction. In the research program behind this script, the directional question was tested three separate ways on 14 years of XAUUSD minute data — 132 technical variables, a dedicated 40-feature study (intraday synthetic dollar index, gold/silver lead-lag, compression context, M1 microstructure, path features), and real aggressor order flow from COMEX gold futures — and all three came back null. A 4/4 score says "an impulse is more likely than usual", never which way. Any use of this tool as a bullish/bearish signal is outside what was validated.
It also does not promise big moves in dollar terms. The signal fires when ATR is compressed (about 0.83x its normal level), and the subsequent move measured in % of price is slightly SMALLER than average (about 0.97x). What increases is the move relative to current volatility. If you size stops and targets in ATR units (R multiples), the historical edge is real; if you think in dollars, there is none.
MEASURED RESULTS (all historical, XAUUSD 1h, 2013-2026, ~79,000 bars)
Out-of-sample validation on a pre-registered 2023-2026 holdout, opened once: bars with score >= 3 were followed by a 2-ATR impulse 1.95x more often than the base rate (95% CI 1.76-2.03). Score = 4: 2.73x (CI 2.09-2.94).
Honest base rates: with a ~5% base impulse rate, 2.7x lift means roughly 13-14% of full triggers are followed by an impulse. Most signals are NOT followed by a large move. Position sizing must assume this.
The follow-through advantage, measured in ATR units and controlled for time of day, is about x1.106, favorable in all 21 measurable hourly buckets and in 13 of 14 years. Without the time-of-day control the raw number is x1.139 — the control matters, and the built-in table applies it for you.
Where signals cluster on gold: the New York morning (13:00-15:00 UTC) and the London open (08:00-09:00 UTC). The most volatile hour of gold's day in this dataset is 14:00 UTC (about 1.8x the daily average hourly range).
STOCKS (NVDA, AMD, TSLA — high-volume, high-volatility test set)
The signal transfers, but with roughly half the strength: x1.04-1.08 in ATR units after the same time-of-day control (below 1 in dollar terms). Three structural rules came out of that validation and are enforced by the script's guards:
Do not use 5-minute charts: intraday volume is U-shaped and the signal degenerates into a closing-auction detector (a fake x1.68 "edge" came entirely from the last 30 minutes of the session).
Do not use 1-hour charts on RTH equities: the session's partial bar has a smaller range by construction and concentrates signals. The script excludes partial bars automatically (marked with a dot).
Use 15m or 30m, and keep the characterization horizon inside the session (H <= 12 on 15m, H <= 11 on 30m). Windows containing long closures (overnight gaps, weekends) are excluded by the gap guard.
Earnings are not the driver: excluding extreme-gap days does not change the result.
THE BUILT-IN CHARACTERIZATION TABLE
The table answers, for THE SYMBOL AND TIMEFRAME ON YOUR CHART, whether the signal has historically preceded larger moves, using three measures: raw MFE in ATR (inflated by the denominator and by time of day — reference only), MFE in % of price (immune to the denominator), and the intra-hour advantage (computed within each hour of day, then aggregated — the one that decides, highlighted in yellow). It also reports the ATR-at-signal ratio (~0.8 expected) and the maximum hourly concentration of signals (if it exceeds ~8 pp, part of what you see is the clock, not the market). If it says "short sample", the guards are refusing to output a number that cannot be measured cleanly on your chart — that is a feature.
WHY IT IS ORIGINAL
Rolling percentiles converted to the exact convention of pandas rolling rank, so the script reproduces the research module it was ported from (practical parity check: on XAUUSD 1h, score >= 3 should fire on roughly 17% of bars, score = 4 on roughly 3.7%).
Wilder ATR (RMA), population standard deviations, closed-bar evaluation with alerts on bar close, and an entry reference at the next bar's open — no repainting of the validated signal.
Session guards: partial-bar exclusion (any intraday bar shorter than its timeframe) and a data-measured gap guard (characterization windows may not contain a closure longer than 3x the timeframe), so equity overnight gaps and weekends do not contaminate the statistics while gold's 1-hour daily break does not block them.
A self-auditing characterization table with denominator-aware and time-of-day-controlled measures. It will happily tell you the signal does NOT work on your chart.
SETTINGS
Signal windows (14 / 500 / 120 / 100) and tercile cuts are the canonical values of the validated module; changing them invalidates every reference number above. "Confirm on bar close" keeps the indicator inside its validated definition. The alert message includes the score breakdown and states that the entry reference is the next bar's open. The characterization table can be displayed in English or Spanish via the "Table language" setting.
LIMITATIONS
All figures are historical measurements from the research program described above; past behavior does not guarantee future behavior. The stock characterization is in-sample (no reserved validation window). This is a statistical tool for regime awareness — when to pay attention — not a trading system: it provides no direction, no entries, and no risk management. Индикатор

Volatility-Scaled Range Level with Term Structure FilterWHAT IT DOES
This indicator plots a single volatility-scaled price level and evaluates three independent market-condition filters against it. The level sits one Average True Range below the prior period's close, so it widens automatically when realized volatility expands and tightens when volatility contracts. A summary table reports the level, its distance from current price as a percentage, and the state of each filter.
It is a reference and condition-monitoring tool. It does not generate buy or sell orders, does not connect to a broker, and takes no position on whether any particular trade should be placed.
HOW IT WORKS
The level is computed on a higher timeframe than the chart:
level = close of higher timeframe − ATR(14) of higher timeframe
ATR here is Wilder's RMA of True Range, which is what ta.atr() returns. Both components are pulled with request.security(..., lookahead = barmerge.lookahead_off) and referenced at index , so the value is drawn from the last completed higher timeframe bar and does not repaint. Setting the timeframe input to W produces a weekly-anchored level; D produces a daily-anchored one.
The level is then floored to a user-defined increment (default 5). This is optional rounding for users who want the level snapped to a round number rather than an arbitrary decimal.
Three filters are evaluated independently:
Term structure. The ratio of a short-dated volatility index to a longer-dated one (default CBOE:VIX over CBOE:VIX3M). A ratio below the threshold indicates contango, the normal state. A ratio above it indicates backwardation, which historically coincides with volatility clustering and trending decline. Both symbols are user inputs and can be swapped for other instruments.
Absolute volatility floor. A minimum level on the short-dated volatility index. Below this, the distance implied by ATR is small in absolute terms.
Optional trend filter. Price above its 21-period EMA.
The table reads GATES PASS only when all enabled filters are satisfied. An alert() call fires on the first bar of each new higher-timeframe period, with the level, the distance, and the filter states embedded in the message text.
HOW TO USE IT
Add to a daily chart. Set the ATR timeframe input to match the horizon you care about: W for a weekly-anchored level, D for a daily one. Confirm your data plan resolves both volatility symbols; substitute alternatives in the Symbols group if not.
The panel position is adjustable through the "Panel offset right of centre (%)" input, from 0 for centred through 45 for the right edge.
For notifications: right-click the chart, Add alert, select this indicator as the condition, choose "Any alert() function call", and set the frequency to Once Per Bar so it fires at the start of a new period rather than at its close.
The "Anchor on forming period" input switches the level to use the in-progress higher-timeframe bar rather than the last completed one. This produces a value that updates continuously through the period. It is intended as a preview of where the next period's level is forming, not as a signal, and it will change intrabar.
ORIGINALITY
Prior-close-minus-ATR levels are a well-established concept and several published indicators plot them, most notably Saty Mahajan's ATR Levels, which plots a full Fibonacci ladder of them across six timeframe modes. This script is not a republication of that work and does not reuse its code. It differs in scope and purpose:
It plots one level rather than a ladder, to keep the chart readable when the level is the only thing being monitored.
It adds volatility term structure and absolute volatility as explicit gating conditions, which existing ATR level indicators do not evaluate.
It rounds the level to a user-defined increment.
It emits a dynamic alert message containing the computed values, so the notification is self-contained and requires no chart lookup.
The arithmetic that produces the level is standard and deliberately matches the conventional definition so that values are comparable with other implementations.
LIMITATIONS AND SHORTCOMINGS
The level is descriptive, not predictive. It describes a distance in volatility units. Price reaching or not reaching it carries no guarantee of any kind.
The term structure filter depends on external symbols. If your data plan does not provide them, the filter cannot be evaluated and the table will not populate correctly. Verify both symbols resolve before relying on it.
Volatility index data is daily. The filter therefore updates on a slower cadence than the chart and can be stale relative to fast intraday moves.
The absolute volatility floor is a coarse proxy. It says nothing about the actual pricing of any instrument.
On index CFD feeds, the underlying value can differ slightly from the cash index. Where the level is near a rounding boundary, the rounded output may differ between feeds.
The forming-period preview mode updates continuously and is not a fixed reference.
No backtest or performance statistics are presented, because this is an indicator and not a strategy. Nothing here has been tested as a system.
CREDITS
The prior-close-minus-ATR level concept is widely used. Saty Mahajan's open-source ATR Levels indicator is the best-known implementation on TradingView and is worth reviewing for a fuller treatment of the concept across multiple timeframe modes and Fibonacci ratios.
DISCLAIMER
This script is provided for educational and analytical purposes. It is not financial, investment, or trading advice, and it is not a recommendation to buy or sell anything. Volatility-based levels describe historical range behaviour and carry no predictive guarantee. Any use of this tool is at your own risk.# TradingView publication description Индикатор

Volatility Regime Range Map [AFD]Two stretches of the same chart can look alike and be nothing alike — one the quietest tape in months, the other the widest swings all year.
Volatility Regime Range Map tells them apart on sight: it sorts every bar into one of four volatility regimes — QUIET, NORMAL, ELEVATED, EXTREME — and draws each unbroken stretch as a colored box on price. The calm and the turbulent history of your chart read at a glance instead of bar by bar.
What it does
At a glance it names which of four volatility regimes the current stretch belongs to, and how it compares with the chart's own recent history.
Regime episodes as boxes. Each unbroken stretch of one regime is a box spanning the bars it covered and the price range it reached. The current box glows and extends while the regime holds; recent finished episodes stay as faint boxes behind it — a map of which stretches were quiet and which were turbulent.
A regime ranked over calendar time. Each bar's volatility is ranked as a percentile against a rolling calendar window (default 6 months), so a regime means the same span of history on a 5-minute chart or a daily one — whether the tape is calmer, wider, or about the same as this symbol usually runs.
Higher-timeframe frames. The same engine on one or two higher timeframes, drawn as outline frames — HTF 1 dashed, HTF 2 dotted (default 1 month and 1 week) — each labelled with its timeframe and regime, so the broader context is on the same screen without switching charts.
Optional dashboard. Off by default. When on, it shows the current regime, the episode's age and price range, where those rank among finished episodes, and the sample behind the ranking.
A standing note in the Data Window — "Volatility-regime episodes · describes chart history · not a forecast" — that is always on.
Every one of those is a measurement of chart history. It reports what volatility has been; it does not tell you what price will do next or how long a regime will last.
How it works
Parkinson
Garman-Klass
Estimator. Parkinson (default), Close-to-close, Garman-Klass, or ATR — the one you pick measures every regime on the chart.
Percentile to tier, with hysteresis. The reading maps to a tier at the 25th, 75th and 85th percentiles, through a small hysteresis band so the regime does not flip on one borderline bar. QUIET below 25, NORMAL 25–75, ELEVATED 75–85, EXTREME 85 and above.
An optional second route into EXTREME. Flags EXTREME when the short window reaches a set multiple of the long one — also while the window is still gathering enough history to rank.
Confirmed bars only, no redraw. Regimes update on confirmed bars. A new box opens at the bar where the regime changes; once a box or a frame is drawn, later bars do not move it or recolour it.
The higher-timeframe frames use request.security to read each timeframe's most recently confirmed regime.
How to use it
Add it to any chart and timeframe. The defaults are the intended reading: Parkinson, Fast (5/30), a 6-month lookback, frames on (1M dashed + 1W dotted), dashboard off. Remove and re-add once so it draws in front of the candles.
Read the boxes first — the colour names the regime you are in, and the height is the price range that stretch covered.
Use the dashed and dotted frames to see the weekly and monthly regime on the chart you are trading.
Turn on the dashboard for the current episode's age and range in numbers, and where they rank.
Change the comparison lookback to widen or narrow the window a regime is judged against.
What it deliberately does not do
Every number is measured from this chart's own price history — nothing is implied, expected, or projected forward.
No alerts, no signals, no entries or exits.
No statement about what price will do next, or how long a regime will last.
Counts and percentiles stay descriptions of this chart's history — never converted into odds.
The regime names are labels for measured tiers, not ratings, scores, or predictions.
Why it is original
Most volatility tools hand you a line (ATR, standard deviation) or a band. This one segments the history into regime episodes and draws each as a box you can take in at a glance, ranks the regime over a rolling calendar window so it means the same across timeframes, and can stack one or two higher timeframes as nested frames on the chart. The classifier is the engine from the author's Volatility Regime Classifier, re-expressed here as an on-price map ranked over calendar time.
Open source under the Mozilla Public License 2.0. Native Pine v6; the optional higher-timeframe frames read the regime on higher timeframes via request.security, and nothing uses external data. Индикатор

Индикатор

Momentum Rotor | Basket Breakout & Leadership RotationWhat it does
Momentum Rotor ranks a basket of correlated symbols (default: AAPL, MSFT, NVDA, GOOGL, AMZN, META, TSLA, AVGO — fully user-editable) by N-bar rate-of-change momentum, recalculated every bar via request.security(). It only opens a long position on the chart's own symbol when that symbol is simultaneously the strongest performer in the basket (rank #1 by momentum) and breaking its own N-bar price high. If the held symbol later loses the #1 rank to another basket member, the strategy closes the position — it "rotates out" of a fading leader rather than holding through a reversal.
Core features
Live leaderboard table — ranks the full basket by momentum every bar, with gradient-colored scores and trend glyphs (↑/↓) so you can see who's strengthening or fading at a glance
Regime/leadership dashboard — shows your symbol's current rank, how many bars the leader has held the top spot, and basket-wide breadth (% of symbols with positive momentum) as a quick risk-on/risk-off gauge
Risk-based position sizing — position size is calculated from a fixed % of equity risked against an ATR-based stop distance, not a fixed share count
ATR stop + R-multiple take-profit — stop distance and profit target both scale with volatility instead of using static price offsets
Optional rotation-confirmation filter — require the leader to lose #1 rank for N consecutive bars before exiting, to reduce whipsaw from brief rank flickers
Optional regime filter — require price above a long SMA before taking new entries, to avoid trading breakouts in a broader downtrend
Realistic backtest defaults — includes commission, slippage, and margin settings out of the box rather than assuming frictionless, infinite-leverage fills
How the strategy works
Each bar, the script pulls the N-bar ROC (rate of change) for every symbol in the basket and sorts them from strongest to weakest. Your chart's symbol only becomes eligible to trade when it holds rank #1 and closes above its own N-bar high — combining a relative-strength filter with an absolute breakout trigger, so entries require both "stronger than its peers" and "breaking out on its own chart" to align. Exits are twofold: an ATR stop/target pair from the entry, and a rotation exit that closes the trade the moment (or, with the confirmation filter on, N bars after) another basket member overtakes it in the momentum ranking.
What makes it distinct
Most retail breakout scripts evaluate a single symbol in isolation. Momentum Rotor brings relative-strength rotation — a concept used by institutional sector/factor rotation strategies — into a single-chart script by polling an entire basket with request.security() and gating trade eligibility on relative rank, not just absolute price action. The live leaderboard turns that ranking process into something visible and auditable on the chart itself, rather than a black-box filter.
Tips for use
Chart the strategy on one of the basket's own symbols (or add your target symbol to the basket inputs) — the "am I #1" check only works when your chart's ticker matches a basket entry
This instance only manages a position on its own chart's symbol; it does not automatically route orders to whichever symbol becomes the new leader. To rotate capital across the whole basket, run separate instances on each symbol
Momentum/breakout systems are inherently prone to false breakouts and whipsaws in choppy markets — the optional regime filter and rotation-confirmation delay are there to dampen that; test both on/off for your instrument and timeframe
Sector ETFs (lower dispersion, steadier trends) and mega-cap tech names (higher dispersion, sharper momentum swings) behave differently in this framework — adjust lenMom/lenBreak accordingly
Backtest results depend heavily on commission, slippage, and margin assumptions set in Properties — review and adjust these to match your actual broker before drawing conclusions
Limitations
This is an educational strategy template, not a production-ready system or financial advice. It has not been optimized or validated for any specific instrument, timeframe, or market regime. Past performance in this backtest does not indicate future results. Стратегия

TrendShift | Supertrend + ADX Regime-Adaptive StrategyOverview
Most Supertrend strategies use one fixed ATR multiplier for every market condition — which means it's either too tight (whipsawed in chop) or too wide (late to catch real trends). TrendShift fixes this by reading market regime in real time with ADX and automatically shifting the Supertrend multiplier to match: tight and responsive when the market is trending, wide and defensive (or disabled entirely) when it's choppy. The strategy essentially "changes gears" as conditions change, and shows you exactly which gear it's in.
Features
ADX-based regime detection — classifies the market as Trending, Choppy, or Neutral, with a built-in hysteresis zone so the regime doesn't flicker back and forth near the threshold.
Dynamic Supertrend multiplier — automatically tightens (fast entries) in trends and widens (fewer false signals) in chop, recalculated live every bar.
Signal gating — Supertrend flips during choppy conditions are suppressed by default; no trades fire on noise.
Risk-based position sizing — every trade risks a fixed % of equity, sized off the actual stop distance (the Supertrend line), so trade size adapts to current volatility automatically.
Trailing stop + optional R-multiple take profit — the Supertrend line itself trails the stop; an optional fixed reward-to-risk target can close the trade early.
Optional chop-flatten & max-bars-in-trade exits — extra safety nets for getting out of dead trades.
Clean, glowing trend line with gradient fill — colored green/red by direction, turns gray and flat in chop, with minimal arrow labels only on actual signal flips (no clutter).
Live dashboard — a small on-chart table showing current Regime, ADX value, Active Multiplier, and Position status, so you can literally watch the strategy shift gears.
How it works
ADX is calculated each bar and compared against two thresholds (default: 25 trending / 20 choppy).
Based on that regime, the strategy picks a tight multiplier (trending) or a wide one (choppy) for the Supertrend calculation — held steady in the neutral zone to avoid jitter.
Supertrend is recalculated using this adaptive multiplier, and a flip in trend direction becomes a trade signal only if the current regime allows new entries.
Position size is calculated from your risk % input and the distance from price to the Supertrend line, so every trade risks roughly the same account %, regardless of how wide the current band is.
The Supertrend line trails your stop; an optional R-multiple limit order banks profit early if enabled.
Tips
Start with the default ADX thresholds (20/25) and multipliers (1.75 tight / 4.5 wide) — they're tuned to be reasonable across timeframes, but always re-check on your specific instrument.
On lower timeframes or noisier symbols, consider raising the choppy threshold or widening the "wide" multiplier further — chop is more common intraday.
Leave "Disable new entries in choppy regime" ON for cleaner equity curves; turn it off if you want to see how the strategy performs without the filter (useful for comparison).
The dashboard's ADX/Multiplier readout is the fastest way to sanity-check whether the strategy is behaving as expected on a given chart — if it feels like it's not trading, check whether it's stuck in "CHOPPY."
Combine with your own higher-timeframe bias filter if you want extra confluence; the strategy doesn't currently check higher-timeframe trend.
This is a strategy script (has backtest results), not just a visual indicator — use the Strategy Tester tab to evaluate performance before live use.
Стратегия

TF: BB/KC and Potential Reversals (BBKC)TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKC combines Bollinger Bands (BB) and a Keltner Channel (KC) in one clean overlay, then uses band re-entry and momentum conditions to highlight potential bullish and bearish reversals. Its purpose is to make volatility structure, trend behaviour, compression, expansion, and possible turning points easier to read without covering the chart with separate indicators.
The diamond markers are hints that price may be reacting after an extended move or that momentum may be fading. They are not automatic trade instructions, and they do not mean a reversal is confirmed.
A Unified BB / KC View
Bollinger Bands and Keltner Channels describe volatility in different ways:
• Bollinger Bands: use standard deviation, so their width changes as price movement expands or contracts.
• Keltner Channel: uses ATR around an EMA to create a smoother channel for reading trends and pullbacks.
BBKC plots both structures with one visual theme rather than stacking two unrelated indicators. The more visible aqua boundaries are the KC, while the lighter boundaries are the BB. Subtle shading makes it easier to see how the two envelopes contract and expand around price, and the full KC area can also be lightly shaded if preferred.
This merged presentation is useful even without the reversal markers. The slope and direction of the channels, the side of the channel where price is holding, and the way price reacts at the boundaries can all provide trend context.
Why the Default KC Multiplier Is 1.6
By default, the KC uses a 20-period EMA and an ATR multiplier of 1.6. Many modern Keltner Channel implementations use a 2.0 ATR setting. BBKC uses 1.6 to keep the boundaries somewhat closer to price, making routine pullbacks, boundary tests, and re-entry behaviour easier to see. This is a visual design choice, not a claim that 1.6 is inherently more accurate.
The multiplier is adjustable. Different instruments and trading styles may benefit from a wider or narrower channel, so 1.6 should be understood as a useful default rather than a universal optimum.
How to Read the Potential Reversal Markers
• Green diamond: a bullish potential reversal. Price has reacted from a lower volatility boundary and passed the enabled filters.
• Red diamond: a bearish potential reversal. Price has reacted from an upper volatility boundary and passed the enabled filters.
By default, the script looks for the close to cross back inside a lower or upper KC or BB boundary. An optional rejection rule also checks whether the current or preceding candle touched or pierced a Bollinger Band before the current candle closed back inside.
The optional filters are designed to reduce ordinary boundary crossings:
• Volatility context: one of the two preceding closes must have been outside the corresponding boundary of a separate ATR-based Volatility Channel.
• RSI momentum: RSI must be below the bullish threshold or above the bearish threshold. Both levels are adjustable.
• Stoch RSI extreme: within a recent validity window, at least one completed bar must have both smoothed K and D in the 90/10 extreme zone. The window is adjustable and defaults to the two bars before the potential reversal; the current re-entry bar is excluded.
Potential reversal conditions are confirmed at bar close. The separate Volatility Channel can remain hidden while its values are still used by the filter; display it when you want to inspect those boundaries on the chart.
What a Marker Can and Cannot Mean
A potential reversal may become a major trend reversal, but it may also be only a small pullback, a pause within the existing trend, or a failed signal followed by continuation. The script detects a filtered move back from a volatility boundary; it cannot know in advance which outcome will follow.
The marker is therefore more useful as a prompt to investigate the chart than as a standalone entry command. A marker appearing against a strong trend should generally require more evidence than one appearing at a well-established structural level after an exhausted move.
Practical Reading Process
1. Read the slope and position of the BB / KC structure to understand the current trend and volatility regime.
2. Note whether the BB is compressing inside the KC or expanding beyond it.
3. When a diamond appears, check whether it is located near meaningful market structure rather than evaluating the marker in isolation.
4. Look for confirmation through price action, trend structure, support and resistance, or a failed breakout.
5. Add independent context such as volume profile, high- and low-volume areas, and the reaction around important support or resistance levels.
6. Define invalidation and risk before considering an entry.
Alerts
Alerts can be created for bullish potential reversals, bearish potential reversals, or either direction. They use the same final confirmed conditions and remain available when chart markers are hidden. For live use, “Once Per Bar Close” is recommended.
Important
BBKC is a chart-reading and opportunity-screening tool. Its markers are filtered potential reversals, not probabilities, guaranteed turning points, or complete trading systems. Settings behave differently across instruments and timeframes. Always combine the output with broader trend analysis, market structure, volume context, support and resistance, and appropriate risk management.
---
TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKC 把布林通道(Bollinger Bands,BB)與肯特納通道(Keltner Channel,KC)整合在同一張主圖,並根據價格重新進入通道及動能條件,標示潛在的多頭和空頭反轉。它讓波動、趨勢、收縮、擴張和可能的轉折位置更容易判讀,不用另外疊加兩個指標。
菱形標記只是一個提示:價格經過一段延伸後,可能開始回頭,或原有動能正在減弱。它不是自動交易指令,也不代表反轉已經確認。
整合的 BB / KC 顯示
BB 與 KC 以不同方式描述波動:
• 布林通道: 使用標準差,會隨價格波動的擴大和收窄而改變。
• 肯特納通道: 以 EMA 為中心,利用 ATR 建立較平滑的通道,適合觀察趨勢與回調。
BBKC 用統一的配色呈現兩者。較清晰的水藍色邊界是 KC,較淡的邊界是 BB。淡色填充可幫助觀察兩組通道如何隨價格收縮和擴張,也可選擇顯示整個 KC 範圍。
即使不看反轉標記,這組通道本身也能幫助判斷趨勢。可留意通道斜率、價格主要停留在哪一側,以及價格接近邊界時的反應。
為何 KC 預設倍數是 1.6
KC 預設使用 20 週期 EMA 和 1.6 倍 ATR。現代 KC 指標常見的 ATR 設定是 2.0;BBKC 改用 1.6,讓邊界稍微靠近價格,更容易看到一般回調、邊界測試及價格重新進入通道的情況。這是為了方便讀圖,並不代表 1.6 本身更準確。
倍數可以自行修改。不同市場、時間週期和交易方式可能適合不同寬度,因此 1.6 只是實用的起始設定,並非所有情況下的最佳值。
如何閱讀潛在反轉標記
• 綠色菱形: 多頭潛在反轉。價格從下方邊界回升,並通過已啟用的過濾條件。
• 紅色菱形: 空頭潛在反轉。價格從上方邊界回落,並通過已啟用的過濾條件。
預設會尋找收盤價重新進入 KC 或 BB 邊界的情況。也可加入額外條件:目前或前一根 K 線先觸及/突破 BB,然後目前 K 線收回通道內。
各項過濾器用於減少普通邊界穿越造成的雜訊:
• 波動背景: 前兩根 K 線中,至少一根的收盤價必須曾位於另一組 ATR 波動通道的相應邊界之外。
• RSI 動能: 多頭標記要求 RSI 偏低,空頭標記要求 RSI 偏高;門檻可自行調整。
• Stoch RSI 極端值: 在近期有效期內,至少一根已完成 K 線的平滑 K、D 必須同時進入 90/10 極端區域。有效期可以調整;預設檢查潛在反轉前的兩根 K 線,不包括目前重新進入通道的 K 線。
潛在反轉條件只會在 K 線收盤後確認。另一組 Volatility Channel 即使隱藏,其數值仍可用於過濾;如想直接查看這些邊界,可在設定中顯示它。
標記可能代表甚麼
潛在反轉可能最終發展成主要趨勢反轉,也可能只是一個小型回調、原有趨勢中的短暫停頓,甚至是錯誤提示,之後價格繼續沿原方向運行。這套判斷只能找出價格從波動邊界回頭的跡象,無法預先知道之後會出現哪一種結果。
標記的作用是提醒你多看一眼,而不是叫你立即進場。逆著強勁趨勢出現時,通常需要更多確認;若它出現在明確的支撐、阻力或區間邊緣,而且此前走勢已有明顯延伸,才更值得留意。
實用判讀流程
1. 先閱讀 BB / KC 的斜率及價格位置,判斷目前趨勢與波動狀態。
2. 觀察 BB 正在 KC 內部收縮,還是向 KC 外部擴張。
3. 菱形出現時,先看它是否接近支撐、阻力或區間邊緣,不要只看標記本身。
4. 利用價格行為、趨勢結構、支撐阻力或假突破尋找確認。
5. 配合成交量分布(Volume Profile)、高/低成交量區,以及重要支撐阻力附近的反應。
6. 考慮進場前,先定義失效位置及風險。
警報
如需追蹤,可分別在多頭潛在反轉、空頭潛在反轉,或兩者任一出現時建立警報。警報只會在收盤條件確認後觸發;隱藏圖表上的菱形標記不會影響警報。即時使用時,建議選擇「Once Per Bar Close」。
重要說明
BBKC 是圖表判讀及機會篩選工具。標記只表示經過條件過濾的潛在反轉,不代表任何勝率,也不是必然轉折或完整交易系統。不同市場和時間週期的表現可能不同。使用時仍要結合趨勢、市場結構、成交量、支撐阻力和風險管理。
---
TradingFlow: BB/KC and Potential Reversals (BBKC)
BBKCは、ボリンジャーバンド(BB)とケルトナーチャネル(KC)を1つの見やすいオーバーレイに統合し、バンドへの再進入とモメンタム条件から、強気・弱気の潜在的な反転を表示します。複数の指標を重ねてチャートを複雑にすることなく、ボラティリティ構造、トレンド、収縮、拡大、転換候補を読みやすくすることが目的です。
ひし形のマーカーは、伸びた値動きが反応し始めた、またはモメンタムが弱まりつつある可能性を知らせるヒントです。自動売買の指示ではなく、反転が確定したことも意味しません。
BBとKCを統合した表示
BBとKCは異なる方法でボラティリティを表します。
• ボリンジャーバンド: 標準偏差を使うため、価格のばらつきの変化に反応します。
• ケルトナーチャネル: EMAを中心にATRで幅を作る、より滑らかなチャネルです。トレンドや押し戻りの確認に使えます。
BBKCは両者を共通の配色で整理して表示します。より明瞭なアクア色の境界がKC、薄い境界がBBです。控えめな色付けにより、2つのチャネルが価格の周囲で収縮・拡大する様子を見やすくし、必要に応じてKC全体の範囲も薄く表示できます。
この統合表示は、反転マーカーを使わない場合にも有用です。チャネルの傾き、価格が維持されている側、境界での反応から、トレンドの背景を読み取れます。
KCのデフォルト倍率が1.6である理由
KCは、デフォルトで20期間EMAと1.6倍のATRを使用します。現代的なKCでは2.0倍のATRもよく使われますが、BBKCは境界を価格に少し近づけ、通常の押し戻り、境界テスト、チャネルへの再進入を見やすくするために1.6倍を採用しています。これは見やすさのための設計であり、1.6倍のほうが本質的に正確という意味ではありません。
倍率は調整可能です。銘柄、時間軸、取引スタイルによって適切な幅は異なるため、1.6は実用的な初期値であり、すべての市場に共通する最適値ではありません。
潜在リバーサル・マーカーの見方
• 緑のひし形: 強気の潜在リバーサル。価格が下側のボラティリティ境界から反応し、有効なフィルターを通過した状態です。
• 赤のひし形: 弱気の潜在リバーサル。価格が上側のボラティリティ境界から反応し、有効なフィルターを通過した状態です。
デフォルトでは、終値がKCまたはBBの境界内へ戻る動きを検出します。追加条件では、現在または直前の足がBBに到達・突破し、その後に現在の終値がバンド内へ戻った場合も候補にできます。
各フィルターは、通常の境界通過によるノイズを抑えるために使用します。
• ボラティリティ背景: 直前2本のうち少なくとも1本の終値が、別のATRベースのVolatility Channelの対応する境界より外側であることを要求します。
• RSIモメンタム: 強気ではRSIが下側しきい値未満、弱気では上側しきい値を超えていることを要求します。どちらもしきい値を調整できます。
• Stoch RSIの極端値: 直近の有効期間内で、少なくとも1本の確定足において平滑化されたKとDが同時に90/10の極端ゾーンへ入っていることを要求します。有効期間は調整でき、デフォルトでは潜在リバーサル前の2本を確認します。現在の再進入足は含めません。
潜在リバーサルの条件は足の確定時にのみ成立します。Volatility Channelは非表示でもフィルターに使われ、必要に応じてチャート上に境界を表示できます。
マーカーが意味する可能性
潜在的な反転は、大きなトレンド転換につながる場合もあれば、小さな押し戻り、既存トレンド内の一時停止、または誤ったシグナルとなってそのままトレンドが継続する場合もあります。検出しているのは、フィルターを通過したボラティリティ境界からの戻りです。その後の結果を事前に判断することはできません。
そのため、マーカーは単独のエントリー指示ではなく、チャートを詳しく確認するためのヒントとして使うのが適切です。強いトレンドに逆らうマーカーには、明確な構造水準で伸び切った後に出るマーカーよりも多くの確認が必要です。
実践的な読み方
1. BB / KCの傾きと価格位置から、現在のトレンドとボラティリティ状態を確認します。
2. BBがKCの内側で収縮しているか、外側へ拡大しているかを確認します。
3. ひし形が出たら、重要な市場構造の近くにあるかを確認し、マーカーだけで判断しないようにします。
4. プライスアクション、トレンド構造、サポートとレジスタンス、または失敗したブレイクから確認を探します。
5. ボリュームプロファイル、高・低出来高帯、重要なサポート/レジスタンスでの反応など、独立した情報を組み合わせます。
6. エントリーを検討する前に、無効化水準とリスクを定義します。
アラート
強気、弱気、またはいずれかの方向に潜在リバーサルが現れた場合のアラートを作成できます。どれも同じ足の確定条件で作動し、チャート上のマーカーを非表示にしても機能します。リアルタイムでは「Once Per Bar Close」の使用を推奨します。
重要
BBKCはチャート分析と候補抽出のためのツールです。マーカーはフィルターを通過した潜在的な反転を示すものであり、確率、保証された転換点、または完全な売買システムではありません。銘柄や時間軸によって挙動は異なります。より広いトレンド分析、市場構造、出来高、サポートとレジスタンス、適切なリスク管理と組み合わせて使用してください。
Индикатор

Hybrid Breakout | VCP-Inspired TrendTrend Squeeze Breakout
Trend Squeeze Breakout is a trend-following momentum strategy designed to identify stocks in strong established uptrends that are consolidating into relatively tight trading ranges before attempting a breakout.
The strategy combines a simplified Minervini-style trend template, volatility contraction, volume confirmation, and stop-entry breakout execution. It is designed primarily for swing trading and is intended to participate in strong upward price expansions while filtering out many breakouts occurring in weak or declining trends.
Strategy Explanation
The strategy follows a simple sequence:
Identify a strong uptrend
A long setup requires:
Price above the 50-period SMA
50 SMA above the 150 SMA
150 SMA above the 200 SMA
200 SMA rising
200 SMA continuing to rise over the selected lookback period
50 SMA not declining
This establishes that the stock is already in a structurally bullish environment before considering an entry.
Identify a volatility contraction
The strategy looks for periods where recent price movement has become unusually tight.
It evaluates both:
Recent high-low range
Recent closing-price range
The high-low range is also compared with its historical percentile over the selected lookback period. This allows the strategy to identify relatively quiet consolidation periods rather than relying on a fixed volatility threshold alone.
Confirm volume
When the volume filter is enabled, breakout volume must exceed the moving-average volume baseline by the selected multiplier.
The default requirement is:
Volume > 20-period average volume × 1.2
This is intended to provide additional confirmation that the breakout is supported by meaningful participation.
Enter on a breakout
When the trend, contraction, and volume conditions are satisfied, the strategy places a stop-entry order above the recent high.
The default breakout lookback is 3 bars, allowing the strategy to attempt to enter as price moves through the recent consolidation high rather than simply buying while the stock remains inside the range.
Manage the position
Positions use tiered profit-taking:
25% closed at +10%
50% closed at +20%
Remaining position closed at +30%
Default stop loss at -8%
This allows the strategy to realize some profits during the initial move while maintaining exposure to larger momentum extensions.
Features
Trend Filter — 50/150/200 SMA bullish alignment
Long-Term Trend Confirmation — Requires the 200 SMA to be rising
Volatility Squeeze Detection — Identifies unusually tight recent ranges
Range Percentile Filter — Compares current volatility with historical volatility
Close-Range Filter — Detects tight price consolidation
Volume Confirmation — Optional volume expansion requirement
Stop-Entry Breakout — Enters only when price breaks the recent high
Tiered Profit Taking — Three configurable profit targets
Percentage-Based Stop Loss — Adjustable downside protection
Date Filter — Allows users to restrict backtests to a specific period
Configurable Parameters — Trend, volatility, volume, breakout, and risk settings can all be adjusted
Tips for Use
Use on liquid stocks
The strategy is generally better suited to liquid stocks and ETFs with sufficient trading volume. Extremely illiquid securities can produce unrealistic backtest results because of spreads and execution differences.
Start with daily charts
The strategy is particularly suited to identifying multi-day or multi-week momentum breakouts. Daily charts are a good starting point when evaluating the strategy.
Avoid optimizing every parameter
The many adjustable parameters make it possible to overfit the strategy to a particular stock or historical period. Test parameter changes across multiple securities and different market environments rather than optimizing exclusively for one chart.
Treat the volume filter as confirmation, not a guarantee
High volume can strengthen a breakout signal, but it does not guarantee that the breakout will succeed.
Test across different market conditions
Trend-following breakout systems typically perform differently during strong bull markets, corrections, sideways markets, and high-volatility periods. Evaluate results across multiple market regimes before relying on the strategy.
Pay attention to execution
The strategy uses stop-entry orders above recent highs. In live trading, gaps, slippage, spreads, and intrabar price movement can cause actual execution prices to differ from backtested results.
Important Note
This strategy is inspired by trend-template and volatility-contraction concepts, but it is not a complete implementation of a textbook VCP. It uses a simplified statistical contraction model rather than explicitly identifying multiple successive contractions, contraction depths, and their associated volume characteristics.
Backtest results are hypothetical and do not guarantee future performance. Always consider commissions, slippage, liquidity, position sizing, and market conditions when evaluating a strategy.
Recommended starting configuration: Daily timeframe, liquid stocks, default trend filter, volume confirmation enabled, and the default tiered risk-management settings.
Стратегия

BIST30 to SP 500 ATR Momentum RiderBIST30 to S&P 500 — ATR Momentum Rider
BIST30 to S&P 500 — ATR Momentum Rider is a long-only daily strategy built to test a compact and auditable trend-following structure across index futures.
The name describes the research scope—from BIST30 to S&P 500 and other major index futures. It does not mean that the public parameters were optimized on BIST30. Parameter selection used Mini-DAX, E-mini S&P 500, E-mini Russell 2000, EURO STOXX 50, and Nikkei 225 Mini futures. Turkish index futures were kept outside parameter selection and used only as transferability stress tests.
Entry logic
The raw SET event occurs when HMA 8 > HMA 9 > HMA 20 becomes true for the first time. On that same daily close, the strategy calculates the three-day HMA20 slope in ATR units:
(HMA20 - HMA20 ) / (3 × ATR14)
The setup is accepted only when this value is at least -0.180 ATR per day. The threshold does not require a rising HMA20; it permits a mild decline and rejects setups where the slow trend is deteriorating more sharply. The filter is evaluated only on the first establishment of the HMA order. A rejected setup does not enter later inside the same uninterrupted regime.
An accepted setup creates a market order for the next available session open. The decision uses only values known at the daily close.
Exit logic
The strategy has one public exit stage:
K1-A: activation threshold. Maximum favorable excursion is divided by the ATR value known when the entry order is created. Default: 1.50 ATR.
K1-T: trail distance from the highest high observed during the campaign. Default: 5.75%.
K1-W: minimum waiting interval before a K1 close decision can act. Default: 4 sessions.
Once K1 is active, its absolute trail can only rise. An activation reached on the current bar becomes actionable from the next bar, so the activation bar cannot stop itself retroactively. A daily close at or below the active K1 line creates a market exit for the next available open. If a fresh accepted SET appears while a position is open, the campaign is refreshed at the next open.
Research process and held-out results
The K1 values were selected on January 2020–December 2023 data using equal-weight, percentage-normalized metrics across the five international contracts. Keeping the K1 engine fixed, the three-day slope threshold was then scanned from -0.400 to +0.050 ATR/day in 0.001 steps on the same development interval. The exact PF-priority plateau peak was -0.176; the operational value was rounded and locked at -0.180 to avoid publishing a fragile, over-precise threshold.
January 2024–July 2026 was not used to select the slope threshold. In this held-out interval:
Raw setups: 153
Accepted setups/trades: 102 (33.3% reduction)
Positive international instruments: 5 of 5
Median profit factor: 3.46 versus 1.94 without the slope filter
Median normalized net return: 39.3% versus 37.9% without the slope filter
Median return/max-drawdown ratio: 2.32 versus 2.16 without the slope filter
These figures use one adverse minimum tick per market fill and no commission, tax, funding, or roll cost. They are historical research results, not a forecast.
The held-out BIST stress test remained weak: the three Turkish contracts had a median profit factor of 0.77 with the slope filter. Therefore, this public version is better viewed as an international index-futures research strategy. It is not a replacement for a dedicated BIST30 live system.
Use the strategy on standard daily candles. Review each symbol's contract multiplier, session, continuous-contract construction, commissions, roll costs, and margin settings before interpreting Strategy Tester results. Changing the HMA, ATR, K1, or execution settings creates a different, unvalidated configuration.
This script is a research and educational tool, not investment advice. Past performance does not guarantee future results.
BIST30 to S&P 500 — ATR Momentum Rider
HMA 8/9/20 kuruluşunu, sabit ATR-normalize HMA20 eğim filtresini ve yalnız yukarı taşınan tek tepe trailini birleştiren açık kaynak, long yönlü günlük strateji.
BIST30 to S&P 500 — ATR Momentum Rider, farklı endeks vadelilerinde sade ve denetlenebilir bir trend takip yapısını sınamak amacıyla hazırlanmış, yalnız long çalışan günlük bir stratejidir.
İsim, araştırmanın BIST30'dan S&P 500'e ve diğer büyük endeks vadelilerine uzanan kapsamını anlatır. Açık kaynak parametrelerinin BIST30 üzerinde optimize edildiği anlamına gelmez. Parametre seçiminde Mini-DAX, E-mini S&P 500, E-mini Russell 2000, EURO STOXX 50 ve Nikkei 225 Mini vadeli kontratları kullanılmıştır. Türkiye endeks vadelileri parametre seçiminin dışında tutulmuş ve yalnız taşınabilirlik stres testi olarak değerlendirilmiştir.
Giriş mantığı
Ham SET olayı, HMA 8 > HMA 9 > HMA 20 sıralamasının ilk kez oluştuğu günlük kapanışta doğar. Strateji aynı kapanışta HMA20'nin üç günlük eğimini ATR cinsinden hesaplar:
(HMA20 - HMA20 ) / (3 × ATR14)
Kuruluş yalnız bu değer -0,180 ATR/gün veya daha yüksekse kabul edilir. Eşik HMA20'nin mutlaka yükselmesini istemez; hafif gerilemeye izin verir, yavaş trendin daha belirgin bozulduğu kuruluşları eler. Filtre yalnız HMA sıralamasının ilk kuruluşunda değerlendirilir. Reddedilen kuruluş, aynı kesintisiz rejimin sonraki günlerinde gecikmeli girişe dönüşmez.
Kabul edilen kuruluş, sonraki uygun seans açılışı için piyasa emri oluşturur. Karar yalnız günlük kapanışta bilinen değerlerle verilir.
Çıkış mantığı
Stratejide tek bir açık kaynak çıkış katmanı vardır:
K1-A: aktivasyon eşiği. Azami olumlu hareket, giriş emri oluşturulurken bilinen ATR değerine bölünür. Varsayılan: 1,50 ATR.
K1-T: kampanya boyunca görülen en yüksek fiyattan itibaren trail mesafesi. Varsayılan: %5,75.
K1-W: K1 kapanış kararının uygulanabilmesi için gereken asgari bekleme süresi. Varsayılan: 4 seans.
K1 aktif olduktan sonra mutlak trail seviyesi yalnız yukarı hareket eder. Bir barda ulaşılan aktivasyon eşiği sonraki bardan itibaren uygulanabilir; aktivasyon barı geriye dönük biçimde kendi kendisini durduramaz. Günlük kapanış aktif K1 çizgisinde veya altında gerçekleşirse sonraki uygun açılış için piyasa çıkışı oluşturulur. Pozisyon açıkken yeni ve kabul edilmiş bir SET doğarsa kampanya sonraki açılışta yenilenir.
Araştırma süreci ve ayrılmış dönem sonuçları
K1 değerleri Ocak 2020–Aralık 2023 döneminde beş yabancı kontrat üzerinde; endeksler eşit ağırlıklı ve fiyat ölçekleri yüzdeyle normalize edilerek seçildi. K1 motoru sabit tutulduktan sonra üç günlük eğim eşiği aynı geliştirme döneminde -0,400 ile +0,050 ATR/gün arasında 0,001 adımla tarandı. PF öncelikli platonun matematiksel tepe noktası -0,176 oldu; aşırı hassas bir değer yayımlamamak için operasyonel eşik -0,180 olarak yuvarlanıp sabitlendi.
Ocak 2024–Temmuz 2026 dönemi eğim eşiğinin seçiminde kullanılmadı. Bu ayrılmış dönemde:
Ham kuruluş: 153
Kabul edilen kuruluş/işlem: 102 (%33,3 azalış)
Pozitif yabancı endeks: 5/5
Medyan profit factor: eğim filtresi olmadan 1,94, filtreyle 3,46
Medyan normalize net getiri: filtresiz %37,9, filtreyle %39,3
Medyan getiri/azami düşüş oranı: filtresiz 2,16, filtreyle 2,32
Bu rakamlar her piyasa dolumunda bir minimum fiyat adımı ters slippage içerir; komisyon, vergi, fonlama ve vade geçiş maliyeti içermez. Tarihsel araştırma sonucudur, gelecek tahmini değildir.
BIST stres testi zayıf kalmıştır: eğim filtresiyle üç Türkiye kontratının medyan profit factor değeri 0,77 olmuştur. Bu nedenle açık kaynak sürümü yabancı endeks vadelileri için bir araştırma stratejisi olarak değerlendirmek daha doğrudur; özel BIST30 canlı motorunun yerine geçmez.
Stratejiyi standart günlük mumlarda kullanın. Strategy Tester sonucunu yorumlamadan önce sembolün kontrat çarpanını, seansını, sürekli-vade oluşturma yöntemini, komisyonunu, vade geçiş maliyetini ve teminat ayarlarını kontrol edin. HMA, ATR, K1 veya emir yürütme ayarlarını değiştirmek doğrulanmamış farklı bir model oluşturur.
Bu kod araştırma ve eğitim amaçlıdır; yatırım tavsiyesi değildir. Geçmiş performans gelecekteki sonuçları garanti etmez. Стратегия

Support & Resistance Zones [HexaTrades]
This indicator automatically finds the price levels where the market has turned around before the places where buyers stepped in (support) and where sellers took over (resistance) and draws them as clean rectangular zones on your chart.
Instead of a thin line, each level is drawn as a zone with real thickness, because support and resistance are never one exact price; they are areas where price reacts. The zones update live, extend forward as long as they are valid, and turn into light "ghost" boxes once price finally breaks through them, so you always keep the full picture of the market's history.
Bitcoin 4h: the indicator marking support and resistance zones
How it works
- Finds swing points. A swing high is a candle whose high is higher than the 10 candles on each side of it (the "Swing Length" setting). A swing low is the same idea upside down. These are the exact spots where the market turned.
- Builds a zone from the candle. The zone covers the candle's wick from the extreme tip to the candle body. That wick is where orders actually pushed price back, so it becomes the zone.
- Keeps zone size sensible. Very small wicks get padded to a minimum height, and no zone can grow taller than a maximum height (both measured in ATR, so they adapt automatically to each market's volatility).
- Merges duplicate levels. If a new swing forms at a level that already has a zone, the two are combined into one box instead of stacking clutter on your chart.
- Watches for breaks. When a candle closes beyond a zone, the zone is "broken." what happens next is up to you (see below).
What happens after a zone breaks?
The indicator provides three different zone-management options.
Keep As Past Zone: The broken zone stops extending and remains visible as a faded historical zone. This makes it easier to review how price behaved around previous levels.
Flip Support/Resistance: A broken resistance zone becomes support, while a broken support zone becomes resistance.
This is useful for studying the common market concept of role reversal, where old resistance may act as new support and old support may act as new resistance.
Delete Zone: The zone is completely removed after it breaks. This option is useful for traders who prefer a cleaner chart showing only active zones.
Optional volume filter:
Volume-Confirmed Zones Only can be enabled to filter out lower-volume swing points.
When enabled, the volume of the swing candle must be higher than: Average Volume × Volume Multiplier
For example, with a Volume Multiplier of 1.2, the swing candle’s volume must be greater than 120% of its average volume.
The volume filter is automatically ignored when volume data is unavailable. Volume quality can vary between markets, exchanges and brokers.
Indicator settings
- Swing Length: Controls how significant a swing must be. Lower values create more zones, while higher values create fewer but potentially more significant zones.
- Maximum Zones: Limits the number of active zones displayed. When the limit is exceeded, the oldest active zone is removed.
- ATR Length: Sets the calculation period used to measure volatility.
- Minimum Zone Height: Sets the minimum zone thickness as a multiple of ATR.
- Maximum Zone Height: Prevents zones from becoming excessively wide.
- Merge Overlapping Zones: Combines overlapping or nearby active zones.
- Merge Distance: Controls the ATR-based distance used when deciding whether zones should be merged.
- Maximum Past Zones: Limits how many broken historical zones remain on the chart.
- Past Zone Transparency: Controls how clearly broken zones are displayed.
Alerts
- Built-in alerts
- Zone Touched — price entered a support or resistance zone.
- Resistance Broken — a candle broke above a resistance zone.
- Support Broken — a candle broke a support zone below.
- Set them up from TradingView's alert dialog: Create Alert → Condition → S/R Zones.
How to use it in trading
🔶Bounce trades: when price falls into a support zone and prints a rejection candle, that's a long setup with a stop just below the zone.
A blue support zone represents an area where buyers previously entered the market.
When price returns to support:
- Wait for price to enter or test the zone.
- Look for evidence that buyers are responding.
- Consider an entry only after confirmation.
- Place the stop beyond the opposite side of the zone, with an appropriate buffer.
- Use the next resistance zone as a possible target.
Possible bullish confirmation includes:
- A candle rejecting the lower part of the zone.
- A long lower wick followed by a bullish close.
- A bullish engulfing candle.
- Price closing back above the support zone.
- Increasing volume during the reaction.
- A higher low forming near the zone.
A support touch by itself is not a long signal. Price can move directly through the zone, especially during a strong downtrend.
Example image below:
🔶Rejection from resistance
A pink resistance zone represents an area where sellers previously entered the market.
When price reaches resistance:
- Wait for price to test the zone.
- Look for signs of selling pressure.
- Consider an entry only after bearish confirmation.
- Place the stop beyond the upper edge of the zone, with a suitable buffer.
- Use the next support zone below as a possible target.
Possible bearish confirmation includes:
- A long upper wick inside the resistance zone.
- A bearish engulfing candle.
- Price entering the zone and closing back below it.
- A lower high forming near resistance.
- Increasing selling volume during the rejection.
A resistance touch alone is not a short signal. Strong bullish momentum can break through resistance without producing a meaningful reversal.
Example image:
🔶Trading a breakout
A breakout occurs when price moves beyond an active zone.
- A break above resistance may indicate increasing bullish strength.
- A break below support may indicate increasing bearish strength.
For more conservative confirmation, select Close under Break Confirmation. In this mode, a resistance zone breaks only after a candle closes above it, while a support zone breaks only after a candle closes below it.
The Wick option reacts as soon as price trades beyond the zone. It responds faster but is more sensitive to temporary spikes and false breakouts.
Before considering a breakout trade, traders may look for:
- A strong candle closing beyond the zone.
- A candle body that closes clearly outside the zone.
- Higher-than-average volume.
- Momentum in the breakout direction.
- Alignment with the broader market trend.
- A successful retest of the broken zone.
🔶Trading a role reversal
Support and resistance can sometimes exchange roles after a breakout.
-Broken resistance may later act as support.
- Broken support may later act as resistance.
Select Flip Support/Resistance under the When Broken setting to display this behaviour automatically.
For example, after price closes above a pink resistance zone, the indicator converts that area into a blue support zone. If price later returns to it, traders can watch for a bullish reaction.
Similarly, when price breaks below blue support, the indicator converts the zone into pink resistance. A later retest may provide an area to watch for bearish confirmation.
Role reversal is a commonly observed price-action concept, but it does not occur successfully after every breakout. Wait for confirmation instead of entering only because price has returned to a flipped zone.
🔶Using zones for targets and stops
Zones can also help organise trade management.
For a long setup:
- A stop may be placed below the support zone.
- The next resistance zone may be used as an initial target.
- A higher resistance zone may be considered as a secondary target if momentum remains strong.
For a short setup:
- A stop may be placed above the resistance zone.
- The next support zone may be used as an initial target.
- A lower support zone may be considered as a secondary target.
Avoid placing the stop exactly on the edge of a zone. Price may briefly move beyond the boundary before reacting. The appropriate buffer depends on the symbol, timeframe, volatility and the trader’s risk plan.
Always calculate the potential risk and reward before entering a trade. A visible zone does not automatically make a setup worth taking.
🔶 Using multiple timeframes
Higher-timeframe zones can provide broader market context, while lower timeframes can help refine entries.
A simple process is:
- Identify important support and resistance on a higher timeframe.
- Determine whether the broader structure is bullish, bearish or ranging.
- Move to the preferred trading timeframe.
- Wait for price to reach a relevant zone.
- Use candle structure, volume or momentum for confirmation.
Higher timeframes generally produce fewer but more widely watched zones. Lower timeframes produce more zones and may contain more market noise.
Support and Resistance Zones help traders identify and manage important price areas with less chart clutter. Its volatility-based sizing, zone merging, break confirmation, role reversal, and alerts make it suitable for different markets and timeframes. Use the zones as areas to watch—not automatic trade signals and always combine them with price confirmation, broader market structure and proper risk management.
We would love to hear your suggestions. If you have ideas for new features, indicators, analytics, or improvements, please share your feedback. Your input helps guide future updates and improve the indicator for all traders.
Wedge pattern detector indicator is for educational and analytical purposes only. It is not financial advice. Trading involves risk. Always use proper risk management and combine this indicator with your own analysis before taking any trade.
Индикатор

Стратегия