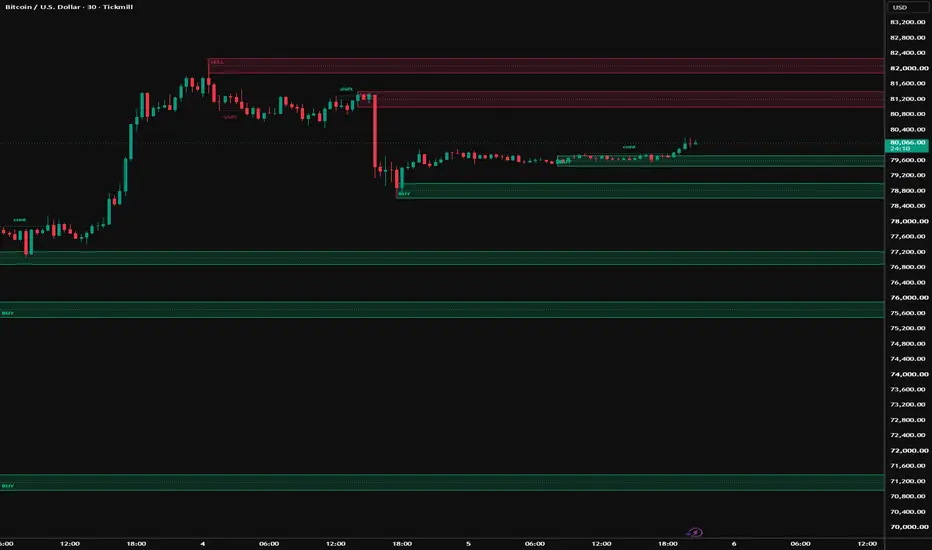
DAO GAM Reversal StructureBX Reversal Structure - Adaptive Top and Bottom is a market-structure indicator designed to identify potential horizontal reversal structures formed by two significant swing areas, referred to as A and B.
The indicator analyzes both top structures and bottom structures.
For a top structure, the script looks for an upward price phase followed by a meaningful rejection. It uses the high and close of the final bullish anchor candle to define a price zone around the swing high.
For a bottom structure, the logic is reversed. The script looks for a downward price phase followed by a meaningful recovery and uses the low and close of the final bearish anchor candle to define the swing-low zone.
When two valid zones, A and B, share an overlapping price area, the script attempts to determine a horizontal reference level called X.
The X level is selected so that it remains within the common price area of A and B while avoiding the interior of candle bodies located between the two structures. Wick interaction with X is permitted.
This approach is intended to distinguish meaningful horizontal market structures from simple price equality between two isolated swing points.
Main concepts
The indicator evaluates several structural conditions, including:
Minimum price movement into and away from each swing.
A minimum number of candles forming the directional phase before and after the swing.
Overlap between the price zones of A and B.
Candle-body interaction between A and B.
Separation between the two swing areas.
Distance and spacing between A and B.
Additional interactions with the X level after the structure is formed.
The indicator can detect:
Top structures: potential resistance or reversal structures.
Bottom structures: potential support or reversal structures.
Adaptive mode
The indicator includes an adaptive mode based on ATR (Average True Range).
Instead of relying exclusively on fixed price distances, ATR-based thresholds can automatically scale according to the volatility of the current symbol and timeframe.
This allows the indicator to be tested on different markets and timeframes, including forex, metals, cryptocurrencies, indices and other instruments available on TradingView.
A manual mode is also available for users who prefer fixed parameter values.
A, B and X
A represents the first qualified swing structure.
B represents a later qualified swing structure that shares a valid price area with A.
X is the horizontal reference level calculated from the overlapping zones of A and B.
Additional qualified interactions with the same level may be displayed as C, D, E or subsequent touches.
For top structures, X acts as a horizontal resistance reference.
For bottom structures, X acts as a horizontal support reference.
Line behavior
After a valid A-B structure is detected, the X line is extended to the right.
The visual line stops when a future candle body reaches the X level. Candle wicks alone do not necessarily stop the line.
The script may also generate a CHECK condition when price moves a specified distance beyond X within the configured monitoring period.
These signals indicate that the predefined structural condition has occurred; they are not automatic trading orders.
How to use
Users can apply the indicator directly to a chart and choose between:
AUTO (ATR): parameters adapt to current market volatility.
MANUAL: price-distance parameters are entered manually.
Because volatility and market structure differ significantly between instruments and timeframes, users should evaluate the parameters on the specific market they intend to analyze.
The indicator is intended primarily as a market-structure visualization and research tool. It can be combined with independent analysis of trend, volatility, liquidity, risk management and broader market context.
Original concept
The central idea of this indicator is that a horizontal resistance or support structure should not necessarily be defined by two identical highs or lows.
Instead, each swing is represented as a price zone between the close and the extreme of its anchor candle.
The indicator searches for the common price area between two qualifying zones and then determines a horizontal level that respects candle-body structure between them.
This zone-overlap and candle-body approach is the main structural concept used by the script.
Limitations
This indicator does not predict future market direction and does not guarantee that a detected support or resistance structure will produce a reversal.
Pivot-based structures require subsequent candles for confirmation, so signals are identified only after sufficient market data becomes available.
ATR adaptation improves portability between instruments and timeframes, but no single parameter configuration can provide identical behavior across all markets.
Low-liquidity instruments, gaps, unusually volatile market conditions and different data feeds may produce different results.
Historical structures should not be interpreted as evidence of future profitability.
Users should independently evaluate the indicator and apply appropriate risk management before making trading decisions. Индикатор

AMD Structure Map [AxeAlgo]AMD Structure Map
============================================
------------------------------------------------------------
WHAT THIS SCRIPT DOES
------------------------------------------------------------
AMD Structure Map automatically detects the Accumulation → Manipulation →
Distribution cycle on any chart, in real time, and draws each phase as its
own labeled zone directly on the candles — so the market's own three-act
structure is visible as it forms, instead of something you have to
eyeball yourself after the fact.
This is a pattern-recognition and structure-labeling tool. It identifies
and visualizes market structure per the AMD model. It does not predict
future price direction, it does not generate buy or sell signals, and
nothing it draws should be treated as a trading recommendation.
------------------------------------------------------------
BACKGROUND — WHAT "AMD" MEANS
------------------------------------------------------------
AMD is a way of reading price action as three sequential acts:
Accumulation is a period where price contracts into a range while orders
build on both sides of the market. Manipulation is a deliberate-looking
move beyond that range — far enough, and on enough volume, to run the
stop-losses and breakout orders sitting just outside it — that then fails
and closes back inside. Distribution is the real, sustained move that
follows, expanding in the opposite direction of that failed move.
The core idea is that the Manipulation phase exists to create liquidity:
a move beyond an obvious range draws in breakout traders and triggers
stops on the other side, providing the volume needed for the real
directional move that follows. Whether or not you subscribe to that
interpretation, the three-part sequence — range, false break, real break
— is a recurring, observable structure across most liquid markets and
timeframes, and this script exists to detect it mechanically and
consistently rather than by eye.
------------------------------------------------------------
HOW EACH PHASE IS DETECTED
------------------------------------------------------------
ACCUMULATION is flagged by genuine volatility contraction: a fast-length
ATR reading meaningfully below its own slow-length ATR baseline, averaged
over a short recent window rather than judged off a single bar, combined
with a minimum range width relative to current volatility. This rules out
both a lone quiet tick being mistaken for real compression and micro-noise
ranges being mistaken for a real base. Once contraction is confirmed, the
zone locks to the highest high and lowest low of the seed window and does
not move afterward.
MANIPULATION is a liquidity sweep: a wick that pierces beyond the
Accumulation range by a minimum distance, on volume above this specific
cycle's own frozen baseline (measured from its own seed window, not a
constantly-rolling average that would otherwise get distorted by the
sweep's own volume spike), that closes back inside the range within a
short window of bars. It does not have to reverse on the exact same bar
it pierced — it is given a handful of bars to do so, since real liquidity
sweeps do not always resolve instantly. The moment a sweep confirms, the
script labels the zone with an Expected Direction: opposite the side that
was swept, since that is what the AMD model itself defines Distribution to
be. If price later sweeps the OPPOSITE side too, before the range
resolves, that second sweep supersedes the first and the call flips —
capped at one such re-arm, since a range swept a third time no longer
looks like a clean setup.
DISTRIBUTION is a confirmed break — by distance and by volume, both judged
against that same frozen baseline — in the direction the Manipulation
phase called. Only at that point is the cycle logged as complete. A break
in the SAME direction as the earlier sweep is logged separately and
honestly as "Manipulation Failed," since the expected reversal did not
occur — the script does not force an incomplete or contradictory sequence
into the AMD narrative just because a Manipulation event happened
somewhere in the range's history.
------------------------------------------------------------
ON THE EXPECTED DIRECTION LABEL
------------------------------------------------------------
The "Expected Direction" shown on the Manipulation zone is a direct
restatement of the AMD model's own definition, not an independent
forecast: Distribution is, by definition, the move opposite the side that
got swept. It carries no probability estimate, is not back-tested, and is
not a trade instruction. It is confirmed or denied by the same real
price-and-volume break logic used everywhere else in the script — nothing
is assumed true until price actually does it.
------------------------------------------------------------
WHAT YOU SEE ON THE CHART
------------------------------------------------------------
Each phase is drawn as its own colored zone box with a label. The
Accumulation zone appears the moment contraction confirms. The
Manipulation zone appears the moment a sweep confirms, labeled with the
Expected Direction. The Distribution zone appears ONLY once the break
genuinely confirms in that expected direction — it is sized to the
Accumulation range's own width rather than to whatever the breakout bar's
own volatility happened to produce, then grows to track the real move for
a limited window before freezing in place, so it always reads as a
proportionate rectangle rather than an arbitrary spike or a box that
keeps expanding indefinitely.
A cycle that does not complete — a Manipulation that failed to lead to a
real Distribution break, or a breakout with no Manipulation ever detected
beforehand — is marked with a single small flag rather than a full zone
box, since nothing pattern-like actually happened there. A small signal
also marks the exact first candle a genuine Distribution phase begins on.
An optional session-window highlight is available for traders who want to
see which cycles are forming inside a specific trading session.
------------------------------------------------------------
DASHBOARD
------------------------------------------------------------
A compact corner table shows the current phase and its status, the
current Expected Direction, an optional higher-timeframe bias reading
(a simple moving-average slope check on a timeframe you choose, shown
purely as background context and never used to filter or alter
detection), and a running Follow-Through Rate.
The Follow-Through Rate is a historical tally, going back to when the
chart loaded, of how often this chart's own past Manipulation calls
actually went on to confirm into a real Distribution break versus failing
or the range simply expiring. It is not a win rate, not the result of a
back-tested strategy, and not a claim about the cycle currently forming.
The percentage is intentionally hidden until a minimum number of cycles
have been observed, so a small handful of outcomes is never presented as
a statistically meaningful rate.
------------------------------------------------------------
INPUTS
------------------------------------------------------------
A single Detection Sensitivity dial (Loose / Normal / Strict) governs
every underlying threshold at once — the seed window length, the required
depth of volatility contraction, the sweep depth and volume requirements,
and the breakout distance and volume requirements. Loose finds more
cycles at looser quality; Strict finds fewer, higher-conviction cycles
only.
Beyond that, every visual element can be toggled or recolored
independently: the zone boxes, the phase labels, the Expected Direction
label, the Distribution start signal, the Follow-Through Rate row, the
higher-timeframe bias row, the session highlight, and the on-chart legend.
A "completed cycles only" mode is also available, which hides everything
while a cycle is still forming and only draws it — retroactively, all at
once — if and when it actually completes the full sequence.
------------------------------------------------------------
CALCULATION AND REPAINT BEHAVIOR
------------------------------------------------------------
All detection logic runs exclusively on confirmed, closed bars. Nothing is
decided from an intrabar wick on the currently forming candle. A sweep
candidate's return window is evaluated bar by bar as it actually happens,
never by looking ahead. A confirmed Manipulation call can be superseded
later within the same range by the one-time re-arm described above, but
only by an equally real, fully confirmed opposite-side sweep — never
speculatively, and never by revising a call that has already led to a
resolved outcome. Once a range resolves, or a zone's phase has finished,
its boundaries are not redrawn or repainted. Higher-timeframe data is
requested with lookahead explicitly disabled, so historical bars never
change; only the still-forming higher-timeframe candle can naturally
update until it itself closes, which is standard behavior for any
multi-timeframe context reading and is not repainting in the sense of
historical values changing after the fact.
------------------------------------------------------------
LIMITATIONS
------------------------------------------------------------
This script is a structure-labeling tool, not a trading system. It has no
concept of risk management, position sizing, or trade execution, and it
does not account for spread, slippage, commissions, or liquidity
conditions specific to any individual broker or exchange. Detection
quality depends heavily on the instrument, timeframe, and chosen
sensitivity setting — a setting well suited to one market or timeframe may
under- or over-detect on another, and some manual tuning of the
sensitivity dial is expected. Past detected cycles, and the Follow-Through
Rate built from them, describe what has already happened on this specific
chart and are not a guarantee of how future cycles on the same chart, or
on any other chart, will behave.
------------------------------------------------------------
DISCLAIMER
------------------------------------------------------------
This script detects and labels historical and current market structure
per the AMD model only. Nothing it displays is a probability of future
price direction, a guarantee, or a buy or sell instruction — a
Manipulation event describes a liquidity sweep that has already happened,
not a prediction of what comes next, and a Distribution zone is only ever
drawn once the corresponding break has already confirmed. The Expected
Direction label is a restatement of the pattern's own definition, not a
forecast. The Follow-Through Rate is a tally of what has already happened
to this chart's own past Manipulation calls, typically a modest sample
size, and should not be read as a win rate or as investment advice.
Trading involves substantial risk of loss and is not suitable for every
investor. Nothing in this script or its description constitutes financial,
investment, or trading advice, and past structure detected by this
script is not indicative of future results. Use at your own discretion
and risk.
Индикатор

Индикатор

Session Fibs | Falcon AIAuto-draws Fibonacci retracement levels across a trading session's range, anchored to that session's own high and low.
Pick a session window and the script anchors the fib to it, then projects the 0 / 23.6 / 38.2 / 50 / 61.8 / 78.6 / 100% levels, with optional 127.2 and 161.8% extensions.
Two modes. Previous session (the default) fibs the range that has just COMPLETED and projects those levels onto the session now trading, giving you stable references that do not move under you. Current session anchors live to the developing high and low, so the levels update as the range extends. That is useful for watching a session build, but the levels shift intraday. Knowing which of the two you are looking at matters more than the ratios themselves: one is fixed, one is not.
How to read it: the 38.2 / 50 / 61.8% band holds the common pullback zones inside a range, and the 61.8-78.6% area is the classic deep retrace. Extensions are common measured-move targets beyond the range. Reference levels, not signals.
Settings: session window and timezone, previous or current session, flip the 0% and 100% ends, extensions on/off, line width and colours, shade the 61.8-78.6% zone, labels.
Session logic needs an intraday chart. The default window is the standard US index cash session; change it to whatever market you trade.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, or position-sizing logic. It is pure geometry off one session's high and low, with no trend model, pattern model or scoring. Your entry, your risk.
Educational tool only. Not financial advice. Fib levels are reference points, not predictions. Индикатор

Pivot Points | Falcon AIDraws Classic and Camarilla pivot levels from the previous period's high, low and close, on a daily or weekly anchor.
Classic pivots give you the central pivot plus three supports and three resistances, derived from the standard published formula. Camarilla uses a tighter multiplier set, so its levels sit closer to price and are read differently: the inner pair as mean-reversion boundaries, the outer pair as breakout markers. Both are drawn from the same prior-period data, so you can see where the two frameworks agree or disagree on a given day.
Levels are drawn as extended lines with optional labels and refresh automatically when a new period begins. You can show either set on its own or both together, and switch the anchor between daily and weekly. Only the current period extends to the right and carries labels, so the chart stays readable as history builds.
Settings: pivot period (Daily / Weekly), method (Classic / Camarilla / Both), include current unclosed period on or off, how many R/S pairs to show, periods of history to keep drawn, colours, widths, label side, info panel.
A note on repainting: by default the levels come from the last CLOSED period and stay fixed all session. Turning on "Include current (unclosed) period" deliberately opts into levels that move as the period develops.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, or position-sizing logic. It draws reference levels and nothing more. Your entry, your risk.
Educational tool only. Not financial advice and not a recommendation to buy or sell. Past price behaviour around any level does not predict future behaviour. Индикатор

Volatility Supply and Demand ZonesMost supply and demand tools have the same two problems. They stack near-identical zones on top of each other until the chart is unreadable, and they leave dead zones projecting to the right edge forever, long after price has traded straight through them. This script is built to fix both.
Everything here is measured in ATR, so the same settings behave proportionately on a quiet instrument and a violent one.
HOW A ZONE IS BUILT
A confirmed pivot marks the edge of a zone. Its depth is a fraction of ATR(50):
buffer = ATR(50) * zone depth / 10
A sell zone takes the pivot high as its top and extends the buffer downwards. A buy zone takes the pivot low as its bottom and extends the buffer upwards. A dotted mid line marks the centre of each zone.
Zone depth 2.5 therefore spans a quarter of one ATR. The zone is anchored to the bar the pivot actually formed on, not the bar that confirmed it.
WHY ZONES DO NOT PILE UP
This is the part that changes how the chart reads.
Before a zone is drawn, its midpoint is measured against the midpoint of every live zone on the same side. If it falls inside a separation band of a chosen ATR multiple, it is refused and nothing is drawn.
The effect is most obvious during consolidation, which is exactly where an unfiltered supply and demand indicator produces a dozen overlapping bands that all mean the same thing.
One detail matters here: a zone that has already been broken is removed from the live set, so it can never block a fresh zone that forms in the same price area later. Zones filter each other only while they are still alive.
WHAT HAPPENS WHEN A ZONE IS BROKEN
A sell zone is broken by a close above its top, a buy zone by a close below its bottom. There is a switch for wick-based breaks, which retires zones far more aggressively.
Three behaviours are available:
- Remove deletes the zone outright. Cleanest chart.
- Freeze at the break stops it extending, so it stays as history at the bar it died.
- Leave it running keeps it projecting forever, for anyone who wants the old behaviour.
Frozen zones are capped by the same memory setting, so they cannot accumulate without limit.
MARKET STRUCTURE
A second, stricter detector runs alongside the zones.
A swing is only accepted when price staircased into it and staircased back out of it. Every bar approaching the swing must be higher than the one before, and every bar leaving it lower, with the swing bar itself the extreme of its own window. This is deliberately narrower than a plain pivot and it produces fewer, cleaner levels.
Strict staircase can be turned off. In tolerant mode an equal high or low no longer rejects a swing; only a bar moving the wrong way does. On instruments that print repeated highs this finds noticeably more structure, and the difference is worth measuring on your own symbol.
When a close takes a swing level out, the level is spent and cannot fire again. The break is classified against the standing phase:
- shift, when the break reverses the phase, or when it is the first break on the chart and there is no phase to continue
- cont, when the break extends the phase already in force
The tag sits midway along the line back to the level it took out, so it reads as a label for the whole move rather than an annotation on one bar.
SUPPORT AND RESISTANCE RAYS
Optional and off by default. After a structure break, a backward scan finds the extreme reached between the swing and the break, then projects it forward until a close takes it out.
It is off by default because it runs a scan on every break. The scan limit is adjustable and bounds the work done on a single bar.
SETTINGS THAT MATTER MOST
- Pivot length decides how much structure becomes a zone. Shorter reacts faster and draws more.
- Zone depth sets thickness only. It does not change where zones appear.
- Separation is the single most effective control over chart density.
- Structure span controls the swing detector independently of the zones.
NOTES FOR ANYONE READING THE CODE
Two things in here are easy to get wrong, and both are commented in the source.
ta.highest and ta.lowest carry rolling state and must be evaluated on every bar. Placed behind an and operator they get short-circuited away whenever an earlier condition fails, their window is then built from a sparse history, and the comparison silently stops matching. They are hoisted to the global scope for that reason.
The retirement pass walks its array backwards. Removing entries during a forward pass makes the loop skip the element that slides into the vacated index. Counted loops are also guarded against an empty array, because a Pine for loop from 0 to size minus one counts downwards when the array is empty and reads index minus one.
LIMITATIONS
- A pivot is only confirmed a number of bars after it forms. That delay is inherent to pivot detection and no indicator can remove it, here or anywhere else.
- Zone edges are drawn where the pivot was, so a zone appears on the chart later than the bar it is anchored to.
- In a tight range the separation filter will refuse most new zones by design. That is the intent, but it does mean the chart can look sparse exactly when price is busiest.
- The structure detector is strict by default and will miss swings on instruments that print equal highs and lows. Turn strict staircase off if that matters on your symbol.
- Nothing here predicts direction. It marks where price previously turned and whether those levels are still intact.
- Nothing here is financial advice. Position sizing and risk management remain your own responsibility.
This is original work. It reuses no code from any other publication. The source is open, so read it, change it, and take it further.
Индикатор

Edo Swing StateEdo Swing State — Labels Every Swing as HH, HL, LH or LL and Resolves Market Structure into a Single State
Market structure is the skeleton beneath almost every method of technical analysis: an uptrend is a run of higher highs and higher lows, a downtrend a run of lower highs and lower lows, and the moment that sequence breaks is the moment a trend starts to change. Edo Swing State makes that skeleton explicit. It detects each price swing, labels it with its structural role — higher high (HH), higher low (HL), lower high (LH) or lower low (LL) — and combines the last high and last low into one readable market state.
It draws a swing line that connects the confirmed pivots, marks each swing with a coloured HH/HL/LH/LL label, and reads the whole into Bullish, Bearish or Ranging in a compact panel — all validated on closed bars so the indicator does not repaint. It is a self-contained structure reader: the swings, their roles and the resulting state are all derived from the price series on the chart alone, with no dependency on any other tool.
THE HH / HL / LH / LL CLASSIFICATION
The indicator compares each new swing with the previous one of the same type. A swing high above the previous high is a Higher High (HH); below it, a Lower High (LH). A swing low above the previous low is a Higher Low (HL); below it, a Lower Low (LL). Each label is written at the pivot and does not move. Rising highs and rising lows are the signature of buying strength; falling highs and falling lows, the signature of weakness. High labels are drawn above the swing, low labels below it, colour-coded green for the bullish roles and red for the bearish ones.
SWING PROFILES
The sensitivity of the swings is set by a single Swing Profile input: Scalper (5 bars each side) for fast intraday swings on low timeframes, Swing (10 bars, the default) for the balanced 4H and daily read, and Long Term (21 bars) for the major swings on weekly and higher horizons. The larger the length, the more significant a turn has to be, and the fewer but more important the swings that are marked.
THE MARKET STATE
Above the individual labels, Edo Swing State resolves one overall state by combining the role of the last high with that of the last low. Bullish requires a last high of HH and a last low of HL — rising highs and lows. Bearish requires a last high of LH and a last low of LL — falling highs and lows. Any mixed combination is treated as Ranging. Requiring both sides to agree is deliberate: if price makes a higher high but then loses the previous low, the structure is no longer cleanly bullish, and the state turns to Ranging — precisely the transition zone where a trend starts to fail before the full turn is confirmed. The first LH after a run of HHs, or the first HL after a run of LLs, is the earliest crack in a trend, labelled the moment it is confirmed.
THE SWING LINE
The swing line connects the confirmed pivots in a continuous zigzag, tracing only the legs that run from one swing to the next and filtering out the intermediate noise. It reveals the real skeleton of the move — where price accelerates and where it loses momentum. The line and the labels can each be toggled independently, for a cleaner or a more informative chart.
INFORMATION PANEL
The panel condenses the read into a compact table under the indicator header: the overall market state (Bullish / Bearish / Ranging), the role of the most recent confirmed swing, and the role of the last high and the last low, in the same green/red colour code. The state row is the underlying read; the last-high and last-low rows explain why the state is what it is. The panel sits in any of the four chart corners (Top Right by default), comes in three sizes (Tiny / Small / Normal) and two themes (Dark / Light), and can be hidden entirely. To keep the calculation light, it is drawn only on the last bar.
NO REPAINTING
Swings are built on confirmed pivots and the state change is validated on closed bars, so a label never appears or disappears intrabar. There are no higher-timeframe functions: all logic runs on the current chart timeframe, which keeps the indicator lightweight and repaint-free. For a multi-timeframe read, apply it on several charts at once and look for the confluence of states.
CONFIGURATION
The inputs are grouped by block. Structure sets the swing profile and toggles the HH/HL/LH/LL labels and the swing line, listed in the settings as Show structure line (zigzag). Style exposes the bullish and bearish colours, the line colour and width, the label size and the Dark/Light theme. Panel controls panel visibility, position and size. The defaults are calibrated to work without adjustment on stocks, crypto, forex, indices and futures, on any timeframe — the input most users touch is the Swing Profile, to match the swings' sensitivity to their trading horizon.
ALERTS
Six predefined alerts cover the structure read. Four swing alerts — New Higher High, New Higher Low, New Lower High and New Lower Low — fire when each new pivot is confirmed with its role. Two structure alerts — Structure Bullish and Structure Bearish — fire only on the phase turn, when the overall state flips. All alerts fire on bar close, consistent with the indicator's anti-repaint validation.
HOW TO READ IT
Use the state as a context filter: look for longs while structure is Bullish and shorts while it is Bearish, and treat Ranging as caution — the zone where trends run out and false moves cluster. Use the change labels as an early warning: the first LH after a series of HHs, or the first HL after a series of LLs, flags a fading trend before the overall state fully turns. And read it in confluence: a Bullish state on the trading timeframe that sits inside a Bullish state on a higher one is a far more solid trend than an isolated read. Read on its own terms, the sequence of labels is the whole method: the roles say what the market is doing, and the state says whether it is doing it cleanly.
OPEN SOURCE
Edo Swing State is published as a free open source indicator. The full Pine Script is publicly accessible on TradingView for study, adaptation and integration into any workflow. Part of the Edolab Markets free tools ecosystem, all available on TradingView.
This indicator is a technical analysis tool for educational and informational purposes only. It does not generate automatic buy or sell signals and should not be considered financial advice. Trading financial markets involves significant risk of capital loss. Past performance does not guarantee future results. Always use proper risk management.
Индикатор

RTH 1st Presented FVGPlots the first Fair Value Gap of the Regular Trading Hours session and keeps those levels on the chart.
First presented FVG
Detects the first 3-candle wick-and-body FVG after the cash open. The middle candle cannot be the 09:30 bar, so the earliest valid gap starts at 09:31. By default the gap is measured on 1-minute data and drawn on any chart up to the Max Timeframe. Turn on “Use Chart Timeframe for 1st Presented” to measure it on the chart’s own timeframe instead.
Gradient Levels
Each gap can show high/low, equilibrium, quartiles, and optional eighths. One label sits at the midpoint. Boxes and lines can extend right with a bar buffer.
History
Choose how many daily first-FVGs to keep. Optionally keep a separate count of Monday and Friday gaps so those days stay visible longer.
Premium / Discount
Builds a range from recent first-FVG highs and lows. A table shows premium or discount versus equilibrium, with optional gradient lines at high, low, mid, quartiles, and eighths.
Overlapping FVGs
Optionally highlight later FVGs that trade through a stored first-FVG level. Can limit that to the first overlap of the session.
Session hours, timezone, colors, line styles, and Max Timeframe are all user-controlled. Индикатор

52 Week High/Low Offset ScreenerTitle:
52 Week High/Low Offset Screener
Visibility: Open (recommended) or Protected
Category: Indicator (not overlay)
Companion script: 52 Week High/Low (Current & Offset)
→ After the indicator is published, paste its script URL here in the description
(English NOTES / German HINWEISE).
----- Description (paste below; English first) -----
█ OVERVIEW
This is a Pine Screener companion to “52 Week High/Low (Current & Offset)”.
It scans a watchlist for where price sits relative to a lagged 52-week high/low (default offset: 52 weeks). You can constrain those distances in the script settings and/or with column filters in the Pine Screener.
Same calculation as the chart indicator. This script does not overlay on price; it outputs columns and a Hit flag.
This is a scan helper, not a buy or sell signal.
█ HOW TO RUN THE SCAN
1. Add this script to your Favorites (star). It will not appear in Pine Screener otherwise.
2. Open Products → Screeners → Pine (or tradingview.com/pine-screener/).
3. Choose a watchlist (keep it under 1,000 symbols).
4. Select “52 Week High/Low Offset Screener”.
5. Set the timeframe (daily is typical) and optional distance filters in the script settings.
6. Click Scan.
7. To apply the built-in distance filters, add a column filter: Hit = 1.
Only one Pine script can be used per scan.
█ COLUMNS
• Hit — 1 if all enabled script filters match, otherwise 0
• Distance % nearer offset — distance to the closer of the two offset levels
• Nearer to (1=High, −1=Low)
• Distance % offset high / offset low
• Offset high / Offset low — lagged 52-week levels
• Current 52W high / Current 52W low
• Close
Distance formula:
(close − offset level) / close × 100
Positive = price above that level, negative = below.
█ DISTANCE FILTERS (SCRIPT SETTINGS)
Disabled filters are ignored. All enabled filters must pass for Hit = 1.
• Side: All / only nearer to offset high / only nearer to offset low
• Constrain nearer distance (from % / to %)
• Constrain distance to offset high
• Constrain distance to offset low (DCA-style example: −15 to +8)
• Only below offset low
• Only above offset high
You can also filter on the columns themselves. Numeric filters are literal:
• Distance % offset low < 1 includes +0.08 (slightly above the low) and −16 (below the low)
• Below the offset low only: Distance % offset low < 0
• At least 1% below the low: Distance % offset low < −1
• Within 1% of the low: between −1 and 1
█ ALERT
Alert condition “52W Offset Hit” fires when a symbol matches the script’s distance filters.
█ NOTES
• Uses 52 weekly bars and a weekly offset; the current 52-week high/low includes the developing week.
• Chart companion: “52 Week High/Low (Current & Offset)”.
(Add the published indicator URL here after step 1 of the publishing sequence.)
This script does not generate trading signals and is not investment advice.
--------------------------------------------------------------------------------
DEUTSCH
█ ÜBERBLICK
Das ist der Pine-Screener zum Indikator „52 Week High/Low (Current & Offset)“.
Er scannt eine Watchlist danach, wo der Kurs relativ zu einem zeitversetzten 52-Wochen-Hoch/-Tief steht (Standard-Offset: 52 Wochen). Diese Abstände kannst du in den Skript-Einstellungen und/oder über Spaltenfilter im Pine Screener eingrenzen.
Dieselbe Berechnung wie der Chart-Indikator. Dieses Skript liegt nicht über dem Kurs; es liefert Spalten und ein Hit-Flag.
Das ist eine Scan-Hilfe, kein Kauf- oder Verkaufssignal.
█ SCAN AUSFÜHREN
1. Dieses Skript zu den Favoriten hinzufügen (Stern). Sonst erscheint es nicht im Pine Screener.
2. Products → Screeners → Pine öffnen (oder tradingview.com/pine-screener/).
3. Eine Watchlist wählen (unter 1.000 Symbole halten).
4. „52 Week High/Low Offset Screener“ auswählen.
5. Timeframe setzen (typisch Tageschart) und optional die Abstandsfilter in den Skript-Einstellungen.
6. Scan klicken.
7. Um die eingebauten Abstandsfilter anzuwenden, Spaltenfilter setzen: Hit = 1.
Pro Scan kann nur ein Pine-Skript verwendet werden.
█ SPALTEN
• Hit — 1, wenn alle aktivierten Skript-Filter zutreffen, sonst 0
• Distance % nearer offset — Abstand zum näheren der beiden Offset-Niveaus
• Nearer to (1=High, −1=Low)
• Distance % offset high / offset low
• Offset high / Offset low — zeitversetzte 52-Wochen-Niveaus
• Current 52W high / Current 52W low
• Close
Abstandsformel:
(Schlusskurs − Offset-Niveau) / Schlusskurs × 100
Positiv = Kurs über diesem Niveau, negativ = darunter.
█ ABSTANDSFILTER (SKRIPT-EINSTELLUNGEN)
Deaktivierte Filter werden ignoriert. Alle aktivierten Filter müssen für Hit = 1 gleichzeitig erfüllt sein.
• Side: All / only nearer to offset high / only nearer to offset low
• Constrain nearer distance (from % / to %)
• Constrain distance to offset high
• Constrain distance to offset low (DCA-Beispiel: −15 bis +8)
• Only below offset low
• Only above offset high
Du kannst auch direkt über die Spalten filtern. Numerische Filter gelten wörtlich:
• Distance % offset low < 1 enthält +0,08 (knapp über dem Tief) und −16 (unter dem Tief)
• Nur unter dem Offset-Tief: Distance % offset low < 0
• Mindestens 1 % unter dem Tief: Distance % offset low < −1
• Höchstens 1 % vom Tief entfernt: zwischen −1 und 1
█ ALERT
Die Alert-Bedingung „52W Offset Hit“ löst aus, wenn ein Symbol die Abstandsfilter des Skripts erfüllt.
█ HINWEISE
• Nutzt 52 Wochenkerzen und einen Wochen-Offset; das aktuelle 52-Wochen-Hoch/-Tief bezieht die laufende Woche ein.
• Chart-Begleiter: „52 Week High/Low (Current & Offset)“.
(Nach der Indikator-Veröffentlichung hier die Skript-URL einfügen.)
Dieses Skript erzeugt keine Handelssignale und ist keine Anlageberatung.
Индикатор

52 Week High/Low (Current & Offset)Title:
52 Week High/Low (Current & Offset)
Visibility: Open (recommended) or Protected
Category: Overlay / indicator
Companion script: 52 Week High/Low Offset Screener
----- Description (paste below; English first) -----
█ OVERVIEW
This indicator plots two 52-week ranges at once:
• Current 52-week high/low, including today’s price, as two horizontal lines.
• Historical 52-week high/low, lagged by a user-defined number of weeks, as a full history.
The current range always moves with price. After a sharp rally or sell-off that can make the live 52-week band less useful for context (for example dollar-cost averaging). The offset range shows where the 52-week high and low stood N weeks ago, before the latest move fully rewrote those extremes.
A distance label shows how far the close is from the nearer offset level, in percent of the current price. Positive = price is above that level, negative = below.
This is a positioning tool, not a buy or sell signal.
█ HOW IT WORKS
Current 52-week high/low
Calculated on the weekly timeframe over 52 weeks and combined with the developing week’s high/low on the chart timeframe, so today’s price is included.
Historical 52-week high/low (offset)
The same 52-week calculation, shifted by N weekly bars (default: 52). The offset is applied on the weekly timeframe, not in chart bars, so “52 weeks” remains 52 weeks on a daily chart.
Distance %
(close − offset level) / close × 100
The label is attached to whichever offset level is closer in price:
• Orange = nearer the offset high
• Teal = nearer the offset low
If the current 52-week high and the offset high print as the same price, they are merged into one label: “52W High = Offset”. The same logic applies independently to the low.
█ HOW TO USE
1. Add the script to a chart (daily is a typical timeframe).
2. Set Historical offset (weeks). Default is 52 (about one year); 13 ≈ one quarter, 4 ≈ one month.
3. Read price against the white historical path, not only against the green/red current lines.
4. Use the distance label and the table (Current vs −Nw) for a quick readout.
Reading for DCA-style context (not advice):
• Near the offset low, slightly negative or slightly positive → closer to the older low.
• Near the offset high, small negative → still below the older high, relatively expensive vs that band.
• Near the offset high, positive → price has left the older high.
█ SETTINGS
52-week setup
• Basis for 52-week values: Highs/Lows (default) or Close
• Historical offset (weeks)
Current 52W High/Low
• Horizontal lines, colors, width, style (solid / dashed / dotted), price labels
Historical 52W High/Low (Offset)
• History on/off, colors, fill, fill color
• In the Style tab, historical lines default to dashed and can be switched to solid or dotted
Info panel
• Table on/off, position, distance label
█ NOTES AND LIMITS
• 52 weeks means 52 weekly bars, not exactly 365 calendar days.
• The current 52-week high/low updates with the developing week.
• The offset uses closed weekly values (no lookahead inside the forming week).
• Companion screener: “52 Week High/Low Offset Screener” (add to Favorites, then Products → Screeners → Pine).
This script does not generate trading signals and is not investment advice.
--------------------------------------------------------------------------------
DEUTSCH
█ ÜBERBLICK
Der Indikator zeigt zwei 52-Wochen-Spannen gleichzeitig:
• Das aktuelle 52-Wochen-Hoch/-Tief inklusive heutigem Kurs, als zwei horizontale Linien.
• Das historische 52-Wochen-Hoch/-Tief, um eine wählbare Anzahl Wochen versetzt, als vollständigen Verlauf.
Die aktuelle Range wandert immer mit dem Kurs. Nach einer starken Rally oder einem Ausverkauf ist das live 52-Wochen-Band für den Kontext oft weniger nützlich (zum Beispiel beim Averagen / DCA). Die Offset-Range zeigt, wo Hoch und Tief vor N Wochen standen, bevor die jüngste Bewegung diese Extreme überschrieben hat.
Das Abstands-Label zeigt, wie weit der Schlusskurs vom näheren Offset-Niveau entfernt ist (in % vom aktuellen Kurs). Positiv = Kurs liegt darüber, negativ = darunter.
Das ist eine Lagehilfe, kein Kauf- oder Verkaufssignal.
█ BERECHNUNG
Aktuelles 52-Wochen-Hoch/-Tief
Berechnung auf dem Wochen-Timeframe über 52 Wochen, kombiniert mit dem laufenden Wochenhoch/-tief auf dem Chart-Timeframe, damit der heutige Kurs einbezogen wird.
Historisches 52-Wochen-Hoch/-Tief (Offset)
Dieselbe 52-Wochen-Berechnung, um N Wochenkerzen verschoben (Standard: 52). Der Versatz greift auf dem Wochen-Chart, nicht in Chart-Balken. „52 Wochen“ bleiben also auch auf dem Tageschart 52 Wochen.
Abstand %
(Schlusskurs − Offset-Niveau) / Schlusskurs × 100
Das Label hängt an dem Offset-Niveau, das preislich näher liegt:
• Orange = näher am Offset-Hoch
• Türkis = näher am Offset-Tief
Sind aktuelles 52W-Hoch und Offset-Hoch als derselbe Preis dargestellt, werden sie in einem Label zusammengefasst: „52W High = Offset“. Dieselbe Logik gilt unabhängig fürs Tief.
█ NUTZUNG
1. Skript auf einen Chart legen (Tageschart ist ein üblicher Timeframe).
2. Historical offset (weeks) einstellen. Standard ist 52 (ca. ein Jahr); 13 ≈ ein Quartal, 4 ≈ ein Monat.
3. Den Kurs gegen den weißen historischen Verlauf lesen, nicht nur gegen die grünen/roten aktuellen Linien.
4. Abstands-Label und Tabelle (Current vs. −Nw) für die schnelle Ablesung nutzen.
Lesart für DCA-Kontext (keine Empfehlung):
• Nah am Offset-Tief, leicht negativ oder leicht positiv → näher am älteren Tief.
• Nah am Offset-Hoch, leicht negativ → noch unter dem älteren Hoch, relativ teuer zu diesem Band.
• Nah am Offset-Hoch, positiv → der Kurs hat das ältere Hoch verlassen.
█ EINSTELLUNGEN
52-week setup
• Basis for 52-week values: Highs/Lows (Standard) oder Close
• Historical offset (weeks)
Current 52W High/Low
• Horizontale Linien, Farben, Stärke, Stil (solid / dashed / dotted), Preis-Labels
Historical 52W High/Low (Offset)
• Verlauf an/aus, Farben, Füllung, Füllfarbe
• Im Tab Style sind die historischen Linien standardmäßig gestrichelt und können auf durchgezogen oder gepunktet gestellt werden
Info panel
• Tabelle an/aus, Position, Abstands-Label
█ HINWEISE UND GRENZEN
• 52 Wochen bedeutet 52 Wochenkerzen, nicht exakt 365 Kalendertage.
• Das aktuelle 52-Wochen-Hoch/-Tief aktualisiert sich mit der laufenden Woche.
• Der Offset verwendet geschlossene Wochenwerte (kein Vorgriff innerhalb der entstehenden Woche).
• Begleit-Screener: „52 Week High/Low Offset Screener“ (zu den Favoriten, dann Products → Screeners → Pine).
Dieses Skript erzeugt keine Handelssignale und ist keine Anlageberatung. Индикатор

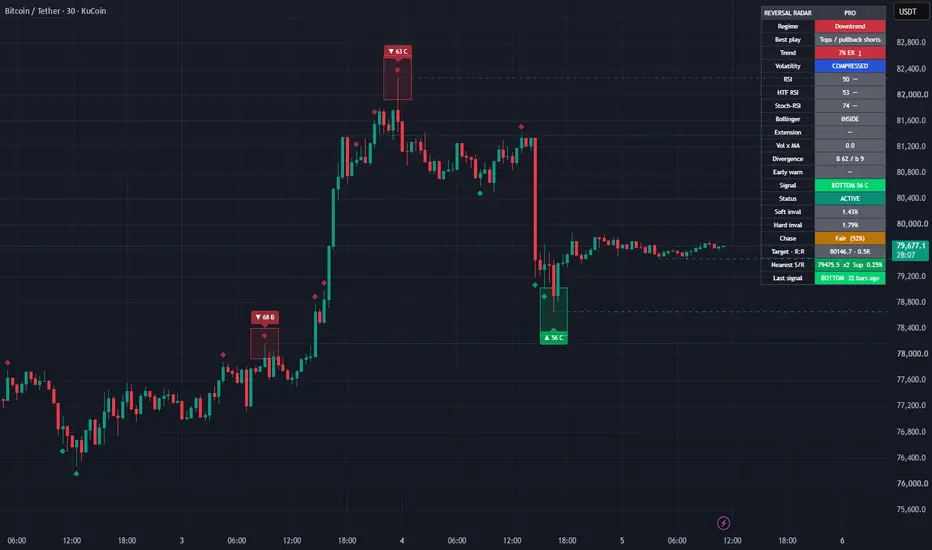
Reversal Radar PRO | Market Tops & Bottoms
↺ Reversal Radar PRO — Tops & Bottoms
Most “reversal” tools fire one arrow and disappear. This one runs three layers: a heads-up while the bar is still forming, a confirmed print after the swing is locked, and a live status on whether that reversal is still valid.
The point is not to catch every wick. It is to grade the turn, map the zone, and tell you when the chase is already late.
① Early-warning
Live-bar gauge. It can repaint — that is stated on purpose. Use it as danger / opportunity forming, not as an entry.
② Confirmed
Pivot-locked after the right-side bars. Does not repaint. Weighted 0–100 confidence with a grade, a vote floor, and a cooldown. Factors that can vote: RSI extreme, RSI divergence (quality-scored), volume climax, Bollinger pierce, over-extension from the mean, Stoch-RSI, wick rejection, engulfing, higher-TF RSI, liquidity sweep. Regime can boost or cut the score. Hidden divergence trims it — that is continuation, not a turn.'
③ Follow-through
Once a confirmed top or bottom is on, the radar tracks:
Active / late / soft invalid / hard invalid / target hit
Soft and hard invalidation distances
Chase quality (good → poor) vs progress to target
Mapped target and R:R
🗺 On the chart
Confirmed labels (confidence + grade) or simple arrows
Tiny diamonds for early-warning
Reversal zone boxes at the pivot
Clustered S/R that merge nearby swings, count touches, and flip when broken
📟 Dashboard
Regime and “best play” (fade the trend, or both sides). Trend efficiency. Volatility state. RSI / HTF RSI / Stoch-RSI. Bollinger position. Extension. Volume vs average. Divergence quality. Early-warn reading. Active signal, status, chase, target. Nearest S/R. Last print and how many bars ago.
🎯 How to use it
Wait for confirmed unless you accept that early-warning will flicker. In a strong uptrend, bottoms are the preferred fade — not every red wick. If chase already reads late, you missed the turn; do not market-order the remainder. Hard invalidation ends the idea. Soft invalidation is a warning, not a rewrite of history. Индикатор

Opening Range Breakout [ITA]🟠 OVERVIEW
Opening Range Breakout marks the high and low of the first minutes of the trading session, extends those boundaries forward, and flags the bar where price closes outside them. The range is built live as the session opens, tracking its running high and low, then locks once the opening period ends.
Once the range is set, the indicator measures its height and projects extension targets above and below it. Four range lengths are available, and the session open time and timezone are configurable so the tool works on any market rather than being fixed to a single exchange.
🟠 CONCEPTS
* Opening Range - The high and low established during the first minutes of the session. Represents the initial boundaries of agreement between buyers and sellers before the day develops.
* Range Lock - The moment the opening period ends and the boundaries stop updating. From that bar onward the levels extend forward unchanged.
* Extension Target - A projected level placed at a multiple of the range height above the range high or below the range low. Acts as a measured move reference rather than a prediction.
* Qualified Breakout - The first close outside the range in a given direction. Each direction is tracked independently and marked only once, so a session that breaks up, reverses and then breaks down shows both events without repeating either.
* Session Anchoring - The range window is evaluated in the selected timezone rather than the chart timezone, keeping it aligned to the actual market open regardless of the user's location.
🟠 FEATURES
* Selectable Range Length - Choose between 5, 15, 30 or 60 minute opening ranges.
* Live Range Building - The box tracks the running high and low as the opening period develops, then locks when it closes.
* Extension Targets - Projects two configurable multiples of the range height in both directions.
* Breakout Marking - Labels the first close outside the range in each direction.
* Breakout Alerts - Fires on upside and downside breaks independently.
🟠 HOW TO USE
* Match the range length to the instrument. Shorter ranges suit fast-moving markets and scalping, longer ranges suit index futures and higher-priced equities where the first minutes tend to be noisy.
* Set the session open time and timezone to your market. The default is 09:30 New York.
* Use the range boundaries as the reference for the session. Price holding inside them points to rotation, while a decisive close outside tends to set the tone for the rest of the day.
* Read the extension targets as measured moves. A tight opening range produces close targets, while a wide one produces targets that may take the full session to reach, which is itself useful when sizing expectations.
* Adjust Days to Display to keep the chart clean when reviewing several sessions of history.
🟠 CONCLUSION
Opening Range Breakout combines automatic range detection, forward-extending boundaries, and range-based extension targets in a single tool. It removes the manual work of marking the opening range each session while keeping the framework configurable enough to apply across different markets and session times. Индикатор

MTF Supply & Demand (PropFirmGorilla)This indicator detects supply and demand zones across eight timeframes at once — 15m, 30m, 1H, 90m, 2H, 4H, 690m and Daily — and draws them on whatever chart you're viewing, so you don't have to flip timeframes to map higher-timeframe levels.
How a zone is found
Each zone is built from an impulse candle and the basing candle immediately before it:
Demand: a bullish impulse candle that moves up at least a set % (open→close) and closes in the top portion of its range, preceded by a small down-closing basing candle whose body is no larger than a set % of the impulse body. The zone runs from the basing candle's open down to its low.
Supply: the mirror — a bearish impulse that closes near its low, preceded by a small up-closing basing candle. The zone runs from the basing candle's high down to its open.
A zone is removed automatically once price trades back through it (through the zone low for demand, the zone high for supply), so the chart only shows levels that are still unmirrored.
Non-repainting
Higher-timeframe zones are read from closed bars only (confirmed history, no lookahead), so a zone appears after its impulse candle closes and does not repaint on reload.
Features:
8 timeframes, each toggled on/off independently.
Simplify Zones: when same-side zones overlap, merge them into one rectangle labeled with every timeframe involved (e.g. "90m / 30m / 15m") to reduce clutter.
Box or line display: filled zones, or a single line at each zone's origin.
Separate colors and adjustable opacity for demand vs supply.
Each zone is labeled with its timeframe.
Adjustable detection thresholds (impulse move %, close-in-range %, basing body %) and a cap on zones per timeframe.
How to use
Add it to any chart. Zones from all enabled timeframes appear as colored areas extended to the right. Treat demand zones as potential support and supply zones as potential resistance; a zone disappears once price closes through it. Tune the detection inputs to match the instrument's volatility, and enable Simplify Zones on lower timeframes where many zones stack up.
Inputs
Zone Detection: Impulse min move (%), Impulse close in range (%), Basing body max vs impulse (%), Max zones per timeframe.
Timeframes: 15m / 30m / 1H / 90m / 2H / 4H / 690m / Daily.
Appearance: Show demand / Show supply, Demand & Supply colors, Fill opacity, Fill boxes (off = origin line only), Simplify Zones, Show timeframe label.
Notes
90m and 690m are requested as custom minute resolutions; if your plan or symbol doesn't return one, untick that timeframe.
Higher-timeframe zones need that timeframe's history to be available; extend the chart's loaded history if a timeframe looks sparse.
This tool is for chart analysis and education only. It is not financial advice; test any approach before trading it.
Индикатор

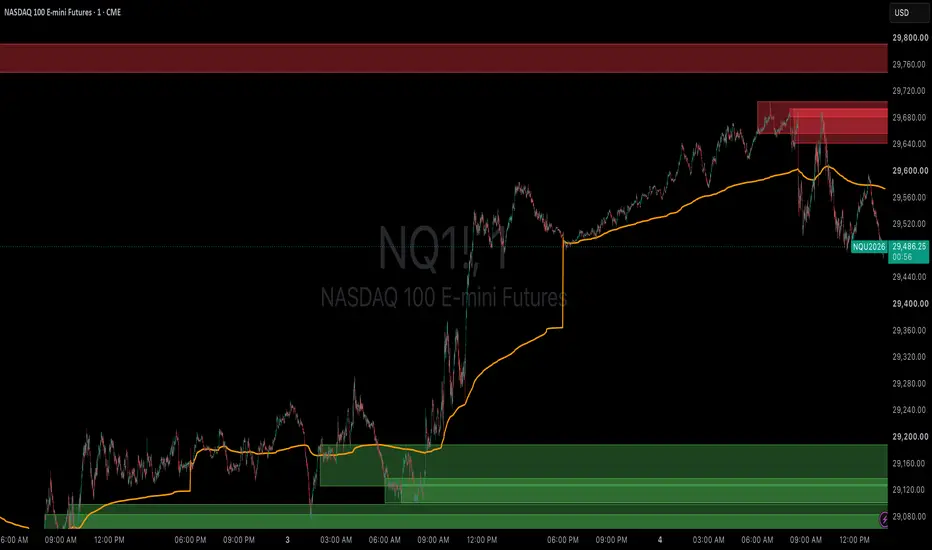
Multiday Anchored Auto VWAP by ByblloOVERVIEW
Multiday Anchored Auto VWAP plots up to 10 automatically anchored, rolling Volume Weighted Average Price (VWAP) lines - Rolling Day #0 (today) through Rolling Day #9 (9 days ago) - plus 5 fully independent manual VWAP lines you anchor to any date/time you choose.
Unlike anchored-VWAP tools that force a choice between automatic or manual mode, the 10 automatic Rolling Day lines and the 5 Manual Input lines here run completely independently and can be shown together - keep the last few rolling days visible for a short-term picture while also anchoring a Manual line to a specific earnings date or session open.
INTENDED USE
Well suited to short-term futures scalping - Nasdaq futures (NQ/MNQ) and similar instruments. Primarily used on the 1-minute chart, but the rolling VWAP levels hold up just as well on 2, 3, and 5-minute charts and other intraday timeframes, since the anchor logic is independent of your chart's timeframe.
FEATURES
- 10 automatic Rolling Day VWAP lines, each recalculated fresh from "now" every run (via timenow) - no hardcoded dates, so the lines never go stale or need republishing.
- 5 independent Manual Input VWAP lines with full date/time pickers, for anchoring to a specific event, earnings date, or session open.
- Single "Auto Mode Session Start Time (HHMM)" input applies to all 10 rolling lines at once - default 07:00 (Asia/Seoul), aligned with the Nasdaq futures (Globex) 18:00 ET session open during US Daylight Saving Time (shifts to 08:00 KST during US Standard Time - adjust as needed around the DST transition).
- Calendar-day based rolling (not trading-day based) for simple, predictable anchoring - see the author's companion script "Multiday VWAP by Bybllo" if you need trading-day-aware anchoring instead.
- Anchor-point safety guard prevents accumulation before each line's actual start, so no artificial spikes at the anchor bar.
- Optional anchor-start labels (#0-#9, M1-M5) marking exactly where each line begins.
- Works on any chart type (candlestick, Heikin Ashi, Renko, etc.) since prices are pulled via request.security() from the underlying ticker.
This script requires volume data from your data provider. For educational and informational purposes only, not financial advice. Always verify how these levels behave on your specific symbol and timeframe before relying on them for live trading. Индикатор

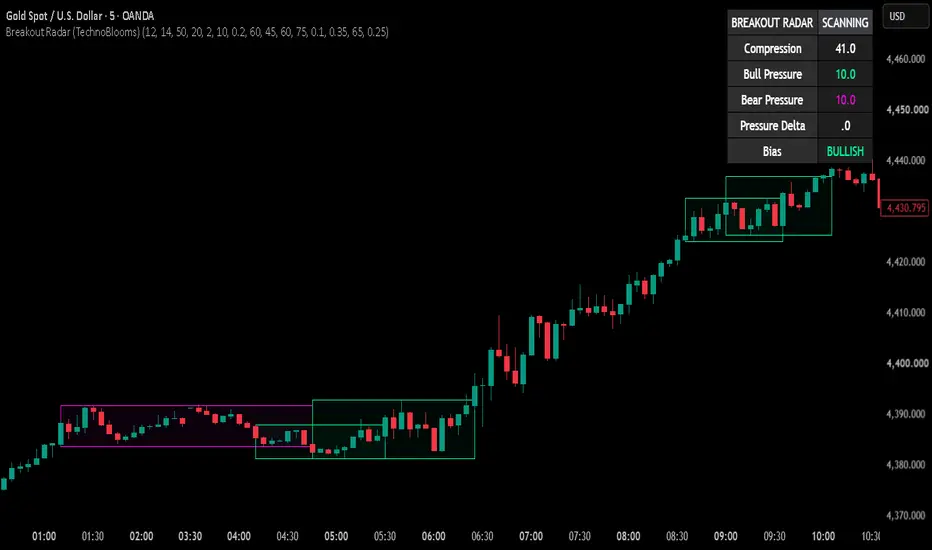
Breakout Radar (TechnoBlooms)Breakout Radar (TechnoBlooms)
Compression • Pressure • Bias • Breakout Confirmation
A structure-first breakout analysis tool designed to identify when quiet price action is building toward a directional move.
Overview
Breakout Radar is a price-compression and breakout-pressure indicator developed by TechnoBlooms. Instead of simply marking every new high or low as a breakout, it first looks for a compressed market structure, measures the pressure developing inside that structure, identifies directional bias, and then waits for price to confirm a break beyond the locked range.
The objective is simple: help traders distinguish between ordinary sideways movement and a consolidation that may be preparing for expansion. The indicator is designed as a decision-support tool, not as an automatic buy/sell system.
What Makes Breakout Radar Different?
Compression first: The system searches for contraction in volatility and price structure before considering a breakout.
Locked structure boxes: Once a qualifying compression is detected, its boundaries are locked instead of continuously following price like a conventional range filter.
Bull vs Bear Pressure: The indicator evaluates how price is behaving near the upper and lower boundaries and converts that behaviour into separate Bull Pressure and Bear Pressure readings.
Pressure Delta and Bias: The difference between bullish and bearish pressure helps identify whether the structure is leaning BULLISH, BEARISH or remains NEUTRAL.
Progressive radar states: The setup develops through SCANNING, BUILDING, WATCH and ARMED states rather than jumping immediately to a signal.
Confirmed breakout: A breakout requires price to close beyond the locked structure with an ATR-based confirmation buffer.
Signal validity buffer: After confirmation, the latest breakout signal can remain valid through a normal retest and is removed only when its stored invalidation level is breached or a newer breakout replaces it.
Clean historical context: Completed compression structures remain faintly visible so traders can study how earlier consolidations resolved, while overlap filtering reduces unnecessary nested boxes.
How to Read the Dashboard
Dashboard Item Interpretation
Compression Measures how strongly the current market is contracting. Higher values indicate tighter compression relative to recent conditions.
Bull Pressure Measures bullish pressure developing inside the active structure.
Bear Pressure Measures bearish pressure developing inside the active structure.
Pressure Delta Bull Pressure minus Bear Pressure. A positive value favours bulls; a negative value favours bears.
Bias Summarises the current directional pressure as BULLISH, BEARISH or NEUTRAL.
Radar State SCANNING = no active setup; BUILDING = compression found; WATCH = pressure is becoming meaningful; ARMED = pressure and compression have reached stronger conditions.
Understanding the Radar States
SCANNING — The indicator is monitoring the market, but no qualifying compression structure is currently active.
BUILDING — A compression structure has been identified. Pressure is developing, but the setup is not yet strong enough to demand close attention.
WATCH — Pressure has strengthened. Traders may begin watching the box boundaries and directional bias more closely.
ARMED — Compression and directional pressure have reached stronger conditions. This does not mean a breakout has already happened; it means the structure deserves heightened attention.
How the Breakout Signal Works
A bullish breakout is considered confirmed when price closes above the locked upper boundary plus the configured ATR confirmation buffer and bullish pressure is stronger than bearish pressure. A bearish breakout uses the opposite logic below the lower boundary.
Only the latest relevant breakout arrow is retained. The arrow is intentionally small so the chart remains focused on structure rather than becoming filled with historical signal markers.
The signal is not automatically removed after a fixed number of candles. At the moment of confirmation, Breakout Radar stores an ATR-based invalidation level. This allows price to perform a normal retest without immediately cancelling the breakout. The signal disappears when the breakout is invalidated or when a newer confirmed breakout replaces it.
Example 1 — Bullish Compression Breakout
Assume a stock trades sideways between ₹980 and ₹1,000 while volatility contracts. Breakout Radar identifies the compression and locks a box around the structure. As price repeatedly tests the upper portion of the box, Bull Pressure rises from 48 to 64 and then to 78, while Bear Pressure remains near 42.
The dashboard may progress from BUILDING → WATCH → ARMED with a BULLISH bias. If price subsequently closes above the upper boundary plus the breakout confirmation buffer, a small bullish arrow appears. A minor pullback toward the breakout area does not automatically remove the signal; it remains valid until the stored bullish invalidation level is breached.
Example 2 — Bearish Compression Breakout
Imagine an index consolidating between 24,800 and 25,000. During the consolidation, repeated pressure develops near the lower boundary. Bear Pressure increases to 81 while Bull Pressure falls to 51, producing a negative Pressure Delta and a BEARISH bias.
Once price closes below the locked lower boundary with the required ATR buffer, the bearish breakout is confirmed and a small downward arrow appears. The completed compression box remains on the chart as historical context while the Radar is free to scan independently for the next compression structure.
Example 3 — Why ARMED Is Not the Same as BUY or SELL
Suppose Compression is 76, Bull Pressure is 80 and Bear Pressure is 49. The Radar can show ARMED with a BULLISH bias even though price is still inside the box. This is an early-warning condition, not a trade confirmation. If price fails to break the upper boundary and pressure weakens, the setup can remain inside the structure or change bias. The breakout arrow appears only after the actual confirmation condition is met.
Reading the Boxes
The rectangles represent detected compression structures. The active structure is used for live pressure and breakout analysis. After a breakout, the completed box can remain lightly visible to show where the expansion originated. An overlap filter is used to reduce repeated boxes representing substantially the same price structure.
How Breakout Radar Compares with Other Popular Tools
Breakout Radar shares some visual ideas with range filters, order blocks, and support/resistance tools because all of them study how price behaves around important areas. The similarity, however, is mainly in the chart structure. Breakout Radar is built for a different question: is the market compressing, which side is applying more pressure, and has that compression actually expanded into a confirmed breakout?
Tool Main Purpose Similarity Key Difference
Range Filter Smooth price noise and identify directional movement or a filtered trading range. Both may show boundaries around price and can help traders recognise a transition from sideways movement to expansion. A range filter usually moves or recalculates with price. Breakout Radar first detects compression, locks the structure, measures Bull/Bear Pressure inside it, and waits for a buffered close outside the box.
Order Block Mark price areas associated with prior institutional-style supply/demand concepts or displacement. Both can leave historical zones on the chart and both may become areas traders watch during later price interaction. Breakout Radar does not claim to identify institutional orders or actual order flow. Its boxes represent measured compression structures, not order blocks. Direction is assessed from price behaviour and pressure within the compression.
Support & Resistance Identify levels or zones where price has previously reacted, stalled, reversed, or broken. The top and bottom of a Breakout Radar box naturally act as temporary resistance and support while the compression remains active. Traditional S&R starts with reaction levels. Breakout Radar starts with volatility/structure compression and then adds pressure, bias, state progression and breakout confirmation.
Breakout Radar Identify compressed structures, measure directional pressure, and confirm expansion beyond a locked range. Uses price boundaries just as many classical technical tools do. Combines compression scoring, locked boxes, Bull/Bear Pressure, Pressure Delta, Bias, BUILDING/WATCH/ARMED states, ATR breakout confirmation and signal invalidation in one workflow.
1. Breakout Radar vs Range Filter
The closest visual comparison is a range filter because both can make consolidation and directional movement easy to see. But Breakout Radar is not designed to continuously filter price. Once a qualifying compression is found, the box is locked. The indicator then studies what is happening inside that fixed structure. A trader can therefore see whether pressure is building toward the upper boundary, the lower boundary, or neither.
Example: price may remain inside a ₹500-₹510 box while Bull Pressure rises from 52 to 79. A conventional range filter may simply continue tracking the range or trend. Breakout Radar can move from BUILDING to WATCH to ARMED while the price is still inside the box, and only confirms the bullish breakout after a close above the upper boundary plus the ATR confirmation buffer.
2. Breakout Radar vs Order Blocks
An order-block indicator normally attempts to identify a zone associated with an earlier impulsive move and treats that area as a possible future supply or demand zone. Breakout Radar does something different: the rectangle is created because the current market has compressed, not because the script is labelling an institutional order area.
The historical boxes may therefore look superficially similar to order-block zones, but their meaning is different. A green completed Breakout Radar box means a compression structure eventually resolved upward; a red completed box means it resolved downward. It should not be interpreted as proof that institutional buying or selling occurred inside that box.
3. Breakout Radar vs Support & Resistance
Support and resistance are still relevant to Breakout Radar. In fact, the lower and upper boundaries of an active compression naturally behave like short-term support and resistance. The difference is that those boundaries are only one layer of the analysis.
Breakout Radar also asks whether volatility is compressed, how frequently price is pressuring each boundary, where price is persisting inside the structure, whether the internal structure is squeezing in one direction, and whether the final candle behaviour supports that direction. These components feed the Bull Pressure, Bear Pressure, Pressure Delta and Bias readings.
Where They Can Be Used Together
These tools do not have to compete with one another. A trader may use higher-timeframe support/resistance or a separately identified order-block area for context, then use Breakout Radar on the execution timeframe to see whether price is compressing near that area and whether directional pressure is developing. Likewise, a range or trend tool can provide broader directional context while Breakout Radar focuses specifically on the compression-to-expansion phase.
A Simple Way to Remember the Difference
• Range Filter asks: Where is filtered price/trend moving?
• Order Block asks: Where is a previously significant supply/demand-style zone?
• Support & Resistance asks: Where has price reacted or may react again?
• Breakout Radar asks: Is price compressing now, which side is building pressure, and has expansion been confirmed?
This distinction is central to the TechnoBlooms concept: the box itself is not the signal. The information comes from the evolution of compression, pressure, bias and eventual breakout confirmation.
Suggested Workflow
1. Look for an active compression box rather than chasing price after an extended move.
2. Check whether the Radar is BUILDING, WATCH or ARMED.
3. Compare Bull Pressure and Bear Pressure, then confirm the Pressure Delta and Bias.
4. Treat ARMED as preparation, not confirmation.
5. Wait for a confirmed close beyond the relevant box boundary and confirmation buffer.
6. Use the breakout invalidation level together with your own risk-management process.
7. Confirm higher-timeframe structure, liquidity, market context and event risk before acting.
Important Notes
Breakout Radar does not predict that every compression will produce a successful breakout. Markets can generate false breaks, gaps, news-driven moves and rapid reversals. Pressure readings are analytical measurements derived from price behaviour; they are not exchange order-flow data.
The indicator does not provide profit targets or broker execution. This is intentional: Breakout Radar focuses on identifying compression, directional pressure, breakout confirmation and subsequent validity.
Recommended Markets & Timeframes
The concept can be applied to liquid equities, indices, futures, forex, commodities and crypto. Because volatility characteristics differ by instrument and timeframe, users should validate the default settings on the market they trade. Lower timeframes generally produce more setups and more noise; higher timeframes generally produce fewer but broader structures.
Alerts
Breakout Radar supports alert conditions for bullish ARMED, bearish ARMED, bullish breakout confirmation and bearish breakout confirmation. For live use, traders should configure TradingView alerts according to their preferred symbol, timeframe and confirmation workflow.
TradingView-Ready Short Description
Breakout Radar (TechnoBlooms) is a structure-first compression and breakout-pressure indicator designed to identify when a quiet market may be preparing for expansion. It combines volatility compression, locked price structures, Bull/Bear Pressure, Pressure Delta and directional Bias with progressive SCANNING → BUILDING → WATCH → ARMED states. Breakouts are confirmed only after price closes beyond the locked structure with an ATR-based buffer. The latest breakout signal remains visible while structurally valid, while completed compression boxes provide clean historical context. Breakout Radar is designed as a decision-support and market-structure tool rather than a standalone buy/sell system.
Disclaimer
For educational and analytical purposes only. This indicator does not constitute investment advice, a recommendation, or a guarantee of future performance. Trading and investing involve risk. Users should perform their own analysis and apply appropriate risk management before making trading decisions.
Индикатор

IQR Risk-to-Reward & Dynamic Targets [MantisAlgo]IQR Risk-to-Reward & Dynamic Targets combines empirical quartile statistics with structural liquidity analysis to identify setups with favorable market-derived risk-to-reward. Instead of assigning arbitrary profit targets such as fixed 2× risk multiples, the indicator divides recent price action into Q1 (25th percentile), Q2 (Median), and Q3 (75th percentile), together with 1.5×IQR statistical outlier boundaries.
These statistical value zones are combined with opposing swing liquidity to calculate the available True Risk-to-Reward Ratio before a setup is displayed. Each qualified setup automatically projects Entry, Structural Stop Loss, Take Profit 1, Take Profit 2, and the resulting True R:R directly on the chart.
🟢 IQR FAIR VALUE STRUCTURE
The Interquartile Range represents the middle 50% of the recent price distribution:
IQR = Q3 − Q1
Q1 = 25th Percentile
Q2 = 50th Percentile (Median)
Q3 = 75th Percentile
When price remains primarily between Q1 and Q3, the market is trading inside its recent statistical value region and tends to rotate around the Median. When price extends beyond an outer quartile or IQR outlier region and subsequently reclaims the Median Wave, the indicator evaluates whether sufficient structural space exists for a move toward opposing liquidity.
This creates two broad market conditions:
• Equilibrium / Mean-Reversion — Price remains within the Q1–Q3 value region and rotates around the Median.
• Expansion / Reclaim — Price extends outside statistical value, then reclaims the Median with sufficient space toward opposing liquidity.
🟢 SIGNALS & TRUE R:R GATE
The core trigger follows a simple sweep-and-reclaim sequence.
For a Long setup, price must first sweep or touch the Lower IQR Band within the recent bars. The signal is then evaluated when price crosses back above the Median Wave and the reclaim candle closes above it.
For a Short setup, price must first sweep or touch the Upper IQR Band. The signal is evaluated when price subsequently crosses back below the Median Wave and the reclaim candle closes below it.
Long: Lower Band Sweep → Median Reclaim → Confirmed Close
Short: Upper Band Sweep → Median Reclaim → Confirmed Close
The reclaim candle becomes the Entry only when volume is sufficiently active, the signal cooldown has been satisfied, and the available True R:R meets or exceeds the selected minimum threshold.
True R:R = Target Distance / Invalidation Distance
Target Distance = |TP2 − Entry|
Invalidation Distance = |Entry − SL|
If True R:R is below the selected threshold, the setup is suppressed. If it meets or exceeds the threshold, the trigger triangle and complete Entry / SL / TP1 / TP2 structure are displayed.
🟢 DYNAMIC TARGET STRUCTURE
Each qualified setup contains four objective levels:
Entry — The exact closing price of the confirmed trigger candle.
Stop Loss — The structural extreme associated with the preceding sweep. For Long setups, the relevant sweep low is used; for Short setups, the relevant sweep high is used. A break beyond this level invalidates the setup structure.
Take Profit 1 — TP1 is based on the opposing quartile boundary: Q3 for Long setups and Q1 for Short setups. It represents the first statistical mean-reversion objective.
Take Profit 2 — TP2 is based on opposing structural liquidity: swing-high liquidity for Long setups and swing-low liquidity for Short setups. Because TP2 is derived from actual chart structure rather than a predetermined fixed multiple, the resulting True R:R changes naturally from setup to setup.
🟢 IQR OUTLIER FENCES
The indicator also calculates traditional Box Plot outlier boundaries:
Lower Fence = Q1 − (1.5 × IQR)
Upper Fence = Q3 + (1.5 × IQR)
These boundaries identify price observations that are unusually extended relative to the recent rolling distribution and provide additional context for statistical sweeps.
🟢 DYNAMIC MEDIAN WAVE
The central Median Wave is based on Q2 and smoothed using a two-pole SuperSmoother-style digital filter. Its purpose is to reduce short-term noise while remaining responsive to directional changes. The wave changes visual state according to its directional slope and acts as the primary reclaim reference for potential setups.
🟢 STATISTICAL BOX-PLOT PIVOTS
Confirmed structural swing pivots can display compact Box Plot brackets directly on the chart. Each bracket visualizes the local Q1 Lower Quartile, Q2 Median, Q3 Upper Quartile, and IQR outlier boundaries, making it easier to compare structural turning points with the surrounding statistical distribution.
🟢 STATISTICAL HUD
The optional top-right HUD provides a compact summary of the current statistical and structural state, allowing users to review the active distribution, directional context, and setup information without manually inspecting every plotted level.
🟢 SETTINGS
Quartile Sample Window — 34: Controls the rolling observation window used to calculate Q1, Q2, and Q3.
Outlier Whisker Multiplier — 1.5: Controls the IQR multiplier used to define the statistical outlier fences.
Structural Liquidity Lookback — 20: Controls the search window used to identify opposing swing liquidity for TP2.
Minimum True R:R Ratio — 2.0: Defines the minimum required target distance relative to structural risk. Higher values produce fewer but more selective setups.
Signal Cooldown — 6: Controls the minimum separation between consecutive signals.
Visual Settings: Show IQR Fair Value Cloud, Show Statistical Box-Plot Pins, Show Signal Trigger Triangles, Show Target Projection Rays, Max Historical Setups to Display, and Show Statistical HUD Dashboard.
🟢 INTERPRETATION
The indicator combines three elements: Statistical Location, Structural Invalidation, and Available Target Space. It does not assume that every statistical extreme will reverse or that every liquidity target will be reached.
Instead, it evaluates whether a confirmed statistical reclaim has enough remaining structural space relative to its invalidation risk to satisfy the selected True R:R requirement. The goal is to make signal timing, structural risk, and available market space directly visible on the chart rather than attaching arbitrary target multiples after a signal appears.
🟢 DISCLAIMER
This indicator is designed for technical analysis, quantitative research, and educational purposes only. It does not constitute financial advice. Historical statistical relationships do not guarantee future outcomes. Always apply appropriate risk management and position sizing. Индикатор

Candle Club - Session LevelsYesterday's high, the overnight range and today's open, drawn where they formed and kept on the chart so you can see what price did there.
WHAT IT DRAWS
Prior day high, low and close; overnight high and low; the cash-session open; an optional prior-day midline and round-number reference lines; and shelf zones, shaded pockets where recent session highs and lows cluster. Each day's lines start when that level becomes known and stop when the next one replaces it, so history stays readable.
THE IDEA
A session extreme is a place the market reached and turned away from; the overnight range is the path it took while the cash session was shut. Many traders watch these places, and this tool's only job is to put them on your chart where you can see them. It makes no claim about what price does when it returns there; what you do at a level is your call.
WHAT IS ORIGINAL
Shelf zones. The script banks each completed session's high and low, sorts the last few days of them, and groups any within your chosen width of each other. Two or more in one pocket become a box starting where its oldest member formed. One extreme is a number; a cluster is a shelf the market has revisited.
HOW TO USE
Set the cash session and timezone for your market (default: US index futures and stocks) and how many days to keep. Read it top down: the table lists every level and how far it sits from the last price, so you can see at a glance what is above and below you. Shaded boxes are shelf zones - the more session extremes stacked in one, the more times the market has stopped in that pocket. Set one alert per level, or the "any level" alert, to be told when price crosses one instead of watching. Best on 1-minute to 15-minute charts; it draws nothing on daily and above.
SETTINGS
One group per family: prior day, overnight, open, shelf zones, round lines, each with an on/off switch and colour on one row, then width and style. Neutral lines follow your chart theme. Prior day can use the exchange's daily bar or the previous cash session only.
LIMITATIONS
Intraday charts only. On stocks the overnight means the pre- and post-market bars on your chart, so extended hours must be on. The cash-session option needs one completed session first. Overnight here means everything outside the cash session you set, so if you also run a tool that starts its overnight at a fixed hour the two will not always draw the same line. The round-number lines are an evenly spaced grid, off by default. They are drawn for reference only and nothing here claims price behaves differently at them.
A standalone drawing tool with no buy or sell signals. Индикатор

Market Path Forecast [BOSWaves]Market Path Forecast - Swing-Calibrated Directional Forecast with Confidence Cone, Structure-Snapped Levels, and Adaptive Horizon
Overview
Market Path Forecast is a swing-calibrated probabilistic directional forecast system that derives its target price, forecast duration, and cone width entirely from the statistical properties of the instrument's own historical swing behavior, where the path cone, level placement, and forecast horizon all adapt continuously to the accumulated record of completed swings rather than applying fixed ATR multiples or arbitrary projection distances.
Instead of projecting fixed percentage moves or static ATR extensions, the system accumulates the percentage size and bar duration of each completed directional swing into weighted sample arrays, computes the weighted average and standard deviation of those samples, and uses these statistics to estimate where the current swing is likely to travel and how long it is likely to take. The resulting forecast is not a generic technical projection but a statistically calibrated estimate derived from the instrument's actual measured movement history.
This creates a forecast framework that is self-calibrating to each instrument and timeframe. Instruments with large consistent swings produce wide confident cones pointing to distant targets. Instruments with small erratic swings produce narrower cones with closer targets. The confidence interval setting scales the cone width relative to the measured historical variance, allowing the trader to choose whether to view the tight central tendency or the broader probable range. Structure snap alignment pulls forecast levels toward nearby historical pivot prices, anchoring statistically derived targets to structurally significant levels. And the adaptive horizon dynamically adjusts the projection duration as the current swing develops, so the cone length reflects how much time is estimated to remain rather than a fixed number of bars.
Price is therefore evaluated against a forecast that reflects the instrument's own statistical swing personality rather than a generic overlay applied identically regardless of how the instrument actually moves.
Conceptual Framework
Market Path Forecast is founded on the principle that the most reliable basis for a directional price forecast is the statistical distribution of the instrument's own completed swing history, and that both the target level and the confidence around that target should derive from measured historical variance rather than from fixed indicator parameters.
Traditional forecast tools apply static extensions, fixed ATR projections, or Fibonacci ratios that carry no relationship to how the specific instrument actually moves. This framework replaces static projection with statistical estimation, accumulating a rolling weighted sample of historical swing sizes and durations and deriving forecast parameters from that sample on every bar. Recent swings receive greater weight than older ones, ensuring the forecast adapts dynamically to evolving market behavior while maintaining the stability that comes from a sufficient sample of historical evidence.
Three core principles guide the design:
Forecast targets, durations, and cone widths should derive from the statistical properties of the instrument's own swing history rather than from fixed parameters, ensuring every element of the projection reflects actual measured behavior rather than generic assumptions.
The confidence cone should scale with historical swing variance through a statistically meaningful confidence interval parameter, so traders understand they are viewing a fraction of the measured probability distribution rather than an arbitrary visual band.
Forecast levels should be snapped toward nearby historical structure prices where they exist within the configurable snap range, anchoring statistically derived targets to the structural price levels that may have influenced prior swing reversals.
This shifts directional forecasting from fixed-parameter projection into instrument-specific statistical estimation where all visual elements adapt to the instrument's own historical behavior.
Theoretical Foundation
The indicator combines swing detection through highest and lowest lookback comparison, recent-weighted average and standard deviation calculation across historical swing percentage moves and bar durations, directional forecast derivation from the appropriate bull or bear sample arrays, momentum-adjusted path curvature using EMA difference normalization, structure-snap level alignment using nearest historical pivot within the configurable ATR search radius, and historical support and resistance zone construction from separate pivot detection with age-based expiry and break detection.
Swing direction is tracked by monitoring whether the current highest or lowest lookback value is being set by the current high or low, with confirmed swing points registered when price rotates away from a prior extreme. Each completed directional leg contributes its percentage move and bar duration to separate bull and bear sample arrays using a weighted push that replaces oldest samples beyond the configured maximum. The weighted average applies linearly increasing weights from oldest to most recent, giving recent swings proportionally greater influence. Standard deviation is computed from the same weighted scheme, producing a variance measure that reflects recent behavior more than distant history. The forecast target is calculated as a percentage move from the swing origin, with the extension factor derived from the deviation ratio to scale the extension level beyond the primary target.
Four internal systems operate in tandem:
Swing History Engine : Detects confirmed swing direction changes, measures the percentage move and bar duration of each completed leg, and accumulates these into directional and combined weighted sample arrays that feed all downstream forecast calculations.
Statistical Forecast Engine : Derives weighted average target percentage and duration from the directional sample arrays, falls back to combined samples when directional sample count is insufficient, calculates the standard deviation for cone width scaling, and applies minimum spacing enforcement to prevent levels from overlapping.
Path and Level Rendering System : Constructs the three-layer confidence cone using eased smooth interpolation with momentum-derived curvature, and renders up to six forecast levels as three-layer box zones with structure-snapped prices, directional coloring, and configurable label display.
Historical Structure System : Independently detects pivot highs and lows at the configured structure pivot length, maintains active zone boxes with age-based fading and break detection, stores pivot prices in a rolling array that feeds the structure snap function for all forecast levels, and enforces maximum zone count and age limits.
This design ensures the forecast derives entirely from measured historical behavior while the structure snap layer connects statistically derived levels to structurally significant prices where they exist in proximity.
How It Works
Market Path Forecast evaluates price through a sequence of swing-calibrated and statistically derived processes:
Swing Direction Tracking : On each bar, the highest high and lowest low over the configured swing length are compared to the current bar. When the current high sets the lookback high, direction tracks bullish. When the current low sets the lookback low, direction tracks bearish. Confirmed swing points are registered when price rotates away from the prior extreme.
Swing Sample Accumulation : On each confirmed swing direction change, the completed leg's percentage move and bar duration are calculated and pushed into the appropriate directional and combined sample arrays with size capping at the configured maximum. Bull legs accumulate into the bull arrays and bear legs into the bear arrays.
Weighted Forecast Derivation : The weighted average of the directional sample array provides the forecast percentage move. The weighted average of the duration array provides the forecast bar count. The weighted standard deviation of the directional array provides the variance measure for cone scaling. When fewer than three directional samples exist, the combined arrays are used as fallback.
Adaptive Horizon Calculation : The estimated remaining bars for the current swing are calculated by subtracting elapsed bars from the estimated total duration and clamping to the configured minimum and maximum. When adaptive horizon is disabled, the fixed bar count is used instead.
Target Calculation : The primary target is derived from the swing origin price adjusted by the forecast percentage in the forecast direction, with a minimum distance floor enforced as an ATR multiple to prevent targets from forming too close to current price.
Level Derivation : Target 1, 2, and 3 are placed at 40, 70, and 100 percent of the base distance. The extension level is placed beyond Target 3 using a factor derived from the deviation-to-mean ratio. The opposite structure reference and invalidation level are placed on the opposing side of price.
Structure Snap Application : Each raw level price is tested against the rolling historical structure price array. If a matching structural high or low exists within the ATR snap range on the correct side of price, the level is blended toward that structural price by the configured snap strength.
Minimum Spacing Enforcement : After snapping, all levels are adjusted to maintain a minimum separation equal to twice the zone ATR width, preventing levels from overlapping regardless of snap results.
Cone Construction : The base band half-width is derived from the greater of the ATR floor and the price-converted standard deviation, clamped to a maximum fraction of the distance to Target 3, then multiplied by the confidence interval setting. Smooth eased interpolation builds the outer, inner, and center polyline paths between current price and the Target 3 level with momentum-derived curvature applied.
Historical Structure Zone Management : Pivot highs and lows detected at the structure pivot length receive dual-layer zone boxes that extend rightward each bar, fade with cubic age scaling, convert to dotted broken style when price closes through them, and expire after the configured maximum age or break age.
Together, these elements form a continuously updating forecast system where every visual element adapts to the instrument's measured swing history and structural price environment.
Interpretation
Market Path Forecast should be interpreted as a statistically calibrated swing forecast with a probabilistic confidence cone and structure-aligned target levels:
Forecast Path Cone : The three-layer cone extending from current price represents the probable range of price paths based on historical swing behavior. The outer layer covers the full confidence interval width. The inner layer covers approximately 55 percent of the cone width. The center line represents the weighted average expected path.
Cone Width : A wide cone indicates high historical swing variance where completed swings varied significantly in size. A narrow cone indicates consistent swing behavior with low variance. The confidence interval setting controls how many standard deviations of historical variance the cone spans.
Cone Curvature : The cone bends in the direction of current EMA momentum, reflecting whether the trend currently has upside or downside momentum bias that may influence the directional path of the developing swing.
Target 1, 2, 3 Levels : Three-layer zone boxes at progressively greater distances represent the expected first, intermediate, and primary swing completion levels derived from the weighted average of historical swings at 40, 70, and 100 percent of the base distance.
Extension Level : Beyond Target 3, the extension level marks where larger-than-average swings have historically reached, scaled by the ratio of standard deviation to mean swing size. A larger extension factor indicates that historical swings have been more variable and have occasionally traveled significantly beyond average.
Support / Resistance Level : The opposing-direction level on the near side of price identifies the closest structural reference in the opposing direction, representing the level where a counter-swing could develop before the forecast target is reached.
Invalidation Level : The furthest opposing level marks the price beyond which the current swing forecast would be statistically invalidated, representing the distance at which counter-directional movement exceeds what is consistent with the current swing remaining intact.
Historical Structure Zones : Green support zones and red resistance zones from historical pivot detection provide the structural price environment that both informs the forecast level snap function and serves as ongoing structural reference for price interaction monitoring.
Broken Structure Zones : Zones that have been closed through convert to dotted style with faded coloring, indicating the former level has been breached and may now function in the opposing structural role.
Cone width, target level placement, snap alignment to structure, and invalidation level distance collectively provide more forecast context than any element in isolation.
Signal Logic & Visual Cues
Market Path Forecast generates two directional signals tied to swing direction changes:
Bullish Forecast : Triggered when swing direction flips from bearish to bullish, resetting the forecast origin to the confirmed swing low and projecting the cone and levels upward toward the statistically estimated bull swing targets.
Bearish Forecast : Triggered when swing direction flips from bullish to bearish, resetting the forecast origin to the confirmed swing high and projecting the cone and levels downward toward the statistically estimated bear swing targets.
Each forecast reset incorporates the newly completed swing into the weighted sample arrays before generating the next projection, ensuring every forecast benefits from the most recent available behavioral evidence.
Alert generation covers bullish and bearish forecast direction changes for systematic swing-based monitoring workflows.
Strategy Integration
Market Path Forecast fits within swing-calibrated directional and statistical target-based trading approaches:
Target-Based Exit Planning : Use the three forecast target levels as a staged exit framework, planning partial position reductions at T1, T2, and T3 rather than targeting a single fixed level, allowing structured progression through the statistically estimated swing completion zone.
Cone Containment Monitoring : Monitor whether price is staying within the inner confidence cone or pressing against the outer boundaries as a real-time swing health indicator. Price persistently hugging the outer cone boundary in the forecast direction suggests above-average momentum. Price compressing toward the center early in the forecast suggests weakening follow-through.
Extension Level Context : Use the extension level as a target for high-momentum setups where the deviation-to-mean ratio is elevated, indicating that historical swings have occasionally extended significantly beyond the average. A larger gap between T3 and the extension level reflects greater historical variability.
Invalidation Level Risk Management : Use the invalidation level as the maximum tolerable counter-directional excursion, beyond which the current swing forecast is no longer statistically consistent with historical behavior and the position rationale is undermined.
Structure Snap Confluence : Prioritize levels that have been snapped to nearby structural pivot prices over purely statistically derived levels, as these represent locations where both the measured swing expectation and historical price structure align simultaneously.
Confidence Interval Calibration : Use a lower confidence interval such as 0.5 for tight conviction analysis where you want to see only the central tendency of the forecast. Use 1.5 or 2.0 to visualize the broader probability range that captures less typical swing outcomes.
Technical Implementation Details
Swing Detection : Highest and lowest lookback comparison with direction tracking and confirmed point registration on price rotation
Sample Arrays : Weighted push accumulation for bull, bear, and combined percentage and duration arrays with configurable maximum size
Forecast Statistics : Linearly increasing weight scheme for weighted average and standard deviation with directional to combined fallback below minimum sample threshold
Cone Construction : Eased smooth interpolation with momentum-normalized EMA curvature across configurable step count for outer, inner, and center polyline paths
Level System : Six forecast levels with percentage-of-base-distance placement, deviation-ratio extension scaling, structure snap blending, minimum spacing enforcement, and three-layer zone box rendering
Structure System : Pivot-based zone detection with dual-layer boxes, rolling structure price array for snap function, cubic age fading, break detection with style conversion, and configurable zone count and age limits
Performance Profile : Last-bar rendering with full polyline and object rebuild each update, configurable level count for object management
Optimal Application Parameters
Timeframe Guidance:
1 - 5 min : Intraday swing forecasting with shorter swing length and fewer historical swings for fast adaptation to intraday directional changes
15 - 60 min : Session-level swing projection with balanced swing length and moderate sample count for meaningful statistical accumulation across typical session swings
4H - Daily : Swing-level directional forecasting with longer swing detection and larger sample count for statistically robust estimates derived from significant structural moves
Suggested Baseline Configuration:
Swing Length : 16
Historical Swings : 20
Volatility Length : 200
Adaptive Forecast Horizon : Enabled
Confidence Interval (SD) : 1.0
Path Curvature : 0.45
Number of Levels : 6
Structure Snap Strength : 0.65
Show Historical Structure : Enabled
Show Forecast Path : Enabled
Show Forecast Levels : Enabled
These suggested parameters should be used as a baseline; their effectiveness depends on the instrument's swing frequency, historical swing consistency, and preferred forecast horizon, so fine-tuning is expected for optimal performance.
Parameter Calibration Notes
Use the following adjustments to refine behavior without altering the core logic:
Forecast targets too close to price : Decrease Minimum Target Distance toward 1.0 to allow targets to form closer to price, or increase Historical Swings to accumulate more samples that may include larger average moves.
Forecast targets too far from price : Increase Minimum Target Distance to enforce greater separation, or decrease Historical Swings to weight more recent and potentially smaller swing samples more heavily.
Cone too wide or too narrow : Adjust Confidence Interval to expand or contract the cone relative to the measured standard deviation of historical swings, using 0.5 for a tight central tendency view or 2.0 for a broad probability range.
Forecast flipping too frequently : Increase Swing Length to require more bars on each side of a confirmed swing extreme, filtering shorter-term oscillations from the swing detection.
Forecast too slow to update : Decrease Swing Length toward 6 for faster swing confirmation, or decrease Historical Swings to allow the weighted average to adapt more quickly to recent behavior changes.
Levels not snapping to structure : Increase Structure Snap Range to widen the ATR distance within which structural pivot prices attract forecast levels, or increase Structure Snap Strength toward 1.0 for stronger magnetic pull toward nearby structure.
Too many historical structure zones : Reduce Maximum Zones to limit visible structural zones, or decrease Maximum Zone Age to expire older zones sooner and keep the chart focused on more recent structural history.
Adjustments should be incremental and evaluated across multiple session types rather than isolated market conditions.
Performance Characteristics
High Effectiveness:
Instruments with consistent swing behavior where historical percentage moves and durations cluster tightly, producing low variance forecasts with narrow confident cones that accurately reflect the instrument's typical directional tendency
Trending markets where completed swings accumulate rapidly and the weighted sample arrays update frequently, keeping the forecast calibrated to current momentum characteristics
Swing-based trading approaches where statistically derived target levels replace arbitrary Fibonacci or ATR projections with instrument-specific measurements of where swings have historically terminated
Structure-rich instruments where the snap function can align statistically derived levels with meaningful historical pivot prices, creating confluence between statistical expectation and structural significance
Reduced Effectiveness:
Instruments with highly erratic swing behavior where percentage moves vary widely between legs, producing large standard deviations and wide uncertain cones that reduce the specificity of target level placement
Range-bound or choppy markets where swing detection fires frequently on minor oscillations, populating the sample arrays with small inconsistent measurements that undermine forecast reliability
Instruments with insufficient completed swings within the sample window where the fallback to combined arrays may produce forecasts that blend bull and bear statistical properties inappropriately
Very short timeframes where completed swings are so numerous and small that the weighted average converges on noise-level movements without statistical significance
Markets undergoing structural regime changes where historical swing statistics are no longer representative of current behavior, making the weighted average a poor estimate of future swing potential until sufficient new samples accumulate
Integration Guidelines
Confluence : Combine with BOSWaves structural tools, volume analysis, or momentum indicators to validate forecast direction and target level interactions with broader analytical context before committing to swing-based trade plans
Sample Count Awareness : Monitor whether the forecast is drawing on directional or combined samples by assessing how many completed swings in the current direction exist within the historical window. Fewer than three directional samples means the forecast is using combined statistics that blend both directions.
Cone Evolution Monitoring : Track cone width changes across successive forecast resets as a volatility regime indicator. Progressively widening cones across multiple swings suggest increasing swing size variability. Narrowing cones suggest the instrument is entering a more consistent swing rhythm.
Structure Snap Validation : When a level snaps significantly from its raw statistical position to a nearby structural pivot, treat the snapped level with elevated confidence as it represents simultaneous statistical expectation and structural significance.
Invalidation Discipline : Respect the invalidation level as a hard position management boundary. A close beyond the invalidation level indicates counter-directional movement that exceeds the statistical parameters of the current forecast, warranting position reassessment regardless of other analytical factors.
Disclaimer
Market Path Forecast is a professional-grade swing-calibrated statistical forecast and structural analysis tool. It uses weighted historical swing statistics with confidence interval scaling and structure snap alignment but does not predict future price movements with certainty. All forecasts represent statistical estimates based on historical behavior and carry inherent uncertainty that increases with forecast horizon. Results depend on market conditions, instrument swing consistency, parameter selection, and disciplined execution. BOSWaves recommends deploying this indicator within a broader analytical framework that incorporates order flow context, structural analysis, and comprehensive risk management. Индикатор

Session Open LineA price overlay for TradingView (Pine Script v6). A horizontal line at the session's reference level - the previous session's close by default, or the session open - drawn from the first to the last bar of that session, with a label carrying the price change during the session (close vs the reference) - as a percent, as a difference in the instrument currency, or both. Alerts fire when the price crosses the line, and the reference level plus the session change are exposed as hidden series for other scripts.
█ 🧠 WHAT IT SHOWS
For every trading session the script anchors a line at the session's reference level and stretches it to the right as the session progresses:
price
│ ╭─╮
│ reference level │ │ ╭╮ ← price above the reference
│ ╭╮ ╭╮ ╰─╯ ││
│ ══╪╪═══════════════════╪╪═══════╪╪══ ─►
│ ╰╯ ╭╮ ╭╮ ╰╯ ╰╯
│ ╰╯ ╰╯ ← price below the reference
│
│ ├──────── one session ────────┤├── next session ──
└────────────────────────────────────────────── time
The line sits at the reference level - the previous session's close (default) or the session open - and never moves vertically.
Its right end follows the current bar until the session ends.
The color of the line depends on the sign of the change : up color when close >= reference level , down color otherwise. It is re-evaluated on every bar, so a session that flips from green to red repaints the whole line.
The whole session is shaded in the same up/down color (on by default, can be turned off).
Reference level
Previous session close (default) - the close of the last bar of the prior session. The change matches the day change quoted against the previous close (the way most quote screens report it), and an opening gap shows up as the distance between the line and the session's first candle.
Session open - the open of the first bar of the session. The change measures only what happened inside the session; there is never a gap between the line and the first candle.
Session detection
A new session is detected with timeframe.change('D') - the trading day boundary as TradingView defines it for the symbol. That is deliberately not "midnight": it follows the instrument's own session definition, so futures sessions that cross midnight are handled correctly (the line starts at the session boundary, not at 00:00).
Why a box, not bgcolor()
The session highlight is drawn as one box per session rather than bgcolor() . bgcolor() paints a single bar and cannot be repainted afterwards, so a session that flips sign would end up striped. A box spans the whole session and keeps a single color that is corrected on every bar. Box extend only works on the time axis, so the vertical coverage comes from the box bounds: the highest high and lowest low of the loaded data, padded by 100x that range above and below. On the last bar every box is brought to the final bounds, so sessions drawn while less data was loaded get the same coverage.
Why not simply 1e17 / -1e17 : TradingView silently skips boxes whose bounds lie extremely far from the price scale (on an instrument near 85, bounds of +-1e8 still draw while +-1e9 do not). Such boxes exist - they show up in the object tree - but never render, so the highlight looks like it is not working at all.
█ 🏷️ THE CHANGE LABEL
The label is colored by the sign of the change and sits on a fully transparent background. Two checkboxes decide what it carries:
Show percent change (default on) - the change as a percent of the reference level, formatted as +0.84% / -1.12% (always signed, two decimals).
Show change in instrument currency (default off) - the change as a price difference ( close - reference level ), formatted with the symbol's tick precision ( format.mintick ) and suffixed with syminfo.currency , e.g. +12.50 USD . For symbols without a quote currency the suffix is omitted.
With both on the label reads +0.84% (+12.50 USD) ; with both off no label is drawn at all - only the line (and the optional highlight) remains. For a reference level at or below zero (possible on futures spreads) the percent is undefined - the label falls back to the price difference, and the up/down color always follows the sign of the difference, which stays meaningful at any price.
Percent position decides where it sits, and the choice applies the same way to completed sessions and to the ongoing one:
Behind the line (default) - anchored on its left edge ( label.style_label_left ), at the reference level, right of the line end, as if continuing the line.
Above the line - anchored at its bottom-right corner ( label.style_label_lower_right ), so the text sits over the end of the line and does not stick out past the session end.
Below the line - anchored at its top-right corner ( label.style_label_upper_right ), so the text hangs under the end of the line, again inside the session.
During the ongoing session the label follows the end of the line and updates on every bar; once the session ends it stays at the last bar with the final value.
█ 🛠️ KEY PARAMETERS
General
Reference level (default Previous session close) - Previous session close / Session open, described above.
Show percent change (default on) - percent of the reference level in the label.
Show change in instrument currency (default off) - price difference in the instrument currency in the label.
Appearance
Up color (default #26A69A ) - line and label color when the session is up.
Down color (default #EF5350 ) - line and label color when the session is down.
Line style (default Solid) - Solid / Dashed / Dotted.
Line width (default 1) - range 1 - 4 .
Text size (default Small) - Auto / Tiny / Small / Normal / Large.
Percent position (default Behind the line) - Above the line / Below the line / Behind the line, described above.
Session highlight
Highlight the whole session (default on) - fills the entire session with a single color, decided by where the price stands against the reference level.
Highlight up color (default #26A69A at 90% transparency) .
Highlight down color (default #EF5350 at 90% transparency) .
█ 📈 HOW TO READ IT
The line is a reference level, not a signal. Trading above it means buyers have controlled the day so far; below it, sellers have.
Reclaims and rejections at the line are the interesting part - price returning to the level and being pushed away often marks who is defending the day.
With the previous-session-close reference (default) the line doubles as the gap-fill level : a session that opens with a gap and later crosses the line has closed that gap.
The label value gives an instant sense of the session's magnitude without measuring anything by hand, and the sign color makes a flip visible at a glance. The percent is comparable across instruments; the currency difference maps directly to points or ticks on the symbol you trade.
With the session highlight on , a screen full of alternating green and red blocks makes runs of consecutive up or down sessions obvious.
█ 🔔 ALERTS
Cross above the reference level - the price crossed the current session's line from below.
Cross below the reference level - the price crossed the current session's line from above.
Those are exactly the reclaim/rejection moments described above (with the default reference: the gap-fill / day-flip moments). The first bar of a session - where the line jumps to the new reference - never fires either alert. Crosses are evaluated on close , so on the live candle a cross can appear and un-cross before the candle closes; set the alert trigger to Once Per Bar Close if you only want confirmed crosses.
█ 📤 HIDDEN SERIES
The script exposes two hidden series, visible in the Data Window and usable as an external source in other indicators and strategies (any input.source field):
Reference level - the level the line sits at: the previous session's close (default) or the session open.
Session change % - the session change as a percent of the reference level.
█ ⛔ LIMITATIONS
Intraday timeframes only. On D and above every bar is its own session, so the script draws nothing and instead shows a hint table in the top-right corner: Session Open Line: the indicator works on intraday timeframes .
Drawing objects are capped at 500 lines, 500 labels, and 500 boxes - older sessions drop off the left side of the chart.
Both values are computed from close against the reference level, so during the ongoing session they move with every tick and only become final at the session close.
The first session in the loaded history starts at the first loaded bar, which is not necessarily the true session start. With the default reference (previous session close) it has no prior close at all, so it draws nothing; with the session-open reference its "open" (and therefore its change) can be off. Every later session is exact.
© Piotr Kowalski "piecioshka". License: Mozilla Public License 2.0. Индикатор

VWAP AI - Statistical Bands & Touch Stats [Dots3Red]⚓ VWAP AI - STATISTICAL BANDS & TOUCH STATS
VWAP's standard deviation bands are treated more or less as reliable support and resistance — on faith. This script checks that faith against the actual chart in front of you: every band touch is graded, every break beyond a band is graded, and the results accumulate into a running, honest record.
✨ WHY THIS MATTERS
VWAP tells you the volume-weighted average price — where the "center of gravity" of trading has actually been. The bands around it are meant to show how far price typically wanders from that center before snapping back. But "typically" varies enormously by instrument, session, and market condition, and no plain VWAP tool tells you what's actually been happening on your chart.
This script tracks it directly:
📊 +1σ | 62% rejected (n=41)
That means 41 touches of the +1σ band have been recorded on this chart, and 62% of them resulted in price genuinely rejecting back toward VWAP. Measured history, not an assumption baked into the tool.
⚙️ HOW IT WORKS
⚓ Anchoring — VWAP resets at the start of each new period. Session is the classic intraday default; Week and Month extend the same logic to longer views. Custom Bar anchors once, permanently, to a specific historical point you choose — useful for anchoring to an earnings date, a gap, or any event you want to measure from, rather than the calendar.
📏 Two-tier statistical bands — Band 1 and Band 2 are both standard-deviation multiples of VWAP, computed from a proper running variance (not an ATR approximation). Defaults are ±1σ and ±2σ, both fully adjustable.
🎯 Touch grading — when price wicks into a band without closing beyond it, that's logged as a touch. Within a configurable window, it resolves as:
• Rejection — price moved back toward VWAP by a meaningful distance
• Break — price closed convincingly through the band
• Timeout — neither happened clearly enough to call
🔄 Break-to-reversion tracking — separately, when price actually closes beyond Band 1, the script watches whether that move reverts back toward VWAP or continues away from it. This answers a different question than touch grading: not "did the band hold," but "once it didn't, did price come back anyway?"
🔒 Non-repainting — all grading happens strictly on confirmed bars.
🧭 HOW TO USE
1️⃣ Check the band stats before treating a level as reliable. "+1σ: 71% rejected (n=38)" and "+1σ: 44% rejected (n=12)" look like the same line on the chart but mean very different things about how much to lean on it.
2️⃣ Use break-reversion stats to judge a breakout beyond VWAP's range. If breaks above Band 1 have reverted back 65% of the time on this chart, that's useful context before assuming a fresh breakout will keep running.
3️⃣ Read Price vs VWAP as the simplest possible bias check. Above VWAP means the average buyer today is in profit; below means the average buyer is underwater. It's a blunt but genuinely useful read on crowd positioning.
4️⃣ Let sample sizes build before trusting the percentages. Every stat shows its N= specifically so you can judge reliability yourself — a handful of touches is not yet a pattern.
5️⃣ Match the anchor mode to what you're actually measuring. Session for pure intraday structure, Week or Month for a longer view, Custom Bar when you want to measure from one specific moment forward.
⏱️ WHICH TIMEFRAMES WORK BEST
Session-anchored VWAP is fundamentally an intraday tool — it was built for, and is most meaningful on, timeframes where a full session contains enough bars to form a real distribution: 1-minute through 1-hour is the classic and most effective range, which is exactly where VWAP sees the heaviest institutional and day-trading use.
On daily or weekly charts, a Session anchor resets so frequently relative to the bar size that it stops being meaningful — you'd see very few bars per session. For higher-timeframe or swing-style use, switch the anchor to Week, Month, or Custom Bar instead, so the accumulation window actually spans enough bars to produce a meaningful VWAP and band structure.
The touch and break statistics also need enough occurrences to mean anything — a fast-moving intraday chart will accumulate a useful sample size in days; a slow higher-timeframe anchor will take considerably longer.
🛠️ SETTINGS
⚓ Anchoring — Session / Week / Month / Custom Bar, source price
📏 Bands — Band 1 and Band 2 standard-deviation multipliers, Band 2 visibility toggle
🎯 Touch Statistics — Touch Tolerance, Rejection Distance, Reversion Distance, Outcome Window
🎨 Visualization — independent Band 1 / Band 2 touch marker toggles, Dot or Triangle marker style, marker size, VWAP and band line widths, independent fill transparency per band tier
🎨 Colors — VWAP line, Band 1 lines, Band 2 lines, upper/lower touch markers, Price Above/Below VWAP indicator, and full dashboard color control (background, border, header, row styling)
🖥️ Dashboard — show/hide, position — current VWAP value, price position, all four band stats, and both break-reversion stats in one place
📝 NOTES
Statistics accumulate from when the indicator is added to the chart and reset only when explicitly cleared by reloading. A Custom Bar anchor never resets on its own, it measures continuously from the point you chose. Band 2 statistics take meaningfully longer to build a useful sample than Band 1, simply because price reaches ±2σ far less often than ±1σ.
⚠️ DISCLAIMER
This is an analytical and visualization tool. It does not generate trade signals and does not constitute financial advice. Historical rejection and reversion rates do not guarantee future performance. Индикатор

Risk-Sizing CalculatorA simple, visual position-sizing tool for any market or timeframe.
Enter your account size and risk percentage, choose a stop-distance
method (ATR-based, manual stop price, or fixed % of entry), and the
indicator calculates your position size, stop distance, dollar risk,
notional exposure, and an optional reward-to-risk target — displayed
in a clean live table with entry and stop lines on your chart.
Also includes a 3-scenario Size Ladder (0.5% / 1% / 2% account risk
side-by-side) so you can see the sizing range at a glance, plus an
optional Market Context panel showing ATR %, RSI, ADX, volatility
class, and session state.
FEATURES
- Three stop-distance methods: ATR-based, Manual Stop Price, Fixed %
- Position size in units, notional dollars, and % of account
- Size Ladder table showing what 0.5% / 1% / 2% risk each produce
- Reward-to-risk target row (optional · pairs with an R multiple)
- Market Context panel: ATR %, RSI(14), ADX(14), volatility class,
session flag
- Live entry + stop + target lines drawn on the chart
- Adjustable table position (top-right, middle-right, etc.)
- Clean numeric output for quick pre-trade sanity check
HOW TO USE
1. Set Direction (Long / Short) and optionally a Manual Entry Price
2. Choose your Stop Distance method — ATR, manual price, or fixed %
3. Enter Account Size and Risk per trade % (1% is a common default)
4. Optional: enable target row and set R multiple
Pairs naturally with any ATR-based visualizer or manual entry planning.
Educational only · not financial advice · does not generate buy/sell signals. Индикатор

ATR Stop & Target VisualizerA simple, visual risk-planning tool for any market or timeframe.
Choose a direction (Long/Short) and the indicator plots an ATR-based
stop-loss, three reward-to-risk targets (TP1, TP2, TP3), shaded
risk / reward zones, and a live trade-plan table summarizing entry,
stop, targets, R:R math, ATR value, dollar risk, and a simplified
position-size estimate.
Also includes an optional Market Context panel showing ATR %, RSI,
ADX, volatility class, and session state — so the risk plan sits
alongside the environment reading you're planning against.
FEATURES
- ATR-based stop distance with selectable smoothing (RMA/SMA/EMA/WMA)
- Three reward-to-risk targets (TP1/TP2/TP3) with independent R
multiples · defaults 1R / 2R / 3R
- Layered shaded reward zones (densest at TP1, lightest at TP3)
- Auto or manual entry price
- Trade-plan table with all key numbers at a glance
- Simplified position-size estimate (account × risk %)
- Market Context panel: ATR %, RSI(14), ADX(14), volatility class,
session flag
- Clean single-bar drawing to keep charts readable
HOW TO USE
1. Set Direction (Long / Short) and optionally a Manual Entry Price
2. Tune the ATR length and stop multiple to fit the instrument's
volatility
3. Set each target as an R multiple (defaults 1R / 2R / 3R)
4. Enter account size and risk % to see a suggested position size
This is a visual risk-planning tool built to help traders think in
terms of risk first. Educational only · not financial advice · does
not generate buy/sell signals. Индикатор

Equal Highs & Lows [ITA]🟠 OVERVIEW
Equal Highs & Lows marks the places where liquidity pools build, and then
tracks what happens to them.
When two swing highs form at almost the same price, the stops of everyone who
sold that level sit just above it. The same is true in reverse below two equal
lows. Those clusters are what price often reaches for before it turns, and they
are visible on the chart long before anything happens to them.
Most tools that find these draw the two swings and stop there. This one keeps
the level alive until price actually takes it, then marks it as swept rather
than deleting it, so you can look back and see whether a symbol respects its
pools at all before you trade one.
🟠 CONCEPTS
* Equal Highs (EQH) - Two swing highs within a set tolerance of each other.
Stop orders rest above them.
* Equal Lows (EQL) - Two swing lows within tolerance. Stops rest below.
* Liquidity Pool - The cluster of resting orders those stops form. It is a
reason for price to travel somewhere, not a reason for it to reverse there.
* Sweep - Price trading through the level and taking the orders. What happens
immediately after the sweep is the part that matters.
🟠 FEATURES
🔹 Equality tolerance is set as a percentage of price rather than in points, so
the same setting behaves consistently on a five dollar stock and a seven hundred
dollar index
🔹 The level is drawn at the higher of the two equal highs, and the lower of the
two equal lows, because that is where the stops actually sit. Averaging the two
puts the line underneath the liquidity it is meant to mark
🔹 Levels extend forward on every bar until they are taken, so an untouched pool
stays visible for as long as it survives
🔹 Swept pools are greyed out and labelled instead of being removed, which
leaves a record of how the symbol has treated its pools historically
🔹 A cap on active pools, so old levels retire instead of filling the chart
🔹 Separate alerts for equal highs taken and equal lows taken
🟠 HOW TO USE
Start with the tolerance. It is the setting that decides everything else. On a
daily chart 0.1 to 0.3 percent is usually right. Intraday, drop it to 0.05 to
0.15. If you are seeing almost no pools, raise it. If everything is a pool,
lower it.
Read an unswept level as a destination, not a wall. Liquidity sitting above the
current price is a reason to expect price to reach up there at some point. It is
not a reason to short it.
The information is in what follows the sweep. Price taking equal highs and then
continuing up means the pool was simply passed through. Price taking them and
immediately failing back below is the sequence that traders are usually looking
for, and the sweep alert is there so you do not have to watch for it.
Swing Lookback controls how significant a swing has to be before it counts.
Raise it for fewer and more meaningful pools.
🟠 CONCLUSION
Equal highs and lows are easy to see once someone points at them and easy to
miss while a chart is moving. This marks them as they form, keeps them until
they are taken, and leaves the record behind. Индикатор