
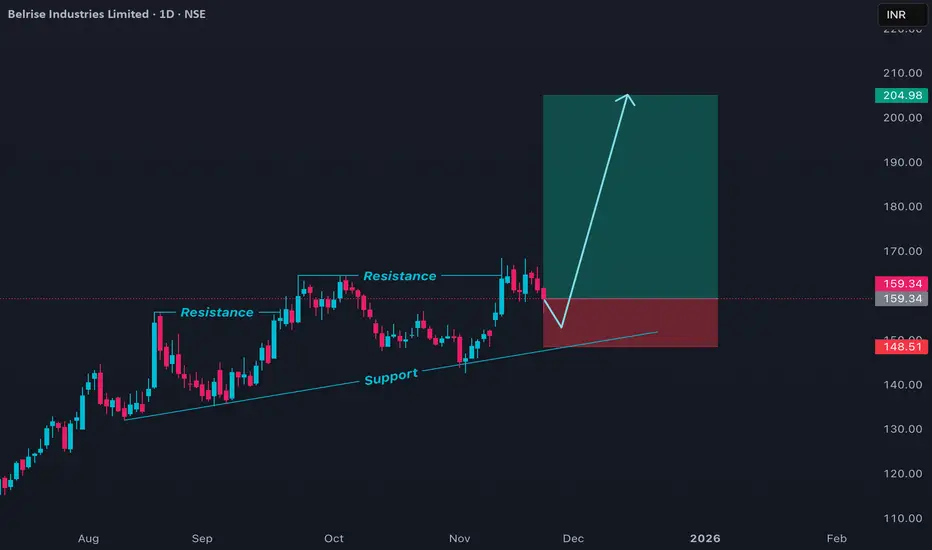
Short to Medium Term (6–12 months): Belrise looks attractive for a growth play, especially if it executes on its capacity expansion and leverages its OEM relationships.
Entry could be considered on a pull-back to strong support or on a breakout above key resistance (~₹ 180-185).
Initial downside risk is mitigated by its improving balance sheet, but growth execution needs to be monitored.
Long Term (3-5 years): If Belrise sustains its revenue growth, scales production, and builds strong profitability, it could become a significant auto-ancillary play — especially if EVs or structural auto demand expand.
Entry could be considered on a pull-back to strong support or on a breakout above key resistance (~₹ 180-185).
Initial downside risk is mitigated by its improving balance sheet, but growth execution needs to be monitored.
Long Term (3-5 years): If Belrise sustains its revenue growth, scales production, and builds strong profitability, it could become a significant auto-ancillary play — especially if EVs or structural auto demand expand.

คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน