
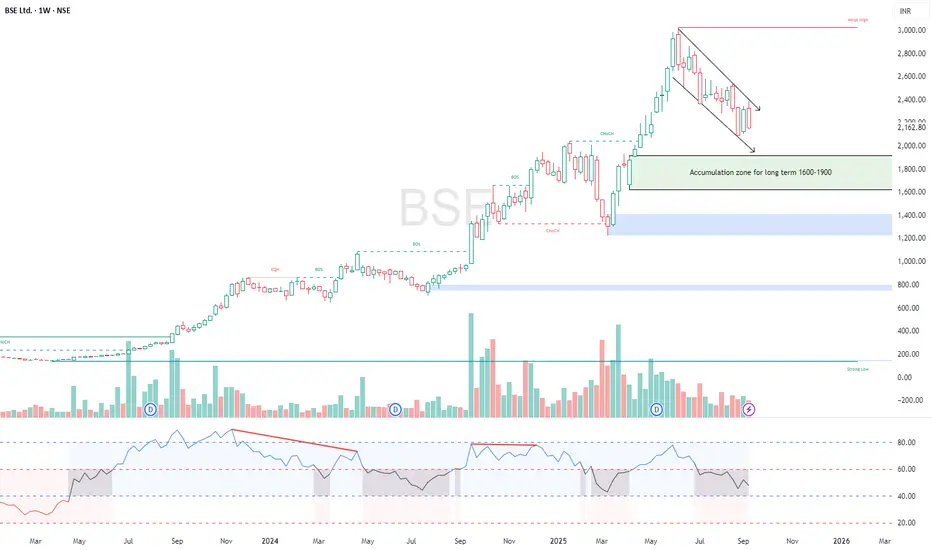
🔎 Technical View
Price: ₹2,162 (down ~6.7% this week).
Trend: Stock topped near ₹3,000, now consolidating inside a downward channel.
Support Levels:
Immediate: ₹2,000–2,100 (holding for now).
Major Accumulation Zone: ₹1,600–1,900 (highlighted on chart).
Strong structural support: ₹1,200.
Resistance Levels:
Short-term: ₹2,400–2,500 (channel top).
Medium-term: ₹2,800–3,000 (previous peak).
Interpretation: Stock is in corrective phase but long-term structure remains intact. Best risk-reward lies in accumulating between ₹1,600–1,900.
📊 Fundamental View
Business Strengths:
Monopoly-like status in equity cash segment; growing dominance in derivatives after contract redesign.
Strong network effect (volumes bring liquidity → liquidity attracts volumes).
Healthy balance sheet, cash-rich, zero debt.
Revenue visibility from transaction charges, listing, data, and annual fees.
Triggers Ahead:
Increasing derivatives volumes (BSE Sensex contracts gaining popularity).
Growth in SME and mutual fund distribution platforms.
Regulatory easing or new product launches could unlock further growth.
Risks:
Heavily dependent on regulatory stance (SEBI).
NSE competition remains tough in derivatives.
Valuations are rich compared to global peers.
📝 Long-Term Investment View
Accumulation Zone: ₹1,600–1,900 (best entry for investors).
Upside Potential: If volumes sustain and product mix improves, stock can revisit ₹2,800–3,000+ in 2–3 years.
Investment Style: SIP-based staggered buying around 1,800–2,000 reduces timing risk.
Conclusion: Structurally strong franchise with high entry barriers → a core long-term portfolio stock, but wait for better entry levels (below 2,000 ideal).

คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน