
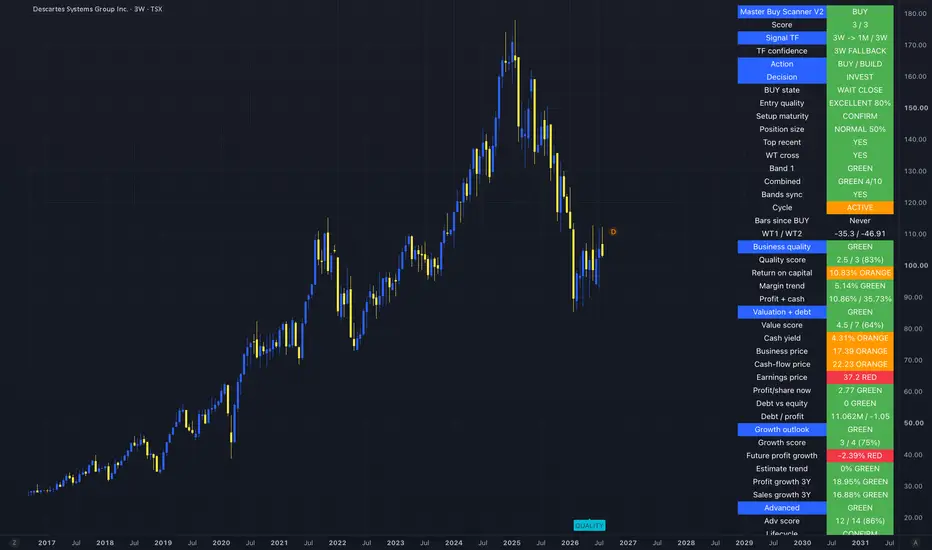
 DSG has fallen from roughly C$175 to around C$103, a drawdown of about 40% from its 2025 peak.
What makes Descartes Systems interesting here is that the share-price reset has happened while the underlying business continues to post record revenue, improving margins and strong cash generation.
The Master Buy Scanner V2 has now moved to a 3/3 BUY setup on the 3-week timeframe.
Master Buy Scanner V2 — 3 Week
Score: 3/3
Signal timeframe: 3W → 1M / 3W
Timeframe confidence: 3W FALLBACK
Action: BUY / BUILD
Decision: INVEST
BUY state: WAIT CLOSE
Entry quality: EXCELLENT — 80%
Setup maturity: CONFIRM
Position size: NORMAL 50%
Top recent: YES
WT cross: YES
Band 1: GREEN
Combined: GREEN 4/10
Bands synchronized: YES
Cycle: ACTIVE
WT1 / WT2: -35.32 / -46.91
This is already a fairly mature technical setup.
The WT cross has confirmed from deeply depressed levels, Band 1 is green and the bands are synchronized. The scanner therefore supports building a meaningful position.
The one limitation is the Combined reading at only 4/10, while the signal remains WAIT CLOSE.
So the reversal is developing, but I would still want the current 3-week candle to hold.
The business hasn't stopped compounding
Descartes reported record Q1 FY2027 revenue of $193.6M, +15% YoY.
Even more impressive:
Services revenue: +15%
Operating income: +35%
Net income: +34%
Diluted EPS: +34%
Operating cash flow: +40%
Adjusted EBITDA: +20%
Adjusted EBITDA margin reached 46%, while net income margin increased from 21% to 25%.
That is not a business deteriorating alongside its stock price.
93% recurring-like services revenue
One of the strongest parts of the Descartes model is its revenue mix.
In Q1, $180.5M of the $193.6M total revenue came from services, representing approximately 93% of revenue.
Descartes' Global Logistics Network sits inside highly operational workflows covering:
Transportation management
Customs and trade compliance
Last-mile delivery
Freight visibility
Routing
Carrier connectivity
Shipping and payment
Regulatory processes
These aren't typically products customers casually replace every year.
That embedded network structure is a major reason I view Descartes as more of a logistics infrastructure compounder than a conventional software company.
Margins are moving in the right direction
The scanner gives DSG:
Business quality: GREEN
Quality score: 2.5/3 — 83%
Return on capital: 10.83%
Margin trend: +5.14%
Cash-generation measure: 35.73%
The reported financials reinforce that margin improvement.
Gross margin increased from 76% in Q1 FY2026 to 78%, while adjusted EBITDA margin moved from 45% to 46%. Net income margin expanded four percentage points to 25%.
This matters because Descartes is not merely buying revenue through acquisitions.
Profitability is improving as the platform scales.
AI is being added to an already valuable data network
Descartes has an interesting AI angle because it already owns large amounts of operational logistics data.
Management explicitly describes the Global Logistics Network as providing the real-time data needed to power both existing operational systems and AI-powered solutions.
It is also acquiring AI capabilities rather than relying solely on internal development.
In April, Descartes acquired Idelic, an AI-powered driver safety and performance platform, for approximately $25.3M upfront plus potential earn-outs. Idelic adds predictive driver-risk intelligence to Descartes' routing and fleet-management capabilities.
Then in July, Descartes acquired Drivin for approximately $30M upfront, expanding its AI-powered last-mile capabilities and presence in Latin America.
The thesis here isn't that Descartes suddenly becomes an "AI stock."
It's more attractive than that:
AI can deepen the value of an existing logistics network that customers already depend on.
The balance sheet supports the acquisition machine
Descartes ended Q1 with $377M in cash after generating $75.1M of operating cash flow.
During the same quarter it spent roughly:
$29.7M on acquisitions
$20.8M repurchasing shares
Only $2.6M on property and equipment
And cash still increased by $20.5M.
That highlights the capital-light nature of the model.
Descartes can simultaneously:
grow organically + acquire niche software businesses + repurchase shares + accumulate cash.
The company has also authorized repurchases of up to roughly 10% of its public float under its current NCIB.
Valuation is better — but this still isn't deep value
The scanner gives valuation 4.5/7:
Cash yield: 4.31% — ORANGE
Business price: 17.39 — ORANGE
Cash-flow price: 22.23 — ORANGE
Earnings price: 37.17 — RED
Profit/share: 2.77 — GREEN
Debt/equity: 0 — GREEN
This is the main reason I wouldn't call DSG a bargain.
Even after a 40% correction, investors are still paying a premium for the combination of recurring revenue, margins, balance-sheet quality and long-term growth.
But that premium looks much more reasonable than it did near the highs.
Growth remains strong
The scanner gives DSG 3/4 on growth:
3Y profit growth: 18.95%
3Y sales growth: 16.88%
Future profit growth: -2.39%
Estimate trend: neutral
Fiscal 2026 provides additional context: revenue increased 12% to $729M, operating income grew 16%, EPS increased 14%, operating cash flow grew 21%, and adjusted EBITDA rose 16%.
Q1 FY2027 then accelerated from those already-solid numbers.
For me, the weaker forward-growth input is therefore something to monitor rather than evidence that the historical compounding engine has already stopped.
Key technical levels
Immediate support: C$100–103
Secondary support: C$90–95
Major support: C$85–90
First resistance: C$110–115
Recovery confirmation: C$120–125
Major resistance: C$135–145
Previous highs: C$170–175
The rebound from approximately C$87 has already started.
A successful 3-week close around current levels, followed by a reclaim of C$110–115, would make the setup considerably stronger.
My classification: COMPOUNDER BUY — BUILD ON CONFIRMATION
What attracts me to DSG is the combination:
3/3 scanner score
80% entry quality
Confirmed WT cross
Synchronized bands
93% services revenue
15% revenue growth
34% EPS growth
40% operating cash-flow growth
Expanding margins
Net-cash balance sheet
Disciplined acquisition strategy
Increasing AI exposure
The main limitation is valuation.
This isn't a distressed stock priced for failure. It's a high-quality compounder whose valuation has finally undergone a meaningful reset.
Current verdict: BUY / BUILD — 50% position, but I want the 3W close to confirm.
What would you do?
A) Start building around C$103
B) Wait for the 3W close
C) Wait for confirmation above C$115
Master Buy Scanner V2:

Not financial advice.

คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน