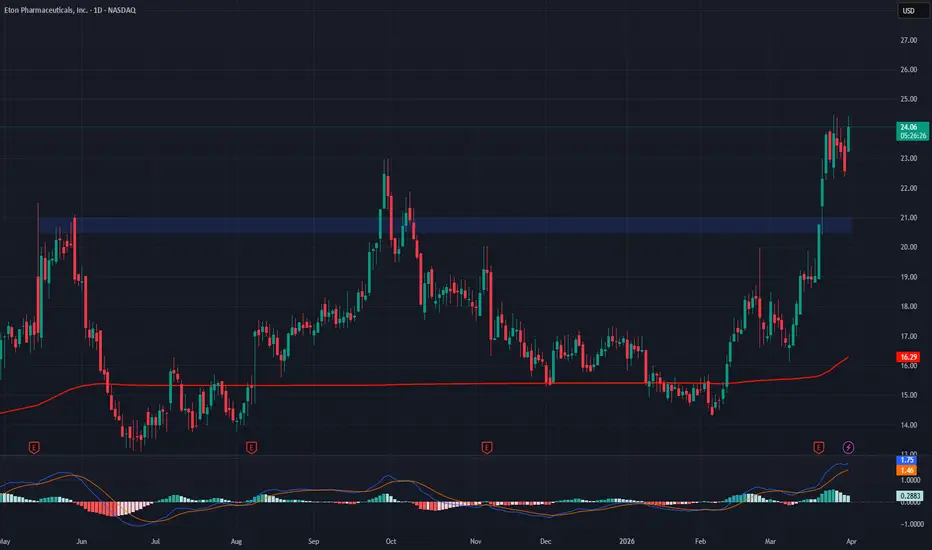
Eton Pharmaceuticals  ETON is a specialty pharma focused on rare disease treatments (notably pediatric and endocrine), offering exposure to high-margin orphan markets where pricing power and limited competition can drive outsized operating leverage.
Key Catalysts
Breakout Revenue Growth: Q4 2025 sales +83% YoY to $21.3M and full-year revenue more than doubled, reflecting strong execution on launches and niche indication expansion.
Portfolio Expansion Adds 2026 Fuel:
DESMODA (oral liquid desmopressin) launch expands the endocrine franchise.
HEMANGEOL acquisition strengthens the commercial base and adds a meaningful revenue contributor into 2026.
Profitability Inflection: 2026 guidance implies $110M+ revenue with 30%+ EBITDA margins, signaling powerful operating leverage as scale builds.
Orphan-Drug Playbook: Focused M&A in underserved rare diseases supports pricing durability, limited competitive pressure, and multiple near-term catalysts.
Investment Outlook
Bullish above: $20.50–$21.00
Upside target: $33.00–$34.00, driven by accelerating product sales, portfolio expansion, and margin expansion into 2026.
ETON is a specialty pharma focused on rare disease treatments (notably pediatric and endocrine), offering exposure to high-margin orphan markets where pricing power and limited competition can drive outsized operating leverage.Key Catalysts
Breakout Revenue Growth: Q4 2025 sales +83% YoY to $21.3M and full-year revenue more than doubled, reflecting strong execution on launches and niche indication expansion.
Portfolio Expansion Adds 2026 Fuel:
DESMODA (oral liquid desmopressin) launch expands the endocrine franchise.
HEMANGEOL acquisition strengthens the commercial base and adds a meaningful revenue contributor into 2026.
Profitability Inflection: 2026 guidance implies $110M+ revenue with 30%+ EBITDA margins, signaling powerful operating leverage as scale builds.
Orphan-Drug Playbook: Focused M&A in underserved rare diseases supports pricing durability, limited competitive pressure, and multiple near-term catalysts.
Investment Outlook
Bullish above: $20.50–$21.00
Upside target: $33.00–$34.00, driven by accelerating product sales, portfolio expansion, and margin expansion into 2026.

คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน