
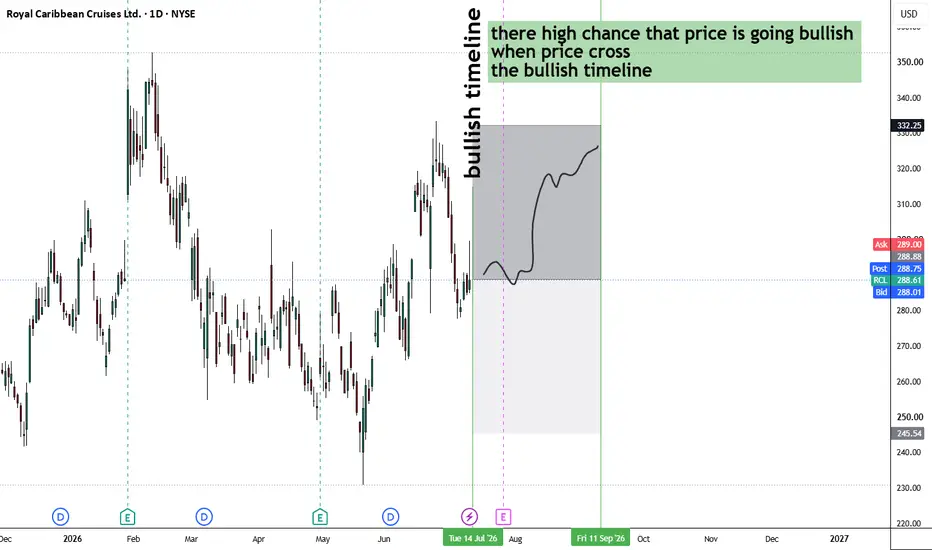
Bullish Analysis: Royal Caribbean Group (NYSE: RCL)
Royal Caribbean remains one of the strongest companies in the global travel and leisure sector. Despite macroeconomic concerns, the company continues to outperform peers thanks to exceptional demand, premium pricing, and industry-leading execution.
Why I'm Bullish
1. Record Booking Demand
Booking volumes remain at historically high levels.
Many 2026 sailings were booked well in advance at record prices.
Management has stated that demand recovered quickly even after temporary geopolitical disruptions.
2. Premium Pricing Power
Unlike many travel companies that compete on discounts, Royal Caribbean continues raising prices while maintaining strong occupancy.
This shows:
Strong brand loyalty
High consumer willingness to spend on experiences
Pricing power that supports expanding margins
3. Industry-Leading Fleet
Royal Caribbean's newest ships (Icon Class, Star of the Seas, Legend of the Seas) generate significantly higher onboard spending than older vessels.
New ships offer:
Higher ticket prices
Better fuel efficiency
More onboard revenue
Greater operating margins
This creates a long-term competitive advantage.
4. Strong Financial Momentum
Recent results showed:
Double-digit revenue growth
Earnings beating expectations
Management maintaining confidence in long-term growth despite higher fuel costs.
Continued shareholder returns through dividends and share repurchases.
5. Cruise Industry Tailwinds
Consumers continue prioritizing experiences over goods.
Key trends include:
Millennials becoming a larger share of cruise passengers
Growth in multigenerational family travel
Cruise vacations remaining attractive relative to land-based alternatives.
6. Growth Pipeline
Royal Caribbean continues expanding through:
New Icon-class ships
Exclusive beach clubs and private destinations
Expanded loyalty ecosystem
Additional ship orders extending growth into future years.
Risks
The bullish thesis isn't without risks:
Rising fuel prices can pressure margins.
Economic slowdowns may reduce discretionary travel spending.
Geopolitical events can temporarily affect itineraries and bookings.
The company still carries meaningful debt from the pandemic era, although leverage has been improving.
Investment Thesis
Royal Caribbean has evolved from a post-pandemic recovery story into a high-quality growth company. Strong demand, premium pricing, expanding onboard revenue, and continuous fleet innovation position it well for continued earnings growth. Analysts have also highlighted Royal Caribbean as one of the strongest operators in the cruise industry, expecting continued earnings expansion over the next several years.
Bullish Rating: 8.8/10
Long-term outlook: Bullish
Investment horizon: 12–36 months
The combination of resilient consumer demand, industry-leading execution, and a robust pipeline of new ships makes Royal Caribbean one of the more compelling growth opportunities in the travel sector.
Royal Caribbean remains one of the strongest companies in the global travel and leisure sector. Despite macroeconomic concerns, the company continues to outperform peers thanks to exceptional demand, premium pricing, and industry-leading execution.
Why I'm Bullish
1. Record Booking Demand
Booking volumes remain at historically high levels.
Many 2026 sailings were booked well in advance at record prices.
Management has stated that demand recovered quickly even after temporary geopolitical disruptions.
2. Premium Pricing Power
Unlike many travel companies that compete on discounts, Royal Caribbean continues raising prices while maintaining strong occupancy.
This shows:
Strong brand loyalty
High consumer willingness to spend on experiences
Pricing power that supports expanding margins
3. Industry-Leading Fleet
Royal Caribbean's newest ships (Icon Class, Star of the Seas, Legend of the Seas) generate significantly higher onboard spending than older vessels.
New ships offer:
Higher ticket prices
Better fuel efficiency
More onboard revenue
Greater operating margins
This creates a long-term competitive advantage.
4. Strong Financial Momentum
Recent results showed:
Double-digit revenue growth
Earnings beating expectations
Management maintaining confidence in long-term growth despite higher fuel costs.
Continued shareholder returns through dividends and share repurchases.
5. Cruise Industry Tailwinds
Consumers continue prioritizing experiences over goods.
Key trends include:
Millennials becoming a larger share of cruise passengers
Growth in multigenerational family travel
Cruise vacations remaining attractive relative to land-based alternatives.
6. Growth Pipeline
Royal Caribbean continues expanding through:
New Icon-class ships
Exclusive beach clubs and private destinations
Expanded loyalty ecosystem
Additional ship orders extending growth into future years.
Risks
The bullish thesis isn't without risks:
Rising fuel prices can pressure margins.
Economic slowdowns may reduce discretionary travel spending.
Geopolitical events can temporarily affect itineraries and bookings.
The company still carries meaningful debt from the pandemic era, although leverage has been improving.
Investment Thesis
Royal Caribbean has evolved from a post-pandemic recovery story into a high-quality growth company. Strong demand, premium pricing, expanding onboard revenue, and continuous fleet innovation position it well for continued earnings growth. Analysts have also highlighted Royal Caribbean as one of the strongest operators in the cruise industry, expecting continued earnings expansion over the next several years.
Bullish Rating: 8.8/10
Long-term outlook: Bullish
Investment horizon: 12–36 months
The combination of resilient consumer demand, industry-leading execution, and a robust pipeline of new ships makes Royal Caribbean one of the more compelling growth opportunities in the travel sector.
ปิดการเทรด: ถึงเป้าหมายการทำกำไร
Done 
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน