
I wanna talk about Uber!
I think this stock is attractive at this level. Here's my analysis.
My Uber thesis:
Scalable global marketplace (mobility + delivery) with very durable network effects, accelerating earnings, and high-conviction AV (autonomous vehicles) partnership upside. Uber is at a good valuation on misplaced AV disruption fears (in my view).
Fundamentals:
Economic Moat:
Powerful network effects, scale advantages, Uber One switching costs, and brand. Platform is the best aggregator for AV fleets.
Key Growth Drivers
Valuation & Intrinsic Value
Risks
AV companies going direct (mitigated by supply fragmentation); regulation/gig worker costs; macro slowdown; competition.
Sentiment
Strongly bullish among investors and on X: network + AV optionality seen as major tailwind; recent pullback viewed as buying opportunity.
What I'm doing
I'm allocating a bit above 1% of my portfolio into the stock.
Quick note: I'm just sharing my journey - not financial advice! 😊
- Henrique Centieiro
I think this stock is attractive at this level. Here's my analysis.
My Uber thesis:
Scalable global marketplace (mobility + delivery) with very durable network effects, accelerating earnings, and high-conviction AV (autonomous vehicles) partnership upside. Uber is at a good valuation on misplaced AV disruption fears (in my view).
Fundamentals:
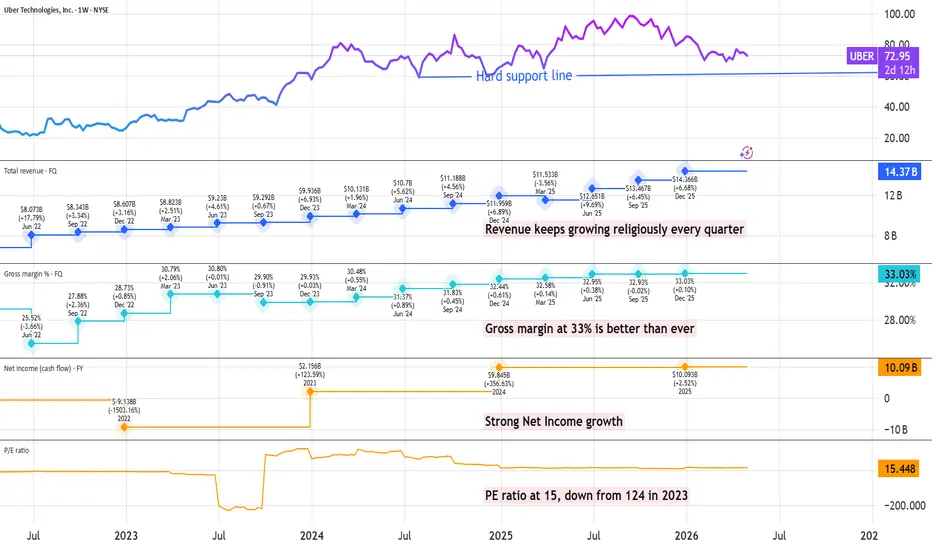
- TTM revenue $52B; bookings +19% in 2025 with accelerating momentum (users, trips, engagement). Revenue keeps growing religiously almost every quarter.
- Pre-tax operating profit +50% YoY; strong operating leverage and ~$10B FCF run-rate.
- Gross margins 33%, EBITDA ~12%, net ~20%. Clean balance sheet (cash $7.6B, low net debt). Gross margin is now at the best level ever.
- Market cap ~$150B at ~$73/share.
Economic Moat:
Powerful network effects, scale advantages, Uber One switching costs, and brand. Platform is the best aggregator for AV fleets.
Key Growth Drivers
- Core: Geographic/suburban expansion, delivery acceleration, new use cases (Moto), membership.
- AV: Commercial operations in 10-15+ cities by end-2026 via partnerships (Waymo, Nvidia, Rivian, VW, etc.). Uber’s hybrid model + data advantage positions it as a pick-and-shovel winner.
Valuation & Intrinsic Value
- Current 15x TTM P/E (22x NTM) is inexpensive for 15-20%+ bookings growth and 30%+ EPS growth outlook. The PE came down from 123 in 2023 to 15 now.
- Consensus price target: ~$105 (44% upside).
- Morningstar fair value: $85.
- Bull case (AV monetization): $125–200+ longer-term.
- Pershing Square says: “high-quality business… valuation is compelling” at 21x NTM.
Risks
AV companies going direct (mitigated by supply fragmentation); regulation/gig worker costs; macro slowdown; competition.
Sentiment
Strongly bullish among investors and on X: network + AV optionality seen as major tailwind; recent pullback viewed as buying opportunity.
What I'm doing
I'm allocating a bit above 1% of my portfolio into the stock.
Quick note: I'm just sharing my journey - not financial advice! 😊
- Henrique Centieiro
การซื้อขายยังคงดำเนินอยู่

Hedge Fund Manager | Wealth Educator | 20+ yrs investing | Stocks, ETFs & Crypto alerts | Join Henrique Wealth Academy for trade alerts & indicators → skool.com/be-limitless/
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน
Hedge Fund Manager | Wealth Educator | 20+ yrs investing | Stocks, ETFs & Crypto alerts | Join Henrique Wealth Academy for trade alerts & indicators → skool.com/be-limitless/
คำจำกัดสิทธิ์ความรับผิดชอบ
ข้อมูลและบทความไม่ได้มีวัตถุประสงค์เพื่อก่อให้เกิดกิจกรรมทางการเงิน, การลงทุน, การซื้อขาย, ข้อเสนอแนะ หรือคำแนะนำประเภทอื่น ๆ ที่ให้หรือรับรองโดย TradingView อ่านเพิ่มเติมใน ข้อกำหนดการใช้งาน