
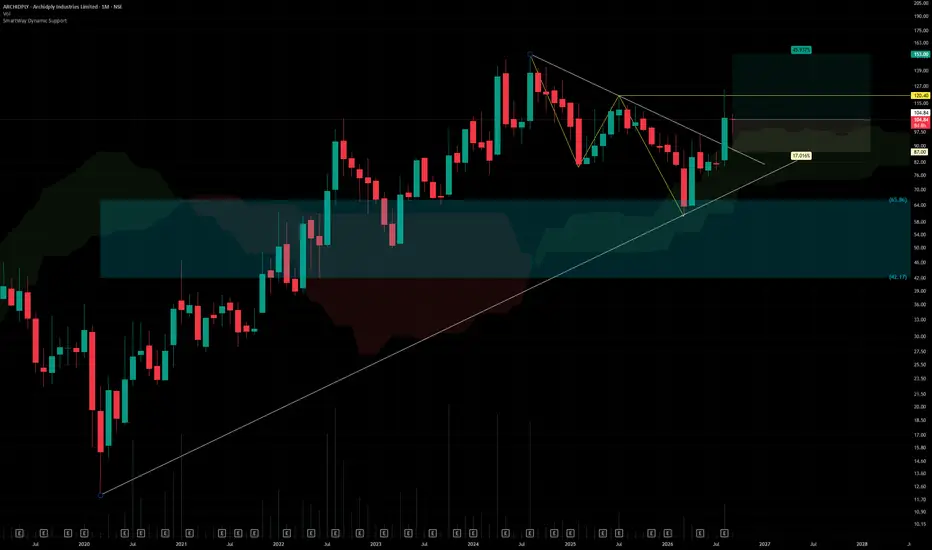
## Archidply Industries Ltd. (CMP ₹105.00, NSE: ARCHIDPLY)
**The SmartWay Research Desk | 22 September 2026**
A Bengaluru‑based building materials company, incorporated in 1976. Archidply Industries manufactures **plywood, blockboards, decorative laminates, and pre‑laminated boards**, catering to housing, furniture, and interior design sectors. The company has a strong distribution network across India and exports to select international markets.
**Promoter Holding (Jun 2026):** **Archidply Group (Dugar Family) — ~62.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹842 Cr vs ₹742 Cr in FY25 (+13.5% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹72 Cr vs ₹62 Cr in FY25 (+16.1% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹142 Cr, margin 16.9% vs 16.2% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹1.50/share declared for FY26. → **Neutral/Good**
- **Asset Building:** Investments in **laminate expansion and MDF boards**. → **Good**
- **Sales:** Strong demand from **housing and furniture sectors**. → **Good**
- **Expense:** Timber and resin costs remain elevated. → **Neutral/Good**
- **EPS:** FY26 EPS ₹12.25 vs ₹10.55 last year (+16.1%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~62.4% (no pledges)
- **FII Holding:** ~2.2%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~30.8%
---
### Strategic Moves & Innovations
- Expansion in **decorative laminates and MDF boards**.
- Focus on **eco‑friendly plywood and sustainable timber sourcing**.
- Partnerships with **architects and builders for premium projects**.
- Diversification into **interior design solutions and modular furniture boards**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹1,020 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹82.00; P/B ~1.3.
- EPS (TTM) ₹12.25; P/E ~8.6.
---
### Risk Factors
- Low **P/E ratio ~8.6**, valuations attractive.
- Dependence on **housing and infra demand cycles**.
- Exposure to **timber price volatility and import restrictions**.
- Competition from Century Plyboards, Greenply Industries, and Kitply.
---
### Investor Takeaway
Archidply Industries has delivered **steady FY26 performance**, supported by laminate expansion, MDF demand, and housing sector growth. With strong promoter backing (Dugar Family, 62.4% stake), dividend payouts, and leadership in decorative laminates, Archidply remains a **small‑cap building materials play**. At CMP ₹105.00, valuations are **attractive (P/E ~8.6, P/B ~1.3)**, reflecting growth potential with manageable risks.

Sucrit.D.Patil
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Sucrit.D.Patil
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.