
🎯 STOCK TO WATCH
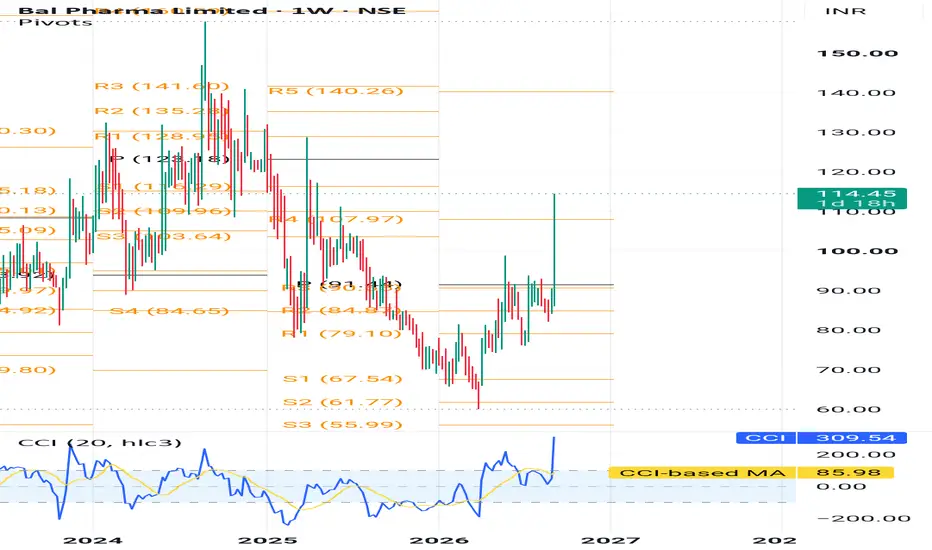
WEEKLY R4 MOMENTUM BREAKOUT SETUP
₹110–114 → ₹160 → ₹294 → ₹362
A small-cap pharma + API + export-oriented momentum setup appearing on my Weekly R4 Momentum Breakout Scanner.
💊 BAL PHARMA LTD
NSE: BALPHARMA
📌 TRADE LEVELS
🟢 Buy Zone: ₹110–114
🟠 Breakout Zone: ₹107
🔴 Stop Loss: ₹82
🎯 Target 1: ₹160
🚀 Target 2: ₹294
🔥 Target 3: ₹362
🔥 WHY BAL PHARMA?
• Revenue momentum: Q1 FY27 consolidated revenue was about ₹89 Cr, up ~34% YoY.
• API + formulations business: Bal Pharma operates across bulk actives, prescription/generic medicines, OTC products, IV infusions and formulations.
• Export-oriented platform: Its APIs and formulations are supplied across Europe, Australia, Japan, Far East, Latin America, Africa and Middle East markets.
• Integrated manufacturing: The company has manufacturing facilities across Bengaluru, Pune, Rudrapur, Sangli and Udaipur.
• Niche product portfolio: Its API portfolio spans areas including anti-diabetic, anti-histamine, anti-inflammatory, cardiovascular and other therapeutic segments.
• Fresh promoter capital: On 7 September 2026, Bal Pharma allotted 10 lakh convertible warrants to promoter Shailesh Siroya at ₹84 per warrant, aggregating ₹8.40 Cr.
👀 WHY IT CAUGHT MY ATTENTION
📈 ₹107 is the key breakout reference on my scanner.
📈 Buy zone sits at ₹110–114.
📈 Revenue growth has accelerated YoY.
📈 Export/API exposure provides multiple geographical markets.
📈 Small-cap pharma can produce sharp momentum when earnings and technical structure align.
📈 Promoter warrant allotment at ₹84 is worth tracking as a recent corporate-development signal.
⚠️ IMPORTANT — THIS ONE NEEDS DISCIPLINE
The Q1 headline growth is stronger than the sequential earnings picture. Operating profit was ₹7.95 Cr, down 24.8% QoQ, while net profit was ₹1.12 Cr, down 68.8% QoQ.
So I would not treat this as a pure fundamental compounder yet. The technical setup needs confirmation through sustained revenue growth, margins and cash generation.
Also, the recent ₹84 preferential warrant issue to the promoter should be factored into any detailed dilution/shareholding analysis.
Risk Defined. Reward Visible.
⚠️ This content is for educational purposes only and not investment advice. Please do your own due diligence before making any investment decisions.
© 20K Microcap Investing | R4 Momentum Desk
#BalPharma #BALPHARMA #PharmaStocks #APIStocks #SmallCapStocks #MomentumStocks #BreakoutStocks #IndianStocks #R4Momentum #StockToWatch

Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.