
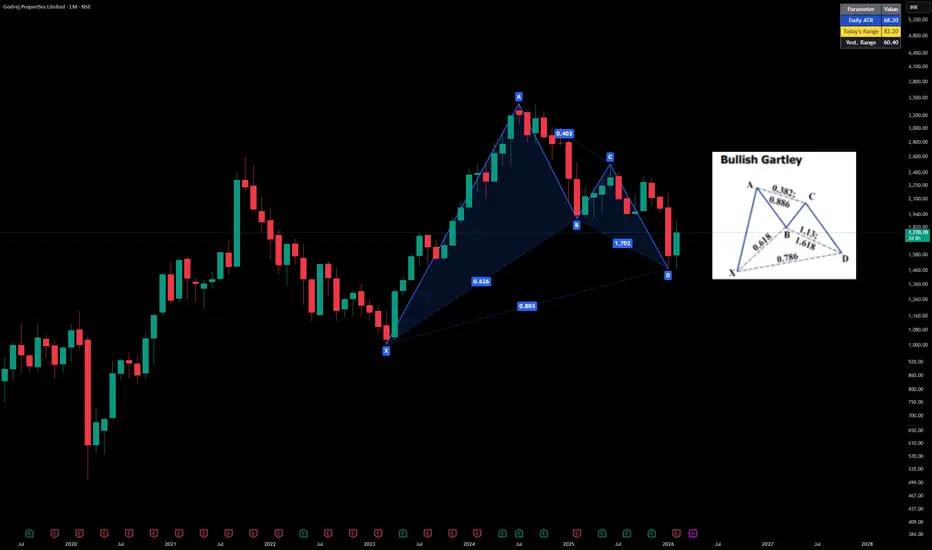
Godrej Properties Ltd. (NSE: GODREJPROP) is one of India’s leading real estate development companies, incorporated in 1990. It develops residential, commercial, and township projects across major Indian cities, leveraging the strong brand equity of the Godrej Group.
Promoter: Godrej Industries Ltd. (Godrej Family) – 58.48% holding (Dec 2025)
FY22–FY26 Snapshot
Revenue Growth: CAGR ~18% over FY22–FY26, driven by strong residential launches. → Good
Net Profit: FY26 PAT ~₹1,150 Cr, reflecting robust demand in housing. → Good
Operating Margin: Maintained ~20–22% range, showing efficiency in project execution. → Good
Equity Capital: Stable, no major dilution. → Good
Dividend Policy: Conservative, reinvesting profits into expansion. → Neutral
Asset Building: Expansion into Tier‑1 cities with large township projects. → Good
Sales: FY26 revenue crossed ₹9,000 Cr, supported by strong bookings. → Good
Expense: Land acquisition and construction costs remain high, impacting margins. → Neutral
EPS: ~₹32.5 in FY26, reflecting consistent earnings growth. → Good
Institutional Interest & Ownership Trends
Largest Promoter: Godrej Industries Ltd. (Godrej Family) – 58.48%
Largest FII: Government of Singapore Investment Corp. (GIC) – 6.72%
Largest DII: HDFC Mutual Fund – 4.15%
Strategic Moves & Innovations
Aggressive expansion in Mumbai, Pune, NCR, and Bangalore.
Focus on large township projects and premium housing.
Strengthening sustainable and green building practices.
Leveraging Godrej brand equity for customer trust.
Cash Flow & Balance Sheet Strength
Strong cash inflows from residential bookings.
Moderate debt levels, manageable with steady project pipeline.
Consistent profit growth supports scalability.
Risk Factors
High dependence on real estate cycles.
Margin sensitivity to land acquisition costs.
Regulatory delays in approvals.
Competition from other large developers (DLF, Oberoi Realty, Prestige Estates).
Investor Takeaway
Godrej Properties Ltd. is a leading real estate developer with strong promoter backing and rising institutional interest. With most snapshot parameters rated Good, the company shows consistent EPS growth, robust asset building, and strong sales momentum. Investors should monitor land acquisition costs and regulatory risks, but overall the outlook remains positive.

Sucrit.D.Patil
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Sucrit.D.Patil
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.