
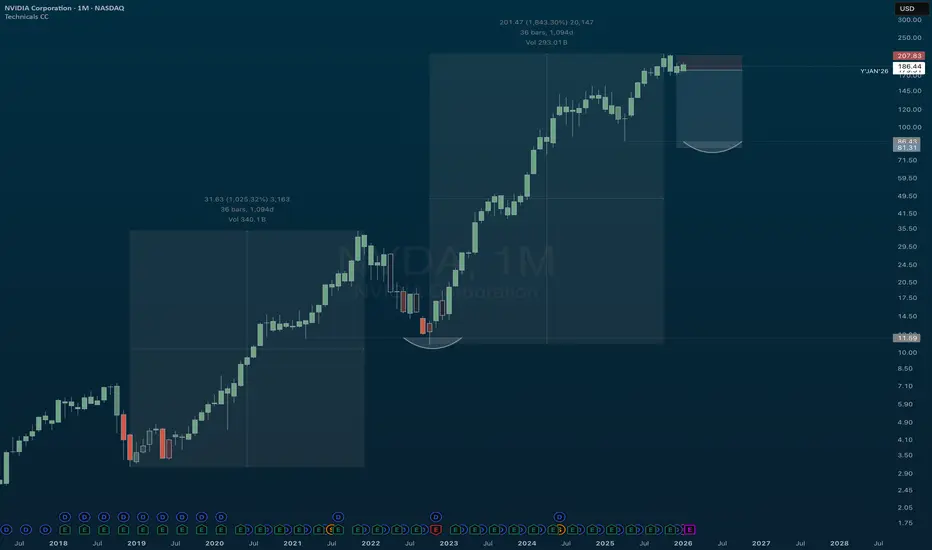
Time, price, and reflexivity at an inflection.
I’ve grown to distrust the perma-bear instinct to short strength. In most cases, it’s a fast track to underperformance and poverty. That said, ignoring time-price symmetry and macro context is equally dangerous. Both matter here.
NVDA appears to be operating on a remarkably consistent time-based cycle, almost script-like in nature. 2018–2021: ~1,094 days, ~10x return, cycle peak. 2022–2025: ~1,094 days, ~18x return, current phase.
We are now late in that second window.
Thesis: The "Circular Revenue" Red Flag (Fundamental Decay)
As of January 2026, NVDA’s Accounts Receivable has ballooned to over $33 Billion (up from just $8B two years ago).
They are shipping Blackwell chips, but the cash isn't hitting the bank yet. They are essentially "loaning" chips to startups they have invested in (like OpenAI and Anthropic).
When a company has to fund its own customers so they can buy its products, you aren't looking at organic growth; you’re looking at a liquidity treadmill that stops the moment Venture Capitalist (VCs) funding dries up.
The most dangerous part of the NVDA chart right now is the concentration. 60%+ of revenue comes from just four companies (Microsoft, Google, Meta, AWS).
All four are currently deploying their own silicon (Maia, Trainium, Axion). We are at "Peak Capex." These companies cannot spend $50B+ a quarter on chips forever. The moment they announce a "reduction in AI infrastructure spend" (likely in Q2/Q3 2026), the NVDA multiplier vanishes.
This structure is not new. It closely resembles the fiber-optic buildout of the late 1990s, where companies like Cisco and Nortel booked explosive top-line growth right up until the capital cycle reversed.
I am not calling for a collapse or a “short to zero” narrative. But the asymmetric upside that once existed is, in my view, largely exhausted for now.
From a broader market perspective, equities have transitioned into a weaker risk-efficiency regime. Sharpe ratios have deteriorated, and that shift has begun to propagate down the risk curve. NVDA itself has turned negative YTD, suggesting distribution rather than continuation at this stage.
There may still be volatility, retests, and tactical battles between bulls and bears at this inflection point. But reflexivity appears stretched. What remains supporting price increasingly looks like inertia rather than fresh marginal demand.
After an ~18x move in ~1,094 days, outperforming BTC, ETH, commodities, and most if not all single macro assets, expectations are saturated. Catalysts have largely been priced in. A correction, or at minimum a prolonged digestion phase, would not be bearish. It would be healthy.
Time will tell.

İlgili yayınlar
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
İlgili yayınlar
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.