☁️ Oracle: Defined-Risk Base Sets Up a 20% Fibonacci Rebound
ORCL trades near $144, roughly 58% below its late-2025 $345 peak. The opportunity is a defined-risk rebound, not a claim that the entire decline is over. Price must hold $132.50 tactically and reclaim $160.95 for confirmation.
Elliott Wave Count
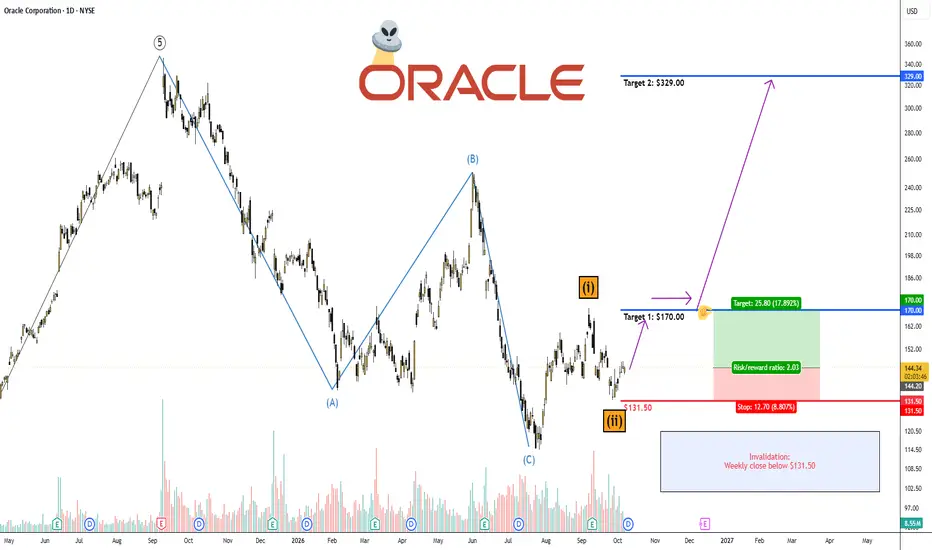
Weekly: the preferred Prechter count marks the advance from the 2020 $37 low to the late-2025 $345 peak as a completed five-wave impulse. The subsequent decline reads A-B-C: A to $145, B to $237, and C to the July $115 low. That places ORCL in a new base after a mature correction.
Daily: C’s July termination initiated wave (i) to $160.95; wave (ii) then retraced to $132.53 on September 29. The C-leg low showed momentum exhaustion and bullish RSI divergence, while the September retest preserved a higher RSI low. A daily close above $160.95 confirms wave (iii); formal Elliott invalidation is below $115, while the tactical long thesis fails below $132.50.
Fibonacci Mathematical Edge
Why ORCL Fell
➡️ Q1 fiscal 2027 capital expenditures reached $28.5 billion and free cash flow was negative $5.4 billion. Investors discounted the near-term cash burn required for AI capacity.
➡️ Oracle completed a $20 billion at-the-market equity sale. It improved funding capacity but introduced dilution alongside ongoing debt-financing concerns.
➡️ oftware revenue declined 3% year over year, while Oracle faces aggressive AI-cloud competition from hyperscalers and specialist providers. Investors want proof that record bookings convert into durable, high-margin revenue.
Bullish Catalysts
➡️ Technical: the C-wave low, the $143.40 38.2% retracement, and improving momentum converge in the $140-$146 entry area.
➡️ Fundamental: Q1 revenue rose 30% to $19.3 billion, cloud revenue rose 62% to $11.6 billion, OCI rose 121% to $7.4 billion, and RPO reached $664 billion. Q2 guidance calls for 30%-34% revenue growth and 65%-71% cloud growth.
➡️ News: Reuters reported a five-year, $7 billion Tencent AI-chip lease with a reported 30% upfront payment. Confirmation would support the demand case, although regulatory risk remains.
Trade Setup & Risk Management
Entry: $140-$146, ideally after a daily close above $146.
Target 1: $170-$175, about 18%-22% upside from $144.
Target 2: $239
Stop: daily close below $131.50.
Snapshots:


 ORCL #Oracle #ElliottWave #Fibonacci #WallStreet
ORCL trades near $144, roughly 58% below its late-2025 $345 peak. The opportunity is a defined-risk rebound, not a claim that the entire decline is over. Price must hold $132.50 tactically and reclaim $160.95 for confirmation.
Elliott Wave Count
Weekly: the preferred Prechter count marks the advance from the 2020 $37 low to the late-2025 $345 peak as a completed five-wave impulse. The subsequent decline reads A-B-C: A to $145, B to $237, and C to the July $115 low. That places ORCL in a new base after a mature correction.
Daily: C’s July termination initiated wave (i) to $160.95; wave (ii) then retraced to $132.53 on September 29. The C-leg low showed momentum exhaustion and bullish RSI divergence, while the September retest preserved a higher RSI low. A daily close above $160.95 confirms wave (iii); formal Elliott invalidation is below $115, while the tactical long thesis fails below $132.50.
Fibonacci Mathematical Edge
- The $115.00-$160.95 advance measures $45.95. Its 38.2%, 50.0%, and 61.8% retracements are $143.40, $138.00, and $132.55, placing current price at the first confluence.
- A 1.618 extension from $132.53 calculates to $206.88, while the weekly 23.6% and 38.2% reversal zones sit near $170 and $203.
Why ORCL Fell
➡️ Q1 fiscal 2027 capital expenditures reached $28.5 billion and free cash flow was negative $5.4 billion. Investors discounted the near-term cash burn required for AI capacity.
➡️ Oracle completed a $20 billion at-the-market equity sale. It improved funding capacity but introduced dilution alongside ongoing debt-financing concerns.
➡️ oftware revenue declined 3% year over year, while Oracle faces aggressive AI-cloud competition from hyperscalers and specialist providers. Investors want proof that record bookings convert into durable, high-margin revenue.
Bullish Catalysts
➡️ Technical: the C-wave low, the $143.40 38.2% retracement, and improving momentum converge in the $140-$146 entry area.
➡️ Fundamental: Q1 revenue rose 30% to $19.3 billion, cloud revenue rose 62% to $11.6 billion, OCI rose 121% to $7.4 billion, and RPO reached $664 billion. Q2 guidance calls for 30%-34% revenue growth and 65%-71% cloud growth.
➡️ News: Reuters reported a five-year, $7 billion Tencent AI-chip lease with a reported 30% upfront payment. Confirmation would support the demand case, although regulatory risk remains.
Trade Setup & Risk Management
Entry: $140-$146, ideally after a daily close above $146.
Target 1: $170-$175, about 18%-22% upside from $144.
Target 2: $239
Stop: daily close below $131.50.
Snapshots:
ORCL #Oracle #ElliottWave #Fibonacci #WallStreet
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.