
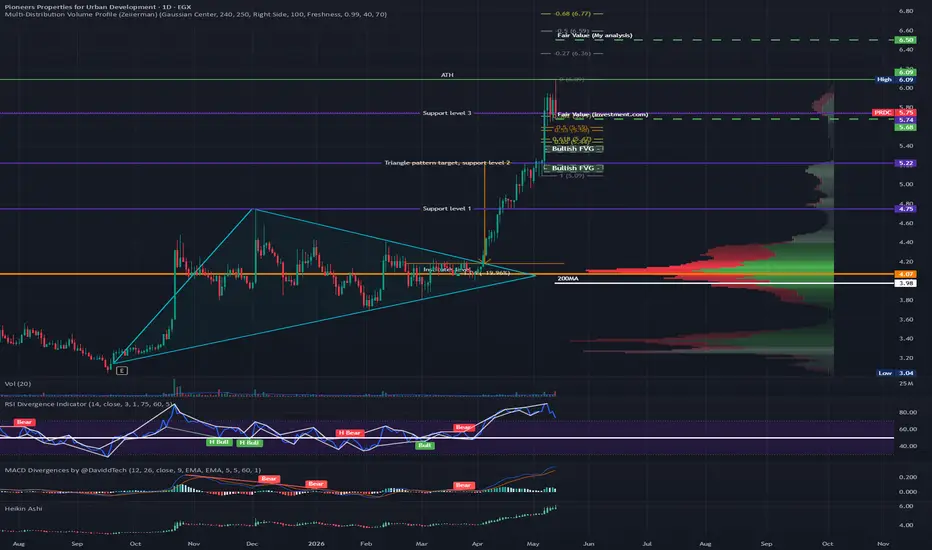
PRDC – Triangle Target Hit as Pullback Intensifies 📉🏢
The Reality: I see a "Growth Transition Play" with a deep split! 🔀
FY2025 revenue soared to EGP 6.41B 🚀, but consolidated net profit plunged to EGP 361.77M 📉.
Stretched customer installment windows mean "paper profits" are racing way ahead of cold, hard operational cash (CFO)! 💸⚓
The Valuation Gap: I find the stock heavily underpriced at 5.75 EGP 📉.
The market is completely ignoring its huge 6.97 EGP Parent Book Value 📜!
My fair value target of 6.50 EGP (11x P/E on 0.35 EGP Parent EPS + EGP 2.65 asset premium for the new 10,000-key hotel pipeline) exposes a juicy 13.0% discount 🎯⚖️!
The Leverage Overload: I observe a dangerous dependency on bank loans to fuel an aggressive EGP 10B+ contracting backlog 🏗️.
In Egypt’s punishing 19% interest rate environment, heavy financing costs act as a massive anchor on net margins ⚓
commercial bank lines are eating the profits 🏦🔥.
Sharia Status: ❌ Non-Compliant.
Conventional debt heavily breaches the 33% market cap cap ⛓️, and huge conventional cash buffers violate the 5% interest purity filter 💰.
It remains excluded from the EGX33 Shariah Index ❌📜.
Technical Analysis:
The Exhaustion Signal: I noticed the stock hit its target after a triangle breakout to an ATH of 6.09 EGP before hitting an aggressive institutional profit-taking wall 🎯🏁.
The Key Support Levels:
5.74: The first immediate line of defense.
Aligns with local support and key moving averages 🩹.
5.22: The secondary structural floor.
If heavy selling volume persists next week, expect a retest here 🧱🏹.
4.75: The ultimate "Line in the Sand."
A break below marks a structural Change of Character (ChoCh) to a confirmed bearish downtrend 🛑📉.
The Upside Target: If bulls absorb this correction and volume returns, a sustained wave faces open skies up to your 6.50 EGP fair value 🚀🏆.
Verdict: The Heavy Asset Turnaround. 🎲🏗️
I view PRDC as a solid growth play trapped under a debt wall.
If the current structural support holds, it's a modest buy for the 6.50 EGP value gap.
However, the sheer size of the bearish volume means traders should keep defensive lines close to the chest. 🛡️🔭
Do you think management will step in with a treasury stock buyback program to defend the 5.68 support level, or will the debt burden force them to conserve cash? 🤔🏢🔍
If I like my posts, I follow and boost 🙌✨
🎁 Get a $15 discount on my next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸

Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.