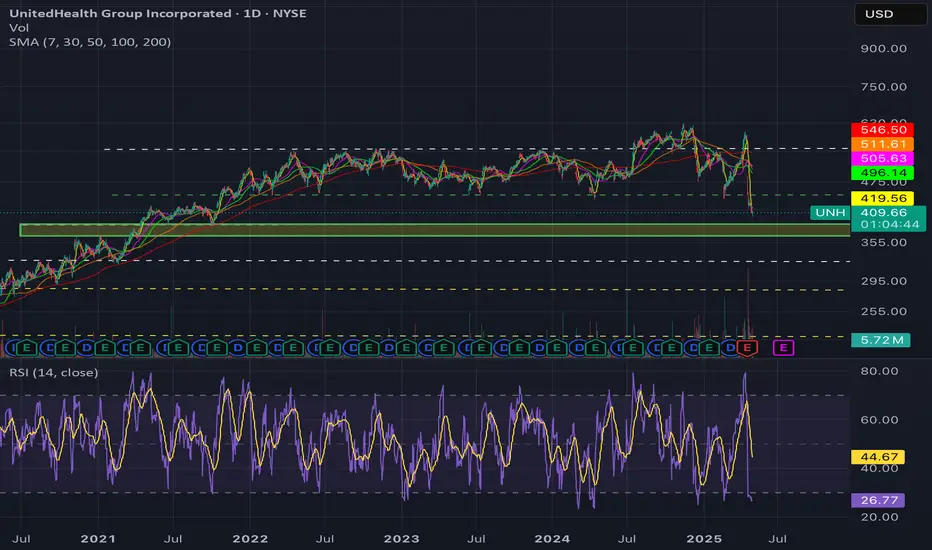
- Fundamentally it's undervalued for the quality blue chip company. My detailed analysis is on the older post I made earlier this year. I have attached that as a reference.
- In my previous swing, I bought UNH on a sell off @ 441 and sold @600 before earning as a de-risking strategy. I'm glad that it did work out.
- I'm happy thatUNH is again trading at a discount and with compressed Earning multiple. This time I am buying it even lower than where I bought last time i.e 441 and I was happy with that price average.
- Whereas I do believe thatUNH EPS is lowered but it is lowered slightly which doesn't warrant a big sell off like this.
- I wanted to wait further before entering but I can't stop myself from buying this nameUNH at a price where I believe it's very undervalued.
- Therefore, I have re-entered theUNH and added it to my portfolio . I will consider adding further if selling pressure continues because I don't want to time the bottom.
- But undecisive market and lumpy market, going with a defensive name like this is a no brainer.
- In my previous swing, I bought
UNH on a sell off @ 441 and sold @600 before earning as a de-risking strategy. I'm glad that it did work out. - I'm happy that
UNH is again trading at a discount and with compressed Earning multiple. This time I am buying it even lower than where I bought last time i.e 441 and I was happy with that price average. - Whereas I do believe that
UNH EPS is lowered but it is lowered slightly which doesn't warrant a big sell off like this. - I wanted to wait further before entering but I can't stop myself from buying this name
UNH at a price where I believe it's very undervalued. - Therefore, I have re-entered the
UNH and added it to my portfolio . I will consider adding further if selling pressure continues because I don't want to time the bottom. - But undecisive market and lumpy market, going with a defensive name like this is a no brainer.
Not
Bought UNH today @ < $410Not
In my previous swing of UNH I made roughly 37% over a period of 2 monthsNot
EPS growth is healthy double digit in mid teens. A fair forward p/e multiple for mid teen EPS growth should at least be 15 ( conservatively )Year | 2024 | 2025 | 2026 | 2027 | 2028
Fair Stock Price (w/ forward p/e = 15 ) | $236 | $423 | $481 | $552 | $616
However,
UNH is a blue chip company and has a moat. Therefore, Investors will be willing to pay forward p/e of 20 once negative news subside.
Year | 2024 | 2025 | 2026 | 2027 | 2028
Fair Stock Price (w/ forward p/e = 20 ) | $315 | $564 | $642 | $736 | $822.2
Not
Fair value for UNH in 2025 is around 550-564 on a forward p/e for 20Not
I saw the updated EPS after the company lowered earning estimates. So, here's my updated price levels. Idea is to buy stock close to fair value:-> Conservative base case estimates:
Year | 2025 | 2026 | 2027 | 2028
EPS | 26.36 | 30.2 | 34.47 | 41.74
Fair Stock Price (w/ forward p/e = 15 ) | $395 | $453 | $517 | $626
-> Base Case : Forward p/e 20 for a defensive name with a moat growing EPS at 15% yearly
Fair Stock Price (w/ forward p/e = 20 ) | $527 | $604 | $680 | $834
Not
- Adding more UNH on this sell off @ 340 .- Guidances often gets pulled when looking for new CEO because it allows new CEO to set expectation.
- Buy the fear!
Not
- UNH appointed long time CEO which led UNH through tough times and through GFC ( Great financial crisis )- Lot of negativity is priced in and even with all the doom & gloom end of the world this stock is at least worth $395 with forward p/e of 15 and it provides you dividend yield of 2.78% while you wait.
Not
Based on management,EPS for FY 2025 reduced to 22.09 and FY 2026 reduced to 26.67
Revised conservative price target for
FY 2025, 15 x 22.09 = $331.35
Fy 2026, 15 x 26.67 = $400
Revised base price target for
FY 2025, 20 x 22.09 = $441.35
Fy 2026, 20 x 26.67 = $533
Not
- CEO added 25 mil worth of stock which adds confidence in the company further!Not
Director bought 1 mil worth of shares of UNH last weekNot
- CFO bought 5 million worth of shares of UNH today May 10, 2025Not
Ideally, UNH should fill the gap @305 and @375Not
- Filled the gap @305 .- Next target @ 375 , let the Shorts pile up which will add fuel to the fire so that
UNH can rocket even higher :)Not
- This should trade more than $450 before the year end. Unwarranted sell off!Not
- UNH is forming a base. Consolidation before spring action.Not
Excited for earnings
İlgili yayınlar
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
İlgili yayınlar
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.