
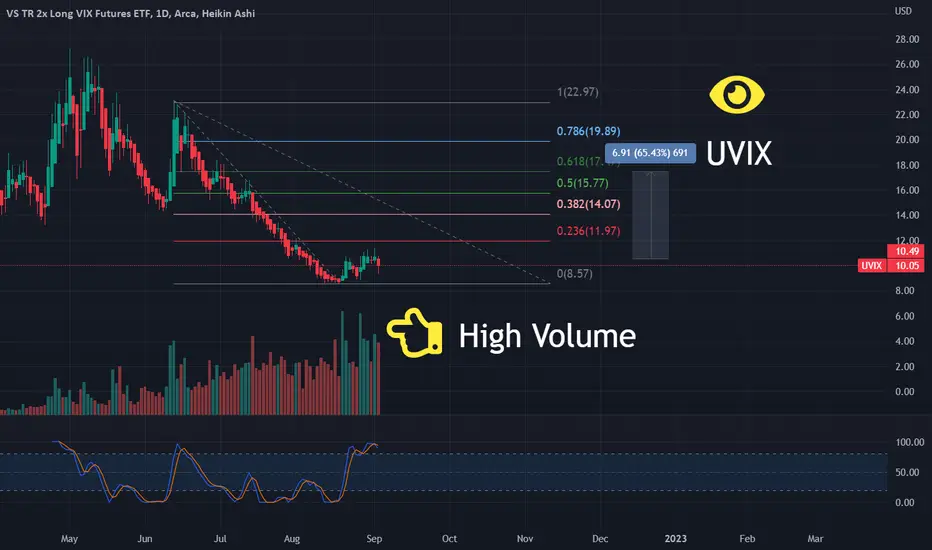
The index measures the daily performance of a portfolio of long positions in first and second month VIX futures contracts. This theoretical portfolio is rolled each day to maintain a consistent time to maturity of the futures contracts. The index is calculated daily at 4:00 p.m. (Eastern time) and at a value calculated from the average price for the futures contracts between 3:45 p.m. (Eastern time) and 4:00 p.m. (Eastern time).
Its that time of the year.
Its that time of the year.

99% of the market trades the noise. I trade the math. Professional divergence hunter and volume tracker. Enter the Seeker Lab:
linktr.ee/DivergenceSeeker
linktr.ee/DivergenceSeeker
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.