CNPS24_BASIS MEAN REVERSION
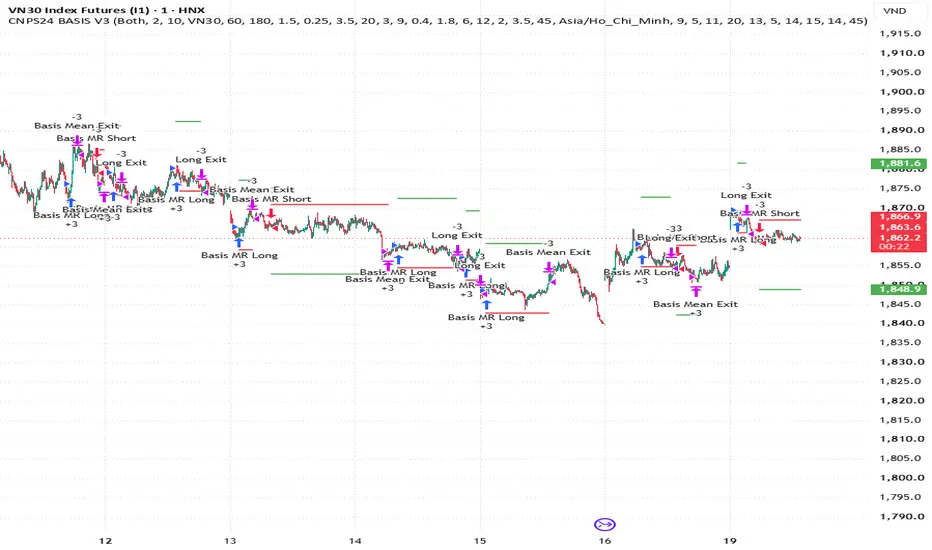
CNPS24 BASIS MEAN REVERSION V3
CNPS24 is a relative-value mean-reversion strategy designed around the price relationship between VN30 futures and the VN30 spot index.
Unlike a conventional directional indicator strategy, the primary signal is derived from the futures-versus-spot basis.
━━━━━━━━━━━━━━━━━━
1. STRATEGY CONCEPT
━━━━━━━━━━━━━━━━━━
The strategy calculates:
Futures Price
−
VN30 Spot Index
=
Intraday Basis
The basis is then standardized using its recent historical mean and volatility.
This produces a Basis Z-Score.
The strategy attempts to identify temporary extreme premiums or discounts and trade their normalization.
━━━━━━━━━━━━━━━━━━
2. REFERENCE MARKET
━━━━━━━━━━━━━━━━━━
Default Spot Reference:
HOSE:VN30
The futures price is taken from the active chart.
The quality and availability of the reference symbol are therefore important to the model.
━━━━━━━━━━━━━━━━━━
3. BASIS MODEL
━━━━━━━━━━━━━━━━━━
Default parameters:
Basis Mean / Z Window: 60 bars
Long Basis Volatility Window: 180 bars
The shorter window estimates the current mean and Z-score.
The longer window is used to evaluate the broader volatility regime of the basis.
━━━━━━━━━━━━━━━━━━
4. LONG SETUP
━━━━━━━━━━━━━━━━━━
A Long setup begins when futures trade at an unusually large discount relative to spot.
Sequence:
Basis Z <= -Entry Z
→ Extreme discount detected
→ Long setup is armed
→ Basis begins to hook upward
→ Price confirmation appears
→ LONG
Default Entry Z:
1.50
The strategy does not automatically buy the most extreme basis print.
It waits for evidence that the spread is beginning to mean-revert.
━━━━━━━━━━━━━━━━━━
5. SHORT SETUP
━━━━━━━━━━━━━━━━━━
A Short setup uses the mirrored process.
Basis Z >= +Entry Z
→ Extreme premium detected
→ Short setup is armed
→ Basis begins to hook downward
→ Price confirmation appears
→ SHORT
The concept is to trade normalization after futures become statistically expensive relative to the spot reference.
━━━━━━━━━━━━━━━━━━
6. EXTREME CONTROL
━━━━━━━━━━━━━━━━━━
The strategy limits how extreme the accepted entry condition can become.
Default Maximum Acceptable Absolute Z:
3.50
This prevents the model from automatically treating every increasingly extreme spread as a better mean-reversion opportunity.
A very large Z-score may instead indicate a regime change, data issue or persistent repricing.
━━━━━━━━━━━━━━━━━━
7. PRICE CONFIRMATION
━━━━━━━━━━━━━━━━━━
Basis normalization alone is not sufficient for entry.
The strategy also evaluates price action.
Default confirmation components include:
EMA Length: 9
Minimum Candle Body / Range: 40%
Previous High / Low Break: ON
EMA Confirmation: ON
This adds directional confirmation to the statistical basis signal.
━━━━━━━━━━━━━━━━━━
8. VOLATILITY REGIME FILTER
━━━━━━━━━━━━━━━━━━
CNPS24 includes a basis-volatility regime filter.
Default:
Enabled
Maximum Short-Term / Long-Term Basis Volatility Ratio:
1.80
The strategy can therefore reject setups when short-term basis volatility becomes unusually unstable relative to its longer-term behavior.
━━━━━━━━━━━━━━━━━━
9. HARD RISK MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default:
Stop Loss: 6 points
Take Profit: 12 points
Theoretical fixed Risk/Reward:
1:2
Position Size:
3 contracts
Pyramiding is disabled.
━━━━━━━━━━━━━━━━━━
10. STATISTICAL EXIT
━━━━━━━━━━━━━━━━━━
The strategy can exit before the fixed Take Profit when the basis has already returned close to its statistical mean.
Default Mean-Reversion Exit:
Absolute Basis Z <= 0.25
However, the statistical exit is only allowed after the trade has reached a minimum open profit.
Default Minimum Profit:
2 points
This prevents the strategy from closing a position at the statistical mean while the directional trade is still unprofitable.
━━━━━━━━━━━━━━━━━━
11. OPTIONAL EMERGENCY CONTROLS
━━━━━━━━━━━━━━━━━━
The strategy includes an optional Z-score emergency stop.
Default:
OFF
An optional time stop is also available.
These controls are not part of the default execution path but can be evaluated during research.
━━━━━━━━━━━━━━━━━━
12. TRADE CONTROL
━━━━━━━━━━━━━━━━━━
Default:
Maximum Trades Per Day: 2
Cooldown After Exit: 10 bars
Break-Even: Not used
The strategy is intentionally cost-aware because spread signals on low timeframes can otherwise generate excessive turnover.
━━━━━━━━━━━━━━━━━━
13. SESSION MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default timezone:
Asia/Ho_Chi_Minh
The strategy uses separate morning and afternoon entry windows.
The final entry time occurs before the end of the futures trading session.
Open positions are force-closed according to the configured session-end rule.
━━━━━━━━━━━━━━━━━━
14. BACKTEST ASSUMPTIONS
━━━━━━━━━━━━━━━━━━
Initial Capital: 100,000,000
Position Size: 3 contracts
Commission: 10,000 VND per contract
Slippage: 3 ticks
Pyramiding: 0
━━━━━━━━━━━━━━━━━━
15. IMPORTANT MODEL CONSIDERATIONS
━━━━━━━━━━━━━━━━━━
CNPS24 is fundamentally different from a standard trend-following system.
Its edge depends on the relationship between two instruments.
Backtesting should therefore pay particular attention to:
• Spot reference availability
• Data synchronization
• Basis behavior across expiries
• Intraday volatility
• Entry Z threshold
• Mean-reversion speed
• Transaction costs
• Structural changes in futures premium / discount
━━━━━━━━━━━━━━━━━━
DISCLAIMER
━━━━━━━━━━━━━━━━━━
This strategy is provided for educational, analytical and backtesting purposes only.
It does not constitute financial advice or a recommendation to trade a relative-value position.
Past statistical relationships may change and do not guarantee future convergence.
Trading futures and leveraged financial instruments involves substantial risk. Users are responsible for all trading and risk-management decisions.
CNPS24 is a relative-value mean-reversion strategy designed around the price relationship between VN30 futures and the VN30 spot index.
Unlike a conventional directional indicator strategy, the primary signal is derived from the futures-versus-spot basis.
━━━━━━━━━━━━━━━━━━
1. STRATEGY CONCEPT
━━━━━━━━━━━━━━━━━━
The strategy calculates:
Futures Price
−
VN30 Spot Index
=
Intraday Basis
The basis is then standardized using its recent historical mean and volatility.
This produces a Basis Z-Score.
The strategy attempts to identify temporary extreme premiums or discounts and trade their normalization.
━━━━━━━━━━━━━━━━━━
2. REFERENCE MARKET
━━━━━━━━━━━━━━━━━━
Default Spot Reference:
HOSE:VN30
The futures price is taken from the active chart.
The quality and availability of the reference symbol are therefore important to the model.
━━━━━━━━━━━━━━━━━━
3. BASIS MODEL
━━━━━━━━━━━━━━━━━━
Default parameters:
Basis Mean / Z Window: 60 bars
Long Basis Volatility Window: 180 bars
The shorter window estimates the current mean and Z-score.
The longer window is used to evaluate the broader volatility regime of the basis.
━━━━━━━━━━━━━━━━━━
4. LONG SETUP
━━━━━━━━━━━━━━━━━━
A Long setup begins when futures trade at an unusually large discount relative to spot.
Sequence:
Basis Z <= -Entry Z
→ Extreme discount detected
→ Long setup is armed
→ Basis begins to hook upward
→ Price confirmation appears
→ LONG
Default Entry Z:
1.50
The strategy does not automatically buy the most extreme basis print.
It waits for evidence that the spread is beginning to mean-revert.
━━━━━━━━━━━━━━━━━━
5. SHORT SETUP
━━━━━━━━━━━━━━━━━━
A Short setup uses the mirrored process.
Basis Z >= +Entry Z
→ Extreme premium detected
→ Short setup is armed
→ Basis begins to hook downward
→ Price confirmation appears
→ SHORT
The concept is to trade normalization after futures become statistically expensive relative to the spot reference.
━━━━━━━━━━━━━━━━━━
6. EXTREME CONTROL
━━━━━━━━━━━━━━━━━━
The strategy limits how extreme the accepted entry condition can become.
Default Maximum Acceptable Absolute Z:
3.50
This prevents the model from automatically treating every increasingly extreme spread as a better mean-reversion opportunity.
A very large Z-score may instead indicate a regime change, data issue or persistent repricing.
━━━━━━━━━━━━━━━━━━
7. PRICE CONFIRMATION
━━━━━━━━━━━━━━━━━━
Basis normalization alone is not sufficient for entry.
The strategy also evaluates price action.
Default confirmation components include:
EMA Length: 9
Minimum Candle Body / Range: 40%
Previous High / Low Break: ON
EMA Confirmation: ON
This adds directional confirmation to the statistical basis signal.
━━━━━━━━━━━━━━━━━━
8. VOLATILITY REGIME FILTER
━━━━━━━━━━━━━━━━━━
CNPS24 includes a basis-volatility regime filter.
Default:
Enabled
Maximum Short-Term / Long-Term Basis Volatility Ratio:
1.80
The strategy can therefore reject setups when short-term basis volatility becomes unusually unstable relative to its longer-term behavior.
━━━━━━━━━━━━━━━━━━
9. HARD RISK MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default:
Stop Loss: 6 points
Take Profit: 12 points
Theoretical fixed Risk/Reward:
1:2
Position Size:
3 contracts
Pyramiding is disabled.
━━━━━━━━━━━━━━━━━━
10. STATISTICAL EXIT
━━━━━━━━━━━━━━━━━━
The strategy can exit before the fixed Take Profit when the basis has already returned close to its statistical mean.
Default Mean-Reversion Exit:
Absolute Basis Z <= 0.25
However, the statistical exit is only allowed after the trade has reached a minimum open profit.
Default Minimum Profit:
2 points
This prevents the strategy from closing a position at the statistical mean while the directional trade is still unprofitable.
━━━━━━━━━━━━━━━━━━
11. OPTIONAL EMERGENCY CONTROLS
━━━━━━━━━━━━━━━━━━
The strategy includes an optional Z-score emergency stop.
Default:
OFF
An optional time stop is also available.
These controls are not part of the default execution path but can be evaluated during research.
━━━━━━━━━━━━━━━━━━
12. TRADE CONTROL
━━━━━━━━━━━━━━━━━━
Default:
Maximum Trades Per Day: 2
Cooldown After Exit: 10 bars
Break-Even: Not used
The strategy is intentionally cost-aware because spread signals on low timeframes can otherwise generate excessive turnover.
━━━━━━━━━━━━━━━━━━
13. SESSION MANAGEMENT
━━━━━━━━━━━━━━━━━━
Default timezone:
Asia/Ho_Chi_Minh
The strategy uses separate morning and afternoon entry windows.
The final entry time occurs before the end of the futures trading session.
Open positions are force-closed according to the configured session-end rule.
━━━━━━━━━━━━━━━━━━
14. BACKTEST ASSUMPTIONS
━━━━━━━━━━━━━━━━━━
Initial Capital: 100,000,000
Position Size: 3 contracts
Commission: 10,000 VND per contract
Slippage: 3 ticks
Pyramiding: 0
━━━━━━━━━━━━━━━━━━
15. IMPORTANT MODEL CONSIDERATIONS
━━━━━━━━━━━━━━━━━━
CNPS24 is fundamentally different from a standard trend-following system.
Its edge depends on the relationship between two instruments.
Backtesting should therefore pay particular attention to:
• Spot reference availability
• Data synchronization
• Basis behavior across expiries
• Intraday volatility
• Entry Z threshold
• Mean-reversion speed
• Transaction costs
• Structural changes in futures premium / discount
━━━━━━━━━━━━━━━━━━
DISCLAIMER
━━━━━━━━━━━━━━━━━━
This strategy is provided for educational, analytical and backtesting purposes only.
It does not constitute financial advice or a recommendation to trade a relative-value position.
Past statistical relationships may change and do not guarantee future convergence.
Trading futures and leveraged financial instruments involves substantial risk. Users are responsible for all trading and risk-management decisions.

Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.