MOYA VWAP Suite [RealSebastianMoya]
Hello traders!
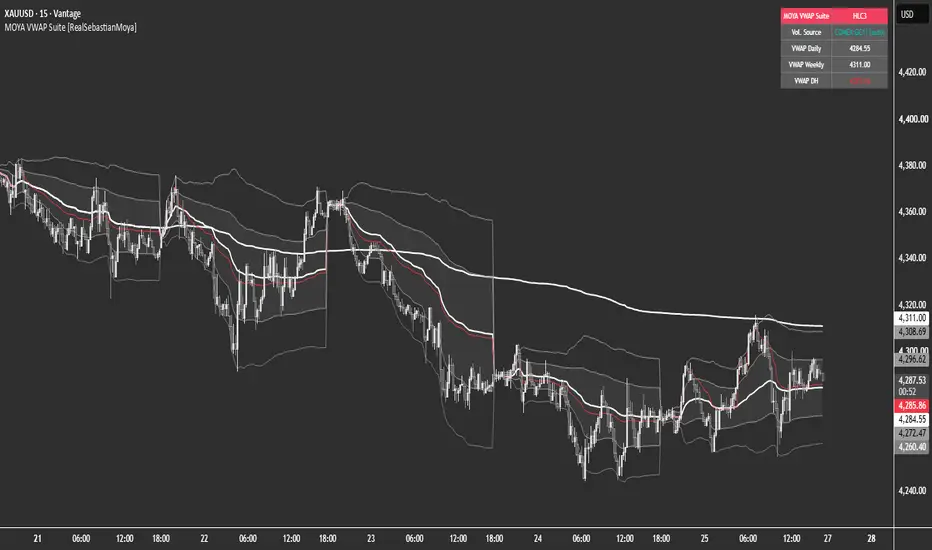
Introducing: "MOYA VWAP Suite"
This script brings together every meaningful way institutional and retail traders use VWAP into a single, fully configurable tool — five independent session-based VWAPs, classic period-extreme anchored VWAPs (Daily/Weekly/Monthly, High and Low), a custom anchor for swing points or exact dates, standard deviation bands, and real futures volume normalization for Forex/CFD charts.

Rather than forcing you to choose one "flavor" of VWAP, this script lets every type run simultaneously, each with independent styling — so you can build the exact multi-timeframe VWAP stack you actually trade with.
♦ Why VWAP Matters
VWAP (Volume Weighted Average Price) isn't just another moving average — it's the price institutions benchmark their own execution against. Large funds can't fill a position in one trade without moving the market against themselves, so they split large orders across the session and measure their own performance relative to VWAP: filling below it on a buy program is considered good execution, filling above it is considered poor execution.
Because of this, VWAP behaves like a real support/resistance level with actual participants defending it — not just a lagging technical indicator.
♦ Features
Standard VWAP — 5 Configurable Slots Each slot can be set to any of 29 session lengths (Tokyo, London, New York, 1H through 12H, Daily through 7 Days, Weekly through 5 Weeks, Monthly through 7 Months, Quarterly, Yearly), with independent color, width, and line style (Solid, StepLine, Circles, Cross, Dashed).
VWAP Close Levels When a session ends, mark a fixed horizontal line at the price where that session's VWAP closed — a persistent reference level, independently styled per slot.
Period-Extreme Anchored VWAP (Daily / Weekly / Monthly) A VWAP that continuously re-anchors itself live, every time a new high or low forms within the current day, week, or month. Choose to anchor from the High, the Low, or both simultaneously, with independent colors for each.
Custom Anchored VWAP Anchor from an automatically detected swing high/low (with adjustable sensitivity) or from an exact date and time you set yourself — for anchoring to a specific event, range start, or impulse move.
Standard Deviation Bands Two configurable bands calculated around any VWAP in the script (any of the 5 slots, any of the six period-extreme anchors, or the custom anchor), with independent multiplier, line colors, width, and fill color per band — matching TradingView's native VWAP band styling.
Real Futures Volume Normalization Forex and CFD brokers report synthetic tick volume, not real traded volume. This script can automatically detect the related futures contract for your current symbol (XAUUSD → Gold futures, EURUSD → Euro futures, BTCUSD → Bitcoin futures, and more) and rescale the volume weighting every VWAP uses, so the calculation reflects real market participation instead of your broker's tick count.
Live Information Panel Shows the current value of every active VWAP, plus which volume source is feeding the calculation and whether it's receiving live data — all in one glance, positioned in any corner of the chart.
♦ Who This Is For
This script is built for traders who read the market through volume-weighted price levels rather than pure price action — those who already think in terms of:
fair value and execution benchmarks
multi-timeframe confluence (does the daily VWAP sit inside last week's anchored range?)
mean reversion toward a statistically "fair" price versus continuation away from it
how real, regulated market volume compares to what a CFD broker reports
If you're used to trading around VWAP on futures or equities and want that same read available across Forex, indices, crypto, and any other chart — including with real futures-based volume weighting — this is built for that specific use case.
♦ How It's Used — Example Approaches
Intraday mean reversion: Run Slot 1 on Daily VWAP as your session baseline. Price extended away from it without matching volume growth often reverts back toward the line — especially when it's also sitting inside the Band #1 deviation range.
Multi-timeframe bias: Run Slot 1 (Daily), Slot 2 (Weekly), and Slot 3 (Monthly) together. When price is above all three, that's confluence for a bullish bias; when the daily VWAP crosses back below the weekly, that's an early signal the shorter-term trend may be losing strength.
Reacting to a specific move: Use the Custom Anchor to mark the VWAP starting from a major swing low or a specific news candle — this shows you the volume-weighted average price of everyone who has traded since that exact point, which is often more relevant than a session-based VWAP when you're tracking a specific move.
Trading real institutional levels on Forex/CFD: Enable External Futures Volume with Auto Detect on a symbol like XAUUSD — the VWAP and its bands now reflect real Gold futures volume instead of your broker's synthetic tick count, which matters most exactly when the two diverge.
(Configuration walkthroughs and chart examples for each of these scenarios below.)
♦ Credits
Original inspiration drawn from the standard institutional VWAP concept and Auction Market Theory. Extended and combined by RealSebastianMoya / MOYA Organization into a unified multi-mode VWAP engine with real futures volume normalization — an original build, not a modification of a third-party script.
Licensed under Mozilla Public License 2.0.
Open-source script
Introducing: "MOYA VWAP Suite"
This script brings together every meaningful way institutional and retail traders use VWAP into a single, fully configurable tool — five independent session-based VWAPs, classic period-extreme anchored VWAPs (Daily/Weekly/Monthly, High and Low), a custom anchor for swing points or exact dates, standard deviation bands, and real futures volume normalization for Forex/CFD charts.
Rather than forcing you to choose one "flavor" of VWAP, this script lets every type run simultaneously, each with independent styling — so you can build the exact multi-timeframe VWAP stack you actually trade with.
♦ Why VWAP Matters
VWAP (Volume Weighted Average Price) isn't just another moving average — it's the price institutions benchmark their own execution against. Large funds can't fill a position in one trade without moving the market against themselves, so they split large orders across the session and measure their own performance relative to VWAP: filling below it on a buy program is considered good execution, filling above it is considered poor execution.
Because of this, VWAP behaves like a real support/resistance level with actual participants defending it — not just a lagging technical indicator.
♦ Features
Standard VWAP — 5 Configurable Slots Each slot can be set to any of 29 session lengths (Tokyo, London, New York, 1H through 12H, Daily through 7 Days, Weekly through 5 Weeks, Monthly through 7 Months, Quarterly, Yearly), with independent color, width, and line style (Solid, StepLine, Circles, Cross, Dashed).
VWAP Close Levels When a session ends, mark a fixed horizontal line at the price where that session's VWAP closed — a persistent reference level, independently styled per slot.
Period-Extreme Anchored VWAP (Daily / Weekly / Monthly) A VWAP that continuously re-anchors itself live, every time a new high or low forms within the current day, week, or month. Choose to anchor from the High, the Low, or both simultaneously, with independent colors for each.
Custom Anchored VWAP Anchor from an automatically detected swing high/low (with adjustable sensitivity) or from an exact date and time you set yourself — for anchoring to a specific event, range start, or impulse move.
Standard Deviation Bands Two configurable bands calculated around any VWAP in the script (any of the 5 slots, any of the six period-extreme anchors, or the custom anchor), with independent multiplier, line colors, width, and fill color per band — matching TradingView's native VWAP band styling.
Real Futures Volume Normalization Forex and CFD brokers report synthetic tick volume, not real traded volume. This script can automatically detect the related futures contract for your current symbol (XAUUSD → Gold futures, EURUSD → Euro futures, BTCUSD → Bitcoin futures, and more) and rescale the volume weighting every VWAP uses, so the calculation reflects real market participation instead of your broker's tick count.
Live Information Panel Shows the current value of every active VWAP, plus which volume source is feeding the calculation and whether it's receiving live data — all in one glance, positioned in any corner of the chart.
♦ Who This Is For
This script is built for traders who read the market through volume-weighted price levels rather than pure price action — those who already think in terms of:
fair value and execution benchmarks
multi-timeframe confluence (does the daily VWAP sit inside last week's anchored range?)
mean reversion toward a statistically "fair" price versus continuation away from it
how real, regulated market volume compares to what a CFD broker reports
If you're used to trading around VWAP on futures or equities and want that same read available across Forex, indices, crypto, and any other chart — including with real futures-based volume weighting — this is built for that specific use case.
♦ How It's Used — Example Approaches
Intraday mean reversion: Run Slot 1 on Daily VWAP as your session baseline. Price extended away from it without matching volume growth often reverts back toward the line — especially when it's also sitting inside the Band #1 deviation range.
Multi-timeframe bias: Run Slot 1 (Daily), Slot 2 (Weekly), and Slot 3 (Monthly) together. When price is above all three, that's confluence for a bullish bias; when the daily VWAP crosses back below the weekly, that's an early signal the shorter-term trend may be losing strength.
Reacting to a specific move: Use the Custom Anchor to mark the VWAP starting from a major swing low or a specific news candle — this shows you the volume-weighted average price of everyone who has traded since that exact point, which is often more relevant than a session-based VWAP when you're tracking a specific move.
Trading real institutional levels on Forex/CFD: Enable External Futures Volume with Auto Detect on a symbol like XAUUSD — the VWAP and its bands now reflect real Gold futures volume instead of your broker's synthetic tick count, which matters most exactly when the two diverge.
(Configuration walkthroughs and chart examples for each of these scenarios below.)
♦ Credits
Original inspiration drawn from the standard institutional VWAP concept and Auction Market Theory. Extended and combined by RealSebastianMoya / MOYA Organization into a unified multi-mode VWAP engine with real futures volume normalization — an original build, not a modification of a third-party script.
Licensed under Mozilla Public License 2.0.
Open-source script

Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.
Feragatname
Bilgiler ve yayınlar, TradingView tarafından sağlanan veya onaylanan finansal, yatırım, alım satım veya diğer türden tavsiye veya öneriler anlamına gelmez ve teşkil etmez. Kullanım Koşulları bölümünde daha fazlasını okuyun.