
AMAZON
9 - 13 May
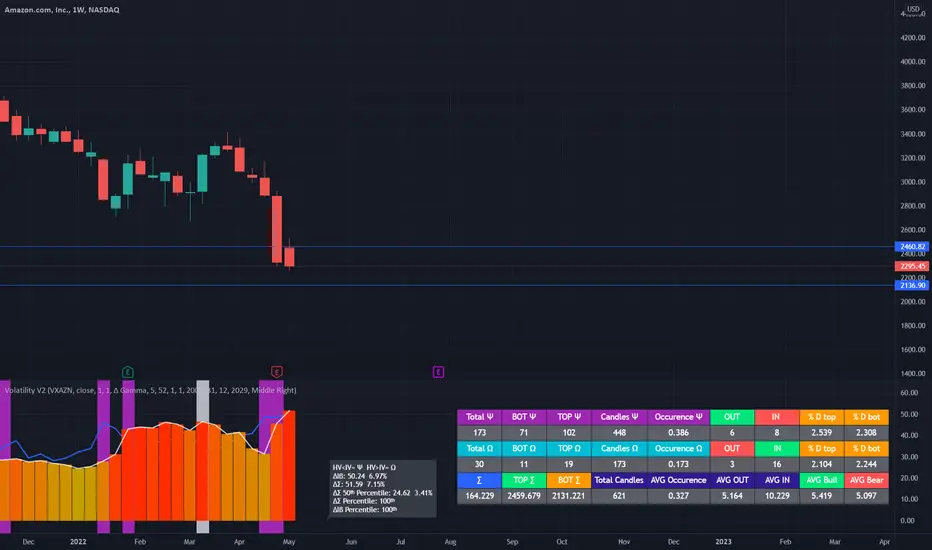
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131
9 - 13 May
The weekly VXAZN-> Volatility Index for AMAZON
Implied = 50.24
In this we have to standard it for weekly session
39.02 / sqrt(52-> 52 weeks in a year) = 6.97%
My historical product is telling me with 1x coficient that the expected movement for this week
E Volatility = 51.59 / sqrt(52) = 7.15%
With this data, from my calculations, when EV > VIX, there were a 83% chance that the market
stay within the bottom and top created with the ranged from the E Vol
So for next week this range for us is going to be
TOP - 2460
BOT - 2131

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。