
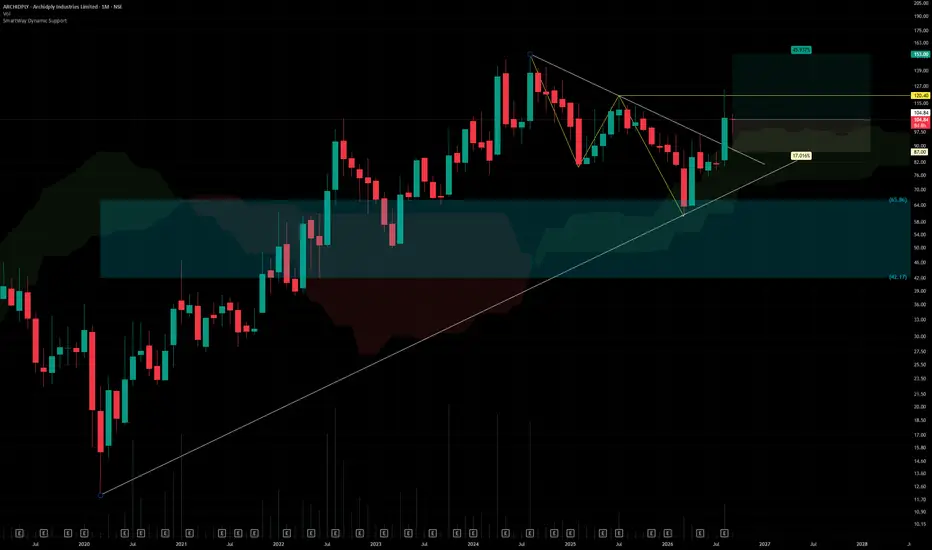
## Archidply Industries Ltd. (CMP ₹105.00, NSE: ARCHIDPLY)
**The SmartWay Research Desk | 22 September 2026**
A Bengaluru‑based building materials company, incorporated in 1976. Archidply Industries manufactures **plywood, blockboards, decorative laminates, and pre‑laminated boards**, catering to housing, furniture, and interior design sectors. The company has a strong distribution network across India and exports to select international markets.
**Promoter Holding (Jun 2026):** **Archidply Group (Dugar Family) — ~62.4% stake (no pledges)**
---
### FY22–FY26 Snapshot
- **Revenue Growth:** FY26 revenue ₹842 Cr vs ₹742 Cr in FY25 (+13.5% YoY). → **Good**
- **Net Profit:** FY26 PAT ₹72 Cr vs ₹62 Cr in FY25 (+16.1% YoY). → **Good**
- **Operating Margin:** FY26 EBITDA ₹142 Cr, margin 16.9% vs 16.2% last year (+70 bps). → **Good**
- **Equity Capital:** Stable, face value ₹10. → **Good**
- **Dividend Policy:** Dividend ₹1.50/share declared for FY26. → **Neutral/Good**
- **Asset Building:** Investments in **laminate expansion and MDF boards**. → **Good**
- **Sales:** Strong demand from **housing and furniture sectors**. → **Good**
- **Expense:** Timber and resin costs remain elevated. → **Neutral/Good**
- **EPS:** FY26 EPS ₹12.25 vs ₹10.55 last year (+16.1%). → **Good**
---
### Institutional Interest & Ownership Trends (Jun 2026)
- **Promoter Holding:** ~62.4% (no pledges)
- **FII Holding:** ~2.2%
- **DII Holding:** ~4.6%
- **Retail & Others:** ~30.8%
---
### Strategic Moves & Innovations
- Expansion in **decorative laminates and MDF boards**.
- Focus on **eco‑friendly plywood and sustainable timber sourcing**.
- Partnerships with **architects and builders for premium projects**.
- Diversification into **interior design solutions and modular furniture boards**.
---
### Cash Flow & Balance Sheet Strength
- Market cap ~₹1,020 Cr.
- Debt‑to‑equity ratio ~0.42 (moderate leverage).
- Book value per share ₹82.00; P/B ~1.3.
- EPS (TTM) ₹12.25; P/E ~8.6.
---
### Risk Factors
- Low **P/E ratio ~8.6**, valuations attractive.
- Dependence on **housing and infra demand cycles**.
- Exposure to **timber price volatility and import restrictions**.
- Competition from Century Plyboards, Greenply Industries, and Kitply.
---
### Investor Takeaway
Archidply Industries has delivered **steady FY26 performance**, supported by laminate expansion, MDF demand, and housing sector growth. With strong promoter backing (Dugar Family, 62.4% stake), dividend payouts, and leadership in decorative laminates, Archidply remains a **small‑cap building materials play**. At CMP ₹105.00, valuations are **attractive (P/E ~8.6, P/B ~1.3)**, reflecting growth potential with manageable risks.

Sucrit.D.Patil
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
Sucrit.D.Patil
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。