
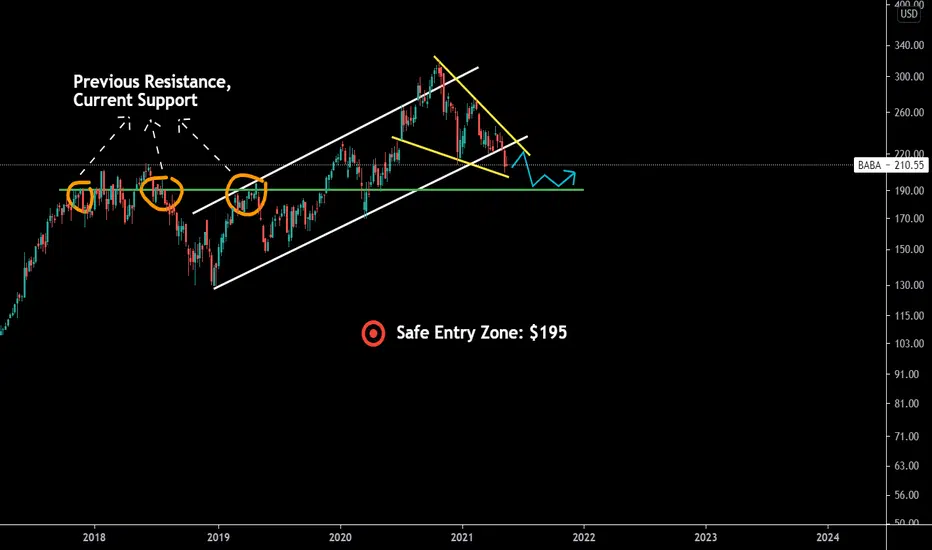
-As of Wednesday, Alibaba is down nearly 33% from its late October peak despite showing robust growth rates.
-The company suffered one of its worst earnings in Q1, with solid performance eclipsed by a hefty Chinese fine.
-From behind a cloud of negative headlines, Alibaba continues to shine as a fast-growing, profitable company with China’s backing.
-The most recent blow was its Q1 earnings report, in which the company reported a roughly $800 million loss, its first-ever as a public company.
-BABA is substantially undervalued and the threats to its success are exaggerated.
Our Opinion:
BABA is oversold but with the given economic volatility and tech sector crash, a safe entry zone can be seen at around $195.

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。