
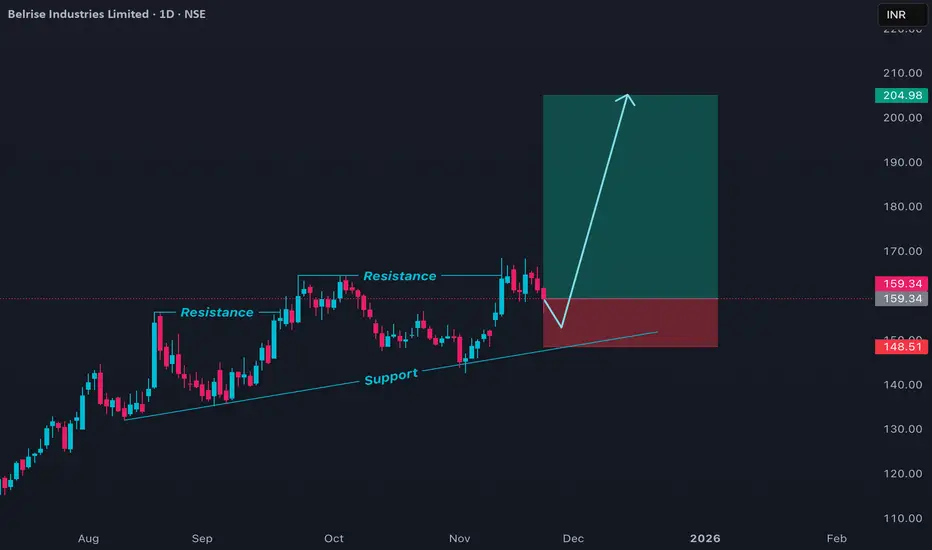
Short to Medium Term (6–12 months): Belrise looks attractive for a growth play, especially if it executes on its capacity expansion and leverages its OEM relationships.
Entry could be considered on a pull-back to strong support or on a breakout above key resistance (~₹ 180-185).
Initial downside risk is mitigated by its improving balance sheet, but growth execution needs to be monitored.
Long Term (3-5 years): If Belrise sustains its revenue growth, scales production, and builds strong profitability, it could become a significant auto-ancillary play — especially if EVs or structural auto demand expand.
Entry could be considered on a pull-back to strong support or on a breakout above key resistance (~₹ 180-185).
Initial downside risk is mitigated by its improving balance sheet, but growth execution needs to be monitored.
Long Term (3-5 years): If Belrise sustains its revenue growth, scales production, and builds strong profitability, it could become a significant auto-ancillary play — especially if EVs or structural auto demand expand.

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。