
Market Performance and Recent Momentum
In the latest trading session, shares of Jabil Inc. (JBL) advanced +2.18% to close at $218.72. This performance notably outpaced the broader market, with the S&P 500 gaining a modest 0.11%. The tech-focused Nasdaq Composite appreciated 0.22%, while the Dow Jones Industrial Average experienced a slight decline of 0.07%. Jabil's positive move suggests investor confidence ahead of its upcoming earnings report, potentially reflecting positioning based on anticipated strong results.
Despite this daily outperformance, Jabil's stock has faced headwinds over the past month, declining 1.88%. This decline has underperformed relative to both its sector peers and the broader market: the Computer and Technology sector fell 1.07%, while the S&P 500 posted a marginal gain of 0.08% over the same period. This recent weakness may indicate sector-specific concerns or profit-taking ahead of earnings, setting the stage for a potentially pivotal quarterly report.
Upcoming Earnings: A Catalyst for Reassessment
All eyes are now on Jabil's forthcoming earnings release, scheduled for December 17, 2025. The report is expected to serve as a significant catalyst, clarifying the company's trajectory amid mixed recent performance.
The consensus analyst estimate projects earnings per share (EPS) of $2.70, which would represent a substantial 35% increase compared to the same quarter last year. Revenue is forecast at $8.01 billion, marking a robust 14.6% year-over-year growth. For the full fiscal year, the Zacks Consensus Estimates point to earnings of $11.05 per share and revenue of $31.32 billion, translating to annual growth rates of +13.33% and +9.84%, respectively. These figures underscore expectations for sustained, double-digit expansion.
Analyst Sentiment and Valuation Metrics
Recent revisions to analyst estimates are a critical indicator of near-term business trends. While Jabil's consensus EPS estimate has remained unchanged over the past month, the company currently holds a Zacks Rank of #3 (Hold). This neutral rating suggests analysts are awaiting confirmation from the upcoming earnings before adjusting their outlooks more decisively. Historically, the Zacks Rank system has demonstrated a strong correlation between estimate revisions and near-term stock price movement, with its top-rated stocks (#1 Strong Buy) delivering an average annual return of +25% since 1988.
From a valuation perspective, Jabil presents a mixed picture:
Its Forward P/E ratio of 19.37 is slightly below the industry average of 19.59, indicating a marginal discount relative to peers.
However, its PEG ratio of 1.39—which factors in expected earnings growth—stands above the industry average PEG ratio of 1.02. This suggests the stock's current price may already incorporate a significant portion of its growth premium, warranting close scrutiny of whether future results can justify this multiple.
Jabil operates within the Electronics - Manufacturing Services industry, which is part of the broader Computer and Technology sector. This industry group holds an impressive Zacks Industry Rank of 7, placing it in the top 3% of all 250+ industries covered. This high ranking indicates favorable fundamental trends and positive earnings outlooks for the industry as a whole, which could provide a supportive backdrop for Jabil.
Technical Analysis and Key Levels
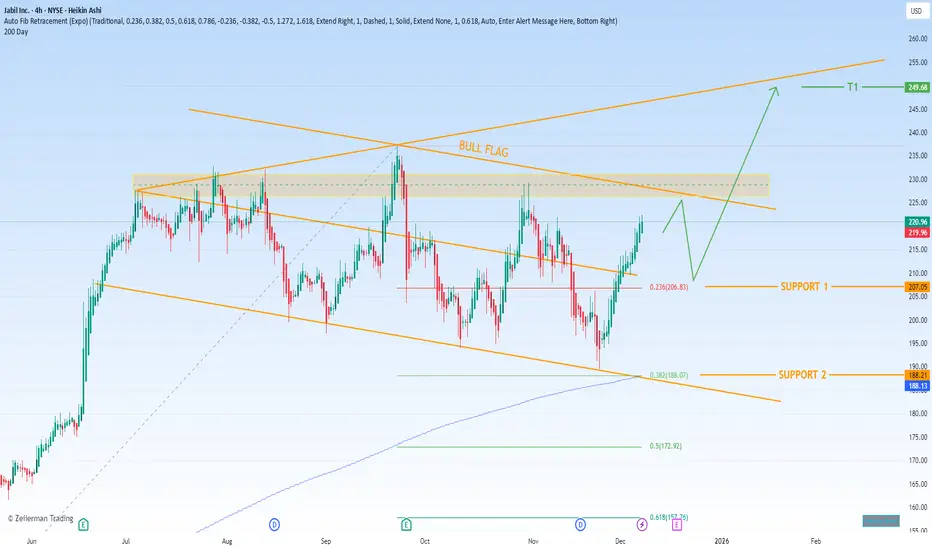
From a technical standpoint, Jabil's chart reveals defined support and resistance zones that will be critical in determining its near-term direction following the earnings release:
Primary Support: The 0.236 Fibonacci retracement level near $206.83 represents the first key support area. A hold above this level would indicate underlying strength.
Secondary Support: The 0.382 Fibonacci retracement level near $188.07 serves as a stronger, more critical support zone. A breach below the primary support could see the stock test this area, which would likely represent a more significant pullback.
Upside Target: The main take-profit resistance is identified at $250. A decisive break above this level, likely fueled by a strong earnings beat and raised guidance, would signal a resumption of the primary bullish trend and open the path for further gains.
Conclusion: A Pivotal Moment at Hand
Jabil enters its earnings report at a technical and fundamental inflection point. While the stock has shown daily strength, its monthly underperformance and elevated PEG ratio highlight investor caution. The upcoming December 17th earnings release is poised to be the decisive factor, validating or challenging the current growth narrative. Strong results that meet or exceed the high expectations for EPS and revenue growth could catalyze a breakout toward the $250 target, especially if accompanied by optimistic forward guidance. Conversely, any disappointment may see the stock retreat to test its Fibonacci support levels. Investors are thus positioned for a high-convidence move post-earnings, with the company's immediate trajectory hinging on its ability to demonstrate that its growth justifies its valuation in a competitively ranked industry.

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。