
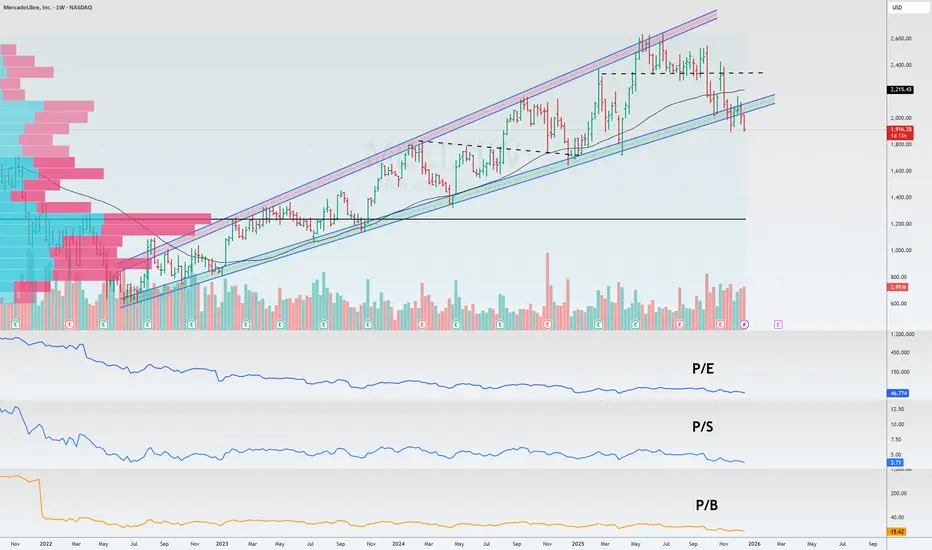
MercadoLibre is a complex ecosystem integrating a marketplace, logistics, fintech (Mercado Pago), and digital advertising.
Company Strengths
MELI's main competitive advantage lies not in its individual services, but in their deep integration, creating a "closed loop" for users.
Logistics (Mercado Envíos): Its own network of fulfillment centers, whose capacity has grown by 41% year-on-year, ensures the fastest delivery in the region.
Fintech (Mercado Pago): It is a full-fledged digital bank with 72 million monthly active users. Mercado Pago's credit card has become the most widely used on its own platform in Brazil, with over 50% of its turnover coming from external transactions, demonstrating its intrinsic value.
Advertising (Mercado Ads): The fastest-growing segment, leveraging unique, first-party data for targeting.
Operational and Financial Performance
Revenue in Q3 2025: $7.4 billion (+39% YoY)
Total Payment Volume (TPV): $71.2 billion (+41% YoY)
Loan Portfolio: $11.0 billion (+83% YoY)
Assets Under Management: $15.1 billion (+89% YoY)
At the same time, the company maintains an investment-grade credit rating (BBB- from Fitch), providing access to affordable capital.
Weaknesses and Risks:
Credit Risks and Profit Pressure
The most significant risk comes from the fintech segment. Rapid loan portfolio growth (+83%) is outpacing revenue growth, and doubtful debt provisions for the first nine months of 2025 increased by 58%. This directly impacts net profit, which grew by 13% significantly below revenue growth (+37%).
Net interest margin after deductions (NIMAL) decreased by 320 basis points to 21%. Investors rightly fear that aggressive lending expansion could lead to a wave of defaults in the event of a macroeconomic downturn.
Margin compression due to strategic investments🔎
Company Strengths
MELI's main competitive advantage lies not in its individual services, but in their deep integration, creating a "closed loop" for users.
Logistics (Mercado Envíos): Its own network of fulfillment centers, whose capacity has grown by 41% year-on-year, ensures the fastest delivery in the region.
Fintech (Mercado Pago): It is a full-fledged digital bank with 72 million monthly active users. Mercado Pago's credit card has become the most widely used on its own platform in Brazil, with over 50% of its turnover coming from external transactions, demonstrating its intrinsic value.
Advertising (Mercado Ads): The fastest-growing segment, leveraging unique, first-party data for targeting.
Operational and Financial Performance
Revenue in Q3 2025: $7.4 billion (+39% YoY)
Total Payment Volume (TPV): $71.2 billion (+41% YoY)
Loan Portfolio: $11.0 billion (+83% YoY)
Assets Under Management: $15.1 billion (+89% YoY)
At the same time, the company maintains an investment-grade credit rating (BBB- from Fitch), providing access to affordable capital.
Weaknesses and Risks:
Credit Risks and Profit Pressure
The most significant risk comes from the fintech segment. Rapid loan portfolio growth (+83%) is outpacing revenue growth, and doubtful debt provisions for the first nine months of 2025 increased by 58%. This directly impacts net profit, which grew by 13% significantly below revenue growth (+37%).
Net interest margin after deductions (NIMAL) decreased by 320 basis points to 21%. Investors rightly fear that aggressive lending expansion could lead to a wave of defaults in the event of a macroeconomic downturn.
Margin compression due to strategic investments🔎

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。