
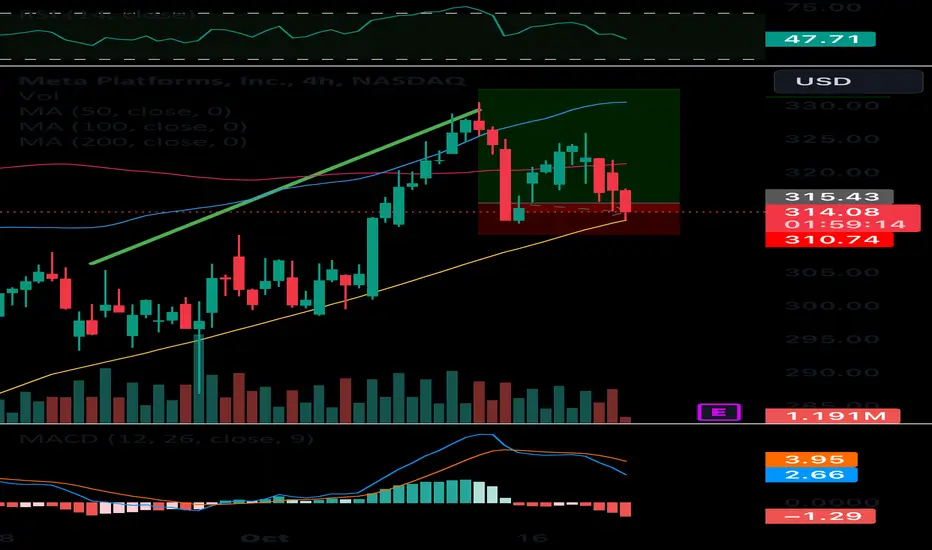
Meta Platforms (META) is showing extremely high implied volatility in the lead-up to its earnings announcement on Wednesday.
There is also significant volatility skew, with short-term options showing much higher implied volatility than long-term options.
One way to take advantage of this skew is via a diagonal put spread. This option strategy is an advanced strategy because it utilizes options over different expiration periods and different strike prices.
e risk on the trade is on the downside, with a potential maximum loss of $995. This is calculated by taking the difference in the spread (10) multiplied by 100 and factoring in the cost (5).
The maximum potential gain is around $1,035. It would occur if Meta stock closes right at 300 on Oct. 27.
The trade has a nice profit zone between 280 and 370.
If Meta stock stays between these values, the trade should do well. The main risk is if the stock drops below 280.
There is also significant volatility skew, with short-term options showing much higher implied volatility than long-term options.
One way to take advantage of this skew is via a diagonal put spread. This option strategy is an advanced strategy because it utilizes options over different expiration periods and different strike prices.
e risk on the trade is on the downside, with a potential maximum loss of $995. This is calculated by taking the difference in the spread (10) multiplied by 100 and factoring in the cost (5).
The maximum potential gain is around $1,035. It would occur if Meta stock closes right at 300 on Oct. 27.
The trade has a nice profit zone between 280 and 370.
If Meta stock stays between these values, the trade should do well. The main risk is if the stock drops below 280.

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。