
NCCW – Project Backlog vs. Margin Compression 📉🏗️
The Reality: I see a "Mid-Cap Contractor" currently stuck in a cooling cycle. 🌬️
While 2024 was stellar, the FY 2025 results show an 11.4% decline in net profit to EGP 60.35 million.
The story here is a "Margin Pinch" revenue was stable at EGP 348.7M, but domestic rising costs for materials and overhead are eating the bottom line. 🩹🏗️
The Regional Pivot: I note the company is looking outside for growth, recently signing a EUR 46M agreement in Uganda. 🌍
This expansion is vital because domestic margins are suffering.
However, I find the EPS of 0.29 EGP (down from 0.32 EGP) reflects the current struggle to maintain efficiency at home.
The Cash Flow Hurdle: I observe that cash conversion is tight.
NCCW is carrying significant "Work in Progress" on the balance sheet, a typical lag in civil works where milestones haven't yet turned into liquid cash.
While I appreciate that the earnings are 100% operational with no "one-off" fluff, the reliance on short-term credit to fund the project backlog is putting pressure on the debt-to-equity profile. ⚓💸
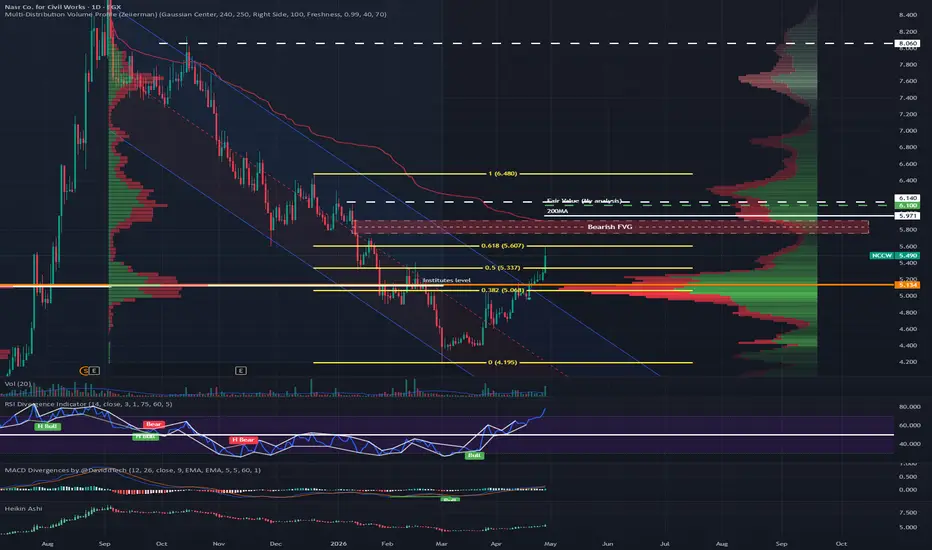
The Valuation: I find the 6.10 EGP Final Target leaves no meat on the bone.
By applying a premium 19.0x P/E to account for their historical "Zero-Debt" reputation and adding an asset strength premium for their EGP 951M book value, the target is technically sound but offers no upside from current interest levels. 🎯⚖️
Sharia Status: ❌ Non-Compliant.
I confirm that NCCW fails the quantitative screens for the EGX33 Shariah Index (April 2026).
The primary hurdles are the Interest Income, which frequently breaches the 5% purification threshold. ☪️🚫
Technical Analysis:
The Waiting Game – I see no immediate trigger. 🎢🧗
The Resistance: I've identified 6.14 as the critical level.
Since my fair value is 6.10, the price needs to break above this threshold to signal a new bullish trend that is actually worth trading. 🏹🧱
Verdict: I classify NCCW as a "Technical Pass." 🏗️🏎️
The fair value is too close to the current market price to justify the risk of high accruals and a declining bottom line.
I will wait for a structural change in earnings before looking at this stock again. 🛡️🔝
If I like my posts, I follow and boost 🙌
🎁 Get a $15 discount on your next subscription:
🔗 tradingview.com/pricing/?share_your_love=mnmabroukw36ix ✨💸

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。