
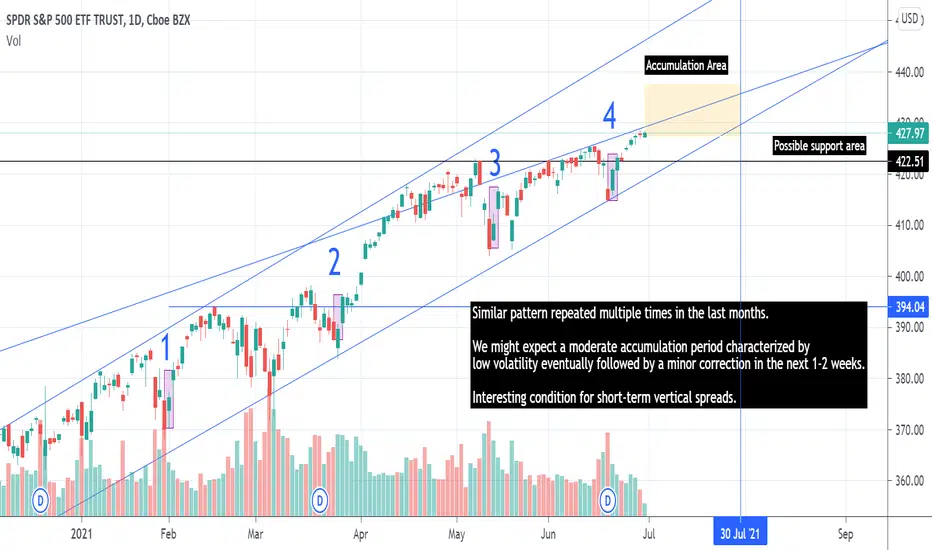
Notice the repetitive pattern on SPY (1 day correction followed by 2 days of strong recovery and a period of consolidation with low volatility. We are in a really low volatility environment. Options prices are low but there are still nice opportunities to collect premium around 16-delta strikes.
Implied Volatility: 11.41%
Historical Volatility: 9.48%
IV Percentile: 3%
IV Rank: 4.34%
IV High: 35.75% on 10/28/20
IV Low: 10.31% on 06/25/21
Implied Volatility: 11.41%
Historical Volatility: 9.48%
IV Percentile: 3%
IV Rank: 4.34%
IV High: 35.75% on 10/28/20
IV Low: 10.31% on 06/25/21

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。