DXY Monthly Return (+3M Lead)
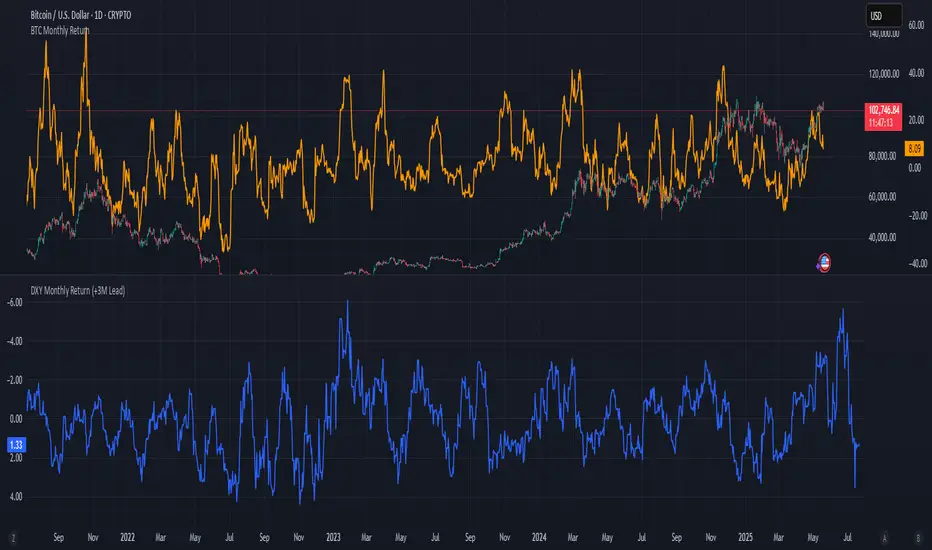
This indicator calculates the rolling monthly return (based on 21 trading days) for the U.S. Dollar Index (DXY), applying a +3-month forward shift (lead) to the series.
It is designed to help visualize the leading effect of USD strength or weakness on other macro-sensitive assets — particularly Bitcoin and crypto markets, which often react to changes in global dollar liquidity with a lag of approximately 10 weeks.
Note: This script does not invert the values directly. To match the inverted Y-axis visual used by Steno Research — where negative USD returns are displayed at the top — simply right-click the Y-axis in the chart panel and select “Invert Scale.”
💡 Use this tool for macro trend analysis, early crypto signal generation, or studying inverse correlations between USD and risk assets.
Source logic: Steno Research, Bloomberg, Macrobond.
It is designed to help visualize the leading effect of USD strength or weakness on other macro-sensitive assets — particularly Bitcoin and crypto markets, which often react to changes in global dollar liquidity with a lag of approximately 10 weeks.
Note: This script does not invert the values directly. To match the inverted Y-axis visual used by Steno Research — where negative USD returns are displayed at the top — simply right-click the Y-axis in the chart panel and select “Invert Scale.”
💡 Use this tool for macro trend analysis, early crypto signal generation, or studying inverse correlations between USD and risk assets.
Source logic: Steno Research, Bloomberg, Macrobond.

免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。