OPEN-SOURCE SCRIPT
已更新 Simple RSI Strategy - Rule Based Higher Timeframe Trading
HOW IT WORKS
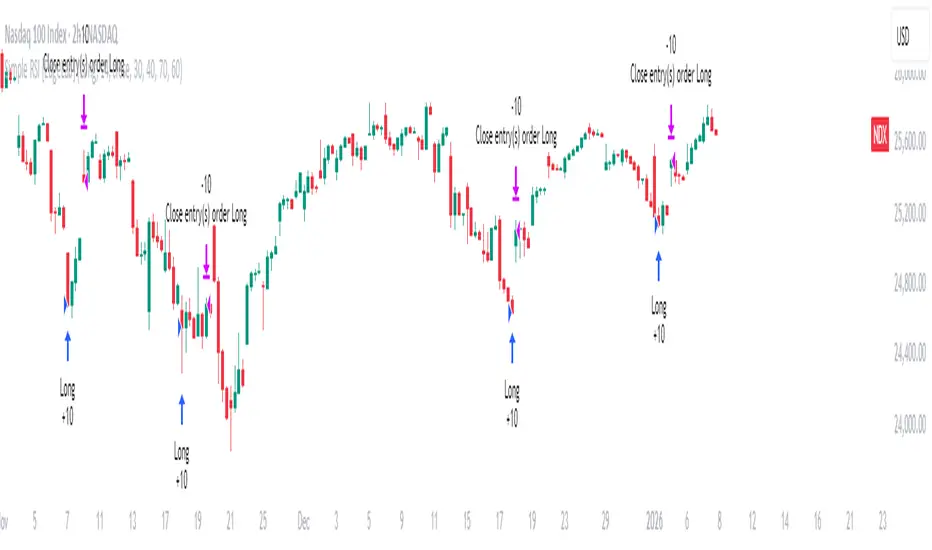
With the default settings, the strategy buys when RSI reaches 30 and closes when RSI reaches 40.
That’s it.
A simple, rule-based mean reversion strategy designed for higher timeframes, where market noise is lower and trading becomes easier to manage.
Core logic:
- Long when RSI moves into oversold territory
- Exit when RSI mean-reverts upward
- Optional short trades from overbought levels
- One position at a time (no pyramiding)
No filters.
No discretion.
Just clear, testable rules.
MARKETS & TIMEFRAMES
This strategy is intended for:
- Indices (Nasdaq, S&P 500, DAX, etc.)
- Liquid futures and CFDs
- Higher timeframes: 2H, 4H and Daily
The published example is Nasdaq (NDX) on the 2-hour timeframe.
Higher timeframes are strongly recommended.
HOW TO USE IT
- Apply the strategy on a higher timeframe
- Adjust RSI levels per market if needed
- Use TradingView alerts to avoid constant screen-watching
- Focus on execution, risk control, and consistency
This strategy is meant to be a building block, not a complete trading business on its own.
For long-term consistency, it works best when combined with other uncorrelated, rule-based systems.
IMPORTANT
- This is not financial advice
- All results are historical and not indicative of future performance
- Always forward-test and apply proper risk management
For additional notes, setups and related systems, visit my TradingView profile page.
發行說明
Added optional stop loss and take profit settings based on ATR.發行說明
Added optional stop loss and take profit settings based on ATR.開源腳本
秉持TradingView一貫精神,這個腳本的創作者將其設為開源,以便交易者檢視並驗證其功能。向作者致敬!您可以免費使用此腳本,但請注意,重新發佈代碼需遵守我們的社群規範。

Rule-based trading strategies for higher timeframes.
Free newsletter with strategies & research 👇
subscribepage.io/edgelab-news
Free newsletter with strategies & research 👇
subscribepage.io/edgelab-news
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。
開源腳本
秉持TradingView一貫精神,這個腳本的創作者將其設為開源,以便交易者檢視並驗證其功能。向作者致敬!您可以免費使用此腳本,但請注意,重新發佈代碼需遵守我們的社群規範。
Rule-based trading strategies for higher timeframes.
Free newsletter with strategies & research 👇
subscribepage.io/edgelab-news
Free newsletter with strategies & research 👇
subscribepage.io/edgelab-news
免責聲明
這些資訊和出版物並非旨在提供,也不構成TradingView提供或認可的任何形式的財務、投資、交易或其他類型的建議或推薦。請閱讀使用條款以了解更多資訊。