Adaptive Market Regime MapAdaptive Market Regime Map is a chart-overlay context tool that separates directional conditions from volatility conditions. It is designed to help traders describe the current market environment without presenting buy or sell signals.
WHAT IT SHOWS
The indicator organizes market context into two layers:
• Directional regime: Bullish, Bearish, or Neutral
• Volatility state: Compressed, Normal, or Expanding
A layered corridor is plotted around an adaptive equilibrium line. Its width responds to ATR, while its color and intensity reflect the current directional regime and measured trend strength.
In bullish conditions, the lower half of the corridor is emphasized as support context. In bearish conditions, the upper half is emphasized as resistance context. These areas are descriptive context zones, not fixed support or resistance levels and not trade-entry signals.
HOW IT WORKS
The directional engine combines:
• the distance between a fast EMA and the equilibrium EMA, normalized by ATR;
• the slope of the equilibrium EMA, also normalized by ATR;
• path efficiency, calculated from net movement relative to total movement over the selected window.
The resulting directional score is bounded and compared with the Trend Threshold to classify the market as Bullish, Bearish, or Neutral.
The volatility engine compares current ATR with a moving baseline of ATR:
• below the Compression Ratio: Compressed
• above the Expansion Ratio: Expanding
• between both thresholds: Normal
The dashboard displays the current regime, normalized strength, volatility state, and the number of bars spent in the current directional regime.
HOW TO USE IT
Use the map as a context filter alongside your own analysis:
• Bullish indicates persistent positive directional structure.
• Bearish indicates persistent negative directional structure.
• Neutral indicates that directional strength is below the selected threshold.
• Compressed indicates volatility below its recent baseline.
• Expanding indicates volatility above its recent baseline.
The corridor can also provide visual context around the equilibrium line. Price moving outside the corridor does not, by itself, constitute a breakout or reversal signal.
INPUTS
Regime Engine
• Fast Length: Period of the faster EMA used in directional separation.
• Equilibrium Length: Period of the central EMA used for the corridor.
• Slope Lookback: Bars used to measure the equilibrium slope.
• Efficiency Length: Window used to compare net movement with total path movement.
• ATR Length: ATR period used for normalization and corridor width.
• Volatility Baseline: Window used for the rolling ATR baseline.
• Spread Weight and Slope Weight: Relative contribution of both directional components.
Classification
• Trend Threshold: Minimum absolute directional score required for a bullish or bearish regime.
• Compression Ratio: ATR-to-baseline ratio below which volatility is classified as compressed.
• Expansion Ratio: ATR-to-baseline ratio above which volatility is classified as expanding.
Regime Corridor
• Inner Zone ATR and Outer Zone ATR: Width of the two corridor layers.
• Show Outer Context Zone: Displays or hides the lighter outer layer.
• Show Equilibrium Line: Displays or hides the central line.
• Color Transition Bars: Controls how quickly a new regime color reaches full intensity. This affects presentation only.
• Tint Candles By Regime and Tint Chart Background: Optional visual context, disabled by default.
State Changes
• Label Confirmation Bars: Number of persistent state bars required before a label is displayed.
• Same-Label Minimum Distance: Minimum distance between labels of the same type.
• Neutral labels are optional and disabled by default.
ALERTS
The script provides five alert conditions:
• Market Regime Changed
• Bullish Regime Started
• Bearish Regime Started
• Compression Started
• Expansion Started
Alerts are confirmed on bar close by default. Label confirmation is separate from alert timing, so the optional label delay does not delay the corresponding regime alert.
REALTIME AND REPAINTING BEHAVIOR
The script does not use higher-timeframe requests, future data, offsets into the future, or lookahead logic. Historical classifications are calculated from information available on each bar.
On an open realtime bar, price, ATR, the corridor, and the displayed regime can change as new ticks arrive. With Confirm Alerts On Bar Close enabled, alerts trigger only after the bar is confirmed. This is the recommended setting for stable alert behavior.
LIMITATIONS
• This is an indicator, not a strategy or automated trading system.
• It does not predict future price movement.
• Bullish and bearish states are contextual classifications, not trade recommendations.
• The corridor provides volatility-scaled context and does not define fixed support or resistance levels.
• Results depend on symbol, timeframe, data quality, and selected parameters.
• Very short history can produce a warmup state until all calculations are available.
• Non-standard chart types use synthetic chart prices and may behave differently from standard OHLC charts.
ORIGINALITY
This script is an original implementation. Its distinctive contribution is the combination of an ATR-normalized directional engine, path-efficiency weighting, separate volatility classification, asymmetric regime-context zones, and a compact state dashboard in one causal chart overlay. 指標

Equalhigh EMA SignatureEqualhigh — EMA Signature v2
### User Manual
**Equalhigh — EMA Signature v2** is an adaptive statistical support indicator designed to identify the EMA that a specific asset historically respects the most.
Instead of assuming that EMA 20, 50, 100, or 200 is automatically relevant, the indicator scans a configurable range of EMA periods and determines which one has historically produced the most reliable price rebounds.
The objective is to identify the asset's own **EMA Signature**.
---
## Concept
Different securities often react to different moving-average periods.
One stock may repeatedly rebound from EMA 21, another from EMA 34, another from EMA 57.
This indicator attempts to quantify that behavior by testing many EMA candidates and ranking them according to their historical effectiveness as dynamic support.
The strongest EMA is plotted directly on the chart.
The second-best EMA can also be displayed.
---
## How It Works
For every EMA candidate, the indicator looks for historical support tests.
A valid support test requires price to approach the EMA from above and enter a tolerance zone around the EMA.
Once the EMA is touched, the indicator observes the following candles and evaluates whether price produces a meaningful rebound.
Each EMA is evaluated using several statistics:
* Number of historical tests
* Number of successful rebounds
* Hit rate
* Average rebound magnitude
* Frequency of support breakdowns
* Statistical confidence
* Sample size
The highest-ranked EMA becomes the current **EMA Signature**.
---
# EMA Signature Score
The indicator does not simply choose the EMA with the highest raw win rate.
A result such as:
**EMA 137: 2 successful rebounds out of 2 = 100%**
should not automatically beat:
**EMA 34: 23 successful rebounds out of 30 = 76.7%**
The first result has too little statistical evidence.
For this reason, Equalhigh — EMA Signature uses a composite score.
### Score structure
* **65% — Statistical reliability**
* **15% — Rebound strength**
* **10% — Sample depth**
* **10% — Support integrity**
Statistical reliability uses a **Wilson lower confidence bound**, which penalizes very small samples.
This makes the ranking significantly more robust than a simple hit-rate comparison.
---
# Main Chart Elements
## Best EMA Signature
The strongest historical EMA is plotted as the main highlighted line.
The label displays:
**EMA period**
and
**Signature Score**
Example:
> ★ EMA 34
> Score 76.8
This means EMA 34 currently has the strongest statistical support profile among all EMA periods tested.
---
## Second-Best EMA
The second-highest-ranked EMA can optionally be displayed.
This is useful because some securities do not have one unique support EMA, but rather a cluster of closely related EMA periods.
For example:
* EMA 32
* EMA 34
* EMA 38
may all rank highly.
This can indicate a broader **dynamic support zone** rather than one exact mathematical line.
---
# Top 5 Dashboard
The dashboard ranks the five strongest EMA candidates.
### EMA
EMA period being evaluated.
Example:
**34**
means EMA 34.
---
### SCORE
The Equalhigh EMA Signature Score.
Higher values indicate stronger historical evidence that the EMA acts as dynamic support.
A practical interpretation:
| Score | Interpretation |
| -------: | --------------------- |
| 75+ | Very strong signature |
| 65–75 | Strong |
| 55–65 | Moderate |
| 45–55 | Weak |
| Below 45 | Low confidence |
These levels should be interpreted comparatively rather than as absolute probabilities.
---
### TESTS
Number of historical support interactions detected for the EMA.
A larger sample generally increases confidence.
An EMA with 25–40 tests is statistically much more meaningful than one with only 3–5 tests.
---
### HIT
Percentage of historical EMA tests that produced the required rebound.
Example:
**78.6%**
means that approximately 79% of detected support tests met the selected rebound criteria.
---
### AVG
Average maximum rebound after successful EMA tests.
Example:
**+6.3%**
means successful historical tests produced an average maximum rebound of approximately 6.3% during the selected evaluation window.
---
### BREAK
Percentage of support tests where price clearly lost the EMA.
Lower is generally better.
Example:
**10.7%**
indicates relatively strong support integrity.
---
### BULL
Historical success rate when the support test occurred during the indicator's bullish market regime.
This allows the user to compare general EMA behavior with behavior during favorable market conditions.
---
# Rebound Detection
A support interaction is not counted simply because the candle touches the EMA.
The indicator checks several conditions.
### 1. Approach from above
Price must approach the EMA from above.
This is important because the indicator is specifically searching for **dynamic support**, not resistance.
---
### 2. EMA touch zone
Price does not need to touch the EMA perfectly.
A tolerance based on ATR is used.
This is more realistic than requiring exact contact because markets rarely reverse at mathematically perfect levels.
---
### 3. Support must remain valid
Price is allowed to temporarily move slightly below the EMA.
However, a sufficiently large close below the EMA is treated as a support failure.
---
### 4. Rebound confirmation
After the EMA interaction, price must rise by the selected minimum percentage within the selected evaluation window.
Example:
**Minimum rebound = 3%**
**Evaluation window = 10 bars**
A successful test requires price to produce at least a 3% rebound during the following 10 candles.
---
# Settings
## Minimum EMA
Defines the shortest EMA included in the scan.
Default:
**10**
---
## Maximum EMA
Defines the longest EMA included in the scan.
Default:
**250**
---
## EMA Step
Controls the distance between tested EMA periods.
Example:
Minimum EMA = 10
Maximum EMA = 250
Step = 5
The indicator tests:
10, 15, 20, 25, 30...250
### Recommended
Use:
**5** for fast exploration
**2** for normal use
**1** for maximum precision
A Step of 1 allows unusual signatures such as:
EMA 37
EMA 43
EMA 61
to be discovered.
---
# Statistical Lookback
Defines how much historical data is used to evaluate each EMA.
Default:
**750 bars**
On a Daily chart, this represents roughly three years of trading history.
A longer lookback provides more observations but may include outdated market behavior.
A shorter lookback adapts faster to structural changes but reduces sample size.
---
# EMA Touch Tolerance — ATR
Defines how close price must come to the EMA to qualify as a support test.
Default:
**0.20 ATR**
ATR-based tolerance automatically adapts to the volatility of the security.
This makes the indicator more transferable between low-volatility stocks and highly volatile assets.
---
# Maximum Break Tolerance — ATR
Determines how far price may close below the EMA before the support is considered broken.
Default:
**0.35 ATR**
Increasing this value allows more temporary undercuts.
Decreasing it makes support validation stricter.
---
# Rebound Evaluation Window
Number of bars available for price to confirm a rebound.
Default:
**10 bars**
On a Daily chart:
10 bars ≈ two trading weeks.
---
# Minimum Rebound %
Defines the minimum move required for an EMA interaction to be classified as successful.
Default:
**3%**
For volatile securities, a larger requirement may be appropriate.
For defensive or low-volatility securities, a smaller value may be preferable.
---
# Minimum Number of Tests
Defines the minimum historical sample required before an EMA can qualify for the ranking.
Default:
**5**
Increasing this value makes the model more selective.
For long historical datasets, values between **7 and 10** may provide stronger statistical confidence.
---
# Touch Cooldown
Prevents several consecutive candles around the same EMA from being counted as separate independent support events.
Default:
**5 bars**
Without a cooldown, one prolonged consolidation around an EMA could artificially create many support tests.
---
# Suggested Daily Settings
For most liquid equities:
| Setting | Suggested value |
| -------------------- | --------------: |
| Minimum EMA | 10 |
| Maximum EMA | 250 |
| EMA Step | 2 |
| Statistical Lookback | 750 |
| Touch Tolerance | 0.20 ATR |
| Break Tolerance | 0.35 ATR |
| Rebound Window | 10 bars |
| Minimum Rebound | 3% |
| Minimum Tests | 5 |
| Cooldown | 5 bars |
---
# Practical Workflow
A useful workflow is to start with:
**EMA 10 → 250**
**Step = 5**
This quickly identifies the broad area where the strongest EMA may exist.
For example, the results may show:
EMA 30
EMA 35
EMA 40
as the strongest group.
The user can then change:
**Step = 1**
to perform a finer scan.
The final result may reveal something such as:
> EMA 34 — Score 77
This becomes the asset's current **EMA Signature**.
---
# How to Use the Indicator
EMA Signature should generally be treated as a **support context tool**, not as a standalone buy signal.
The setup becomes more interesting when price approaches the Best EMA while other factors confirm the level.
Examples include:
* Rising volume on the rebound
* Bullish candle structure
* Relative strength improvement
* Previous horizontal support
* Gap support
* Fair Value zone
* Oversold momentum
* Positive market regime
* Higher-timeframe trend alignment
The strongest opportunities generally occur when several independent forms of support converge around the same price level.
---
# Example
Suppose the indicator identifies:
**EMA 36**
with:
* Score: 78
* Tests: 27
* Hit rate: 81%
* Average rebound: +6.4%
* Break rate: 11%
Price then falls back toward EMA 36.
This does **not** mean the stock has an 81% probability of rising.
It means that, according to the historical rules selected in the indicator, EMA 36 has produced successful rebounds in approximately 81% of comparable historical interactions.
The current market context still matters.
---
# Why the Best EMA Can Change
EMA Signature is adaptive.
The best EMA may change because:
* volatility changes,
* market regime changes,
* the stock enters a stronger trend,
* institutional behavior changes,
* historical observations are added,
* old observations leave the lookback window.
For example:
EMA 50 may dominate during a slow long-term trend.
Later, EMA 21 may become dominant during a strong momentum phase.
This is intentional.
---
# Important Statistical Considerations
Historical interactions are not fully independent events.
EMA periods are also highly correlated.
For example:
EMA 34 and EMA 35 will naturally produce similar values.
Therefore, the indicator should not be interpreted as discovering a mathematically unique "perfect EMA".
A group such as:
EMA 32
EMA 34
EMA 36
should often be interpreted as a **support family or support zone**.
---
# Limitations
The indicator is based on historical price behavior.
It cannot anticipate:
* earnings surprises,
* profit warnings,
* regulatory decisions,
* macroeconomic shocks,
* geopolitical events,
* takeover announcements,
* major fundamental changes.
A historically strong EMA can fail abruptly when market conditions change.
The model also does not prove causality.
Price may appear to react to an EMA because the EMA overlaps with another important technical or fundamental price level.
---
# Best Use
Equalhigh — EMA Signature v2 is particularly useful for:
* Pullback trading
* Trend continuation setups
* Swing trading
* Dynamic support analysis
* Finding non-standard EMA periods
* Comparing support quality between securities
* Identifying repeated institutional price behavior
* Locating potential re-entry zones after a trend pullback
---
## Final Principle
Traditional technical analysis asks:
> **Does this stock respect EMA 20, EMA 50 or EMA 200?**
Equalhigh — EMA Signature asks a different question:
> **Which EMA has this stock actually respected the most?**
The indicator then lets the historical data provide the answer.
---
**Equalhigh — EMA Signature v2**
*Adaptive EMA discovery through statistical rebound analysis.*
**Disclaimer:** This indicator is provided for research and educational purposes only. Historical statistical behavior does not guarantee future performance and should not be considered financial advice.
指標

Liquidity Levels, Sweeps & Grabs | Falcon AIDraws the liquidity pools price tends to hunt, the Previous Day and Previous Week highs and lows, and flags the two distinct ways each one gets taken.
SWEEP: price trades BEYOND the level, can hover or consolidate out there, then closes back through it over one or more candles. The slower stop-run.
GRAB: a single candle spikes a long wick past the level and snaps back inside with a small body, doji-like. Taken and rejected within one bar.
Separating the two matters because they do not look the same on a chart and do not resolve on the same timescale. Lumping them together as one generic liquidity event loses exactly the information that made the distinction worth drawing.
Each level is drawn and kept until it is taken, then marked, so you can see at a glance which pools are still sitting untouched above and below price.
Settings: which levels to draw (previous day high/low, previous week high/low), wick and body thresholds that separate a grab from a sweep, line styles, colours and labels.
This script does NOT place trades, does NOT backtest, and contains no entry, stop, target or position-sizing logic. It marks levels and the events that take them. Your entry, your risk.
Educational tool only. Not financial advice. A swept level is not a signal, and plenty of sweeps simply keep going. 指標

Opening Range Breakout + MidlineWhat this is
An opening range breakout tool that draws the range high, the range low and the
50% midline, then adds the context you need to judge whether today's range is
worth trading at all - and hit rates measured on the chart you are actually
looking at.
Most ORB indicators draw three lines and stop. The reason this one exists is
that the three lines on their own are misleading: a break of the range high is
not, by itself, evidence of a trend day. This script is built around that
problem.
Why the midline is on by default
Clean breakouts are the minority outcome. Measured on ES over a six-month
sample, price took out *both* sides of the opening range on roughly two thirds
of sessions, against roughly one sixth cleanly breaking up and one sixth cleanly
breaking down.
If both sides go more often than either side holds, then "price broke above the
range high, so it is going up" is wrong most of the time, and you need something
other than the break itself to tell you which side actually owns the session.
The 50% level is that something: it is the level a failed break falls back to,
and the level a genuine trend refuses to give back.
So the midline is drawn by default. You can turn it off under
**Midline -> Show midline (50%)**, and it has its own colour, style and width if
you would rather it stayed on but receded into the background.
What it draws
- **Range high and low**, held from the end of the opening range to the session
close, optionally extended to the right.
- **The 50% midline.**
- **A shaded range box**, either spanning just the range window or the whole
session.
- **Extension targets** projected from the broken edge at 0.5x, 1.0x, 1.5x and
2.0x the range width. Only the side that has actually broken is projected,
because targets on an untested side are clutter. 1.0x and 2.0x are on by
default.
- **Previous sessions' ranges**, five by default and up to forty, so you can see
how the instrument has been behaving lately.
The context table
**Range width** in points, as a percentage of price, and as a percentage of
ADR(14) - tagged NARROW, NORMAL or WIDE.
This matters in both directions. A range that is unusually narrow tends to break
in whichever direction noise happens to push it first. A range that is already
very wide has spent much of the day's expected movement before you are even in,
so the extension targets below it become unrealistic.
The comparison is scaled by the square root of time, so the tag stays meaningful
at any range length: a 5-minute range is expected to be about 17% of ADR, a
15-minute range about 30%, 30-minute about 42%, 60-minute about 60%. The
baseline is adjustable if your instrument opens habitually quiet or habitually
violent.
**Opening relative volume** - the volume traded inside the range window against
the average of the same window over the previous 14 sessions, tagged LIGHT,
NORMAL, ELEVATED or HIGH. Opening relative volume was the strongest single
filter in the published research on this setup, so it is shown rather than
buried.
**Session state** - FORMING while the range builds, then INSIDE, BROKE UP,
BROKE DOWN or DOUBLE BREAK, with BACK INSIDE appended when price has returned
into the range after breaking out.
The measured statistics
The bottom block is measured on the symbol and timeframe you have open, over the
last N sessions (60 by default). It is not borrowed from anywhere. Each row
carries its own sample size, because the denominators genuinely differ:
- **broke range** - of all sessions, how often price left the range at all.
- **double break** - of all sessions, how often price took out *both* sides.
This is the number that tells you how much to distrust a first break on this
instrument.
- **1x before far side** - of sessions that broke, how often the 1.0x extension
target printed before price reached the opposite extreme of the range. This is
the entry-at-the-break, stop-at-the-other-side pairing, scored honestly:
when a single bar spans both levels the bar is counted as reaching the stop,
and a session that reaches neither by the close counts as not reaching target.
- **failed to midline** - of sessions where a break failed, how often price then
reached the midline. A failed break is defined by a *close* back inside the
range; a wick back in that closes outside does not count.
Rows at or above 65% are tinted, which is a rough and widely used dividing line
between a tendency worth building a plan around and a coin flip. Treat these as
descriptive history for the symbol and timeframe in front of you. They describe
what has happened; they do not predict what will happen, and a small sample size
in the n= column means exactly what it says.
How to use it
Set **Trading session** to the instrument's real hours and **Session timezone**
to match - `0930-1600` New York for US equities and index futures RTH,
`0300-1130` London for European hours. The range is then measured forward in
wall-clock minutes from that session's first bar, so any range length works and
the two windows cannot drift out of step.
A workable reading, in order:
1. Check the range-quality tag before anything else. NARROW warns that breaks
are more likely to be noise; WIDE warns that the extension targets may be
asking for more than the day has left to give.
2. Check opening relative volume. A range formed on LIGHT volume is a weaker
reference level than one formed on HIGH volume.
3. Check the double-break rate for this symbol. If it is high, treat a first
break as provisional rather than as confirmation.
4. Watch the midline once a break fails. That is what the failed-to-midline row
is measuring.
Use 5-minute or 15-minute charts. The table warns you if your chart timeframe is
larger than the range length, or if it does not divide the range evenly - a
15-minute range on a 2-minute chart actually measures 16 minutes, which is
inherent to any bar-based range rather than a fault of this script.
Alerts
Seven alert conditions: break above the range, break below the range, failed
break (a close back inside), midline reached after a failed break, midline
crossed, and the 1x target reached above or below.
The range high, midline, low, width and opening relative volume are also
published to the Data Window, so other scripts can read them.
## What is different about this one
There is no shortage of ORB indicators. This one adds three things that are
uncommon:
1. **Measured hit rates on your own chart**, with visible sample sizes and
explicit definitions, rather than a static claim in a description. The
double-break number in particular changes how you should read a first break,
and it varies a lot between instruments.
2. **A range-quality score** that is comparable across range lengths because it
is scaled by the square root of time, instead of a fixed points or percentage
threshold that only works on one instrument at one setting.
3. **Opening relative volume**, surfaced as a first-class number because it was
the strongest filter in the research, not because it is easy to compute.
The range is also measured in wall-clock minutes from the session open rather
than from a second hardcoded session string, which is what usually breaks other
ORB scripts on futures, on non-US instruments, and on any timeframe the author
did not test.
Credits and sources
No code from other authors is used; this is written from scratch. The defaults,
however, are taken from published work rather than convention, and that work
deserves credit:
- Carlo Zarattini, Andrea Barbon and Andrew Aziz, *A Profitable Day Trading
Strategy For The U.S. Equity Market* (2024), which compared 5, 15, 30 and
60-minute opening ranges across more than 7,000 US stocks from 2016 to 2023,
and whose relative-volume stock selection is the reason opening relative volume
is displayed here.
- Carlo Zarattini and Andrew Aziz, *Can Day Trading Really Be Profitable?*,
on the 5-minute opening range applied to index ETFs.
- The published ES double-break statistics that motivate the midline being on by
default.
- A published study of 100,569 fifteen-minute opening range entries comparing
profit-target rules, in which the full 1x range projection produced the best
expectancy against the opposite range extreme as stop. This is why 1x is
enabled by default and labelled as such.
These are cited as the origin of the default settings. They are not claims about
what this indicator will do for you, and I have not independently reproduced
their results.
Limitations
- Intraday charts only.
- The statistics are limited by how much history your chart has loaded. On a
1-minute chart that can be considerably fewer sessions than the lookback you
set; the n= column tells you what you actually got.
- Intrabar sequence is unknowable from bar data. Where a single bar reaches both
a target and a stop, the statistics count the stop.
- This is a levels-and-context tool. It does not generate buy or sell signals,
it does not size positions, and nothing in it should be read as a prediction. 指標

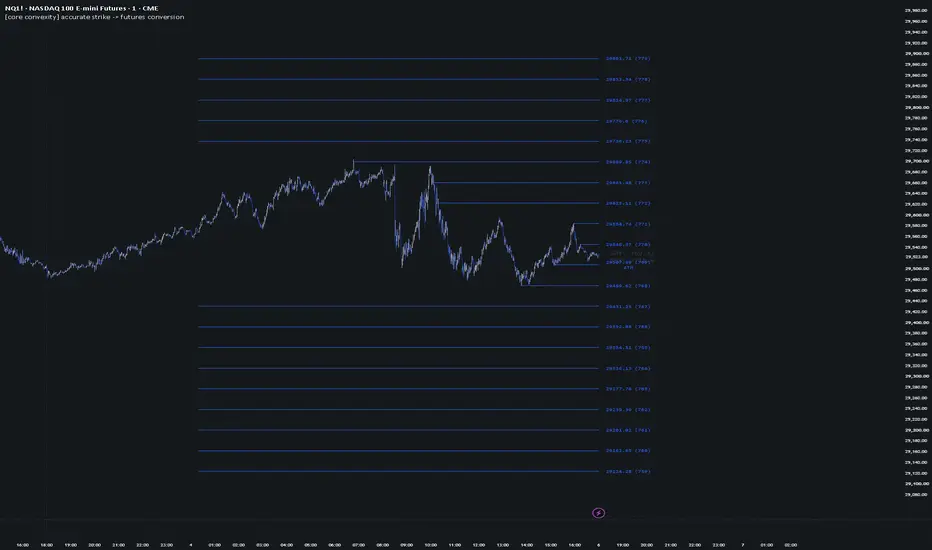
[core convexity] accurate strike -> futures conversionconverts etf/index strikes into futures levels using a live smoothed price ratio between the selected cash product and futures contract. presets cover common pairs like es/spx, es/spy, nq/ndx, nq/qqq, gc/gld and si/slv, with manual symbol selection available too.
theory
the conversion is based on the live futures / cash ratio with configurable smoothing, optional tick-size rounding and output precision. extended-session cash data is used so the relationship can continue updating outside regular equity hours.
because its smoothed its better to roughly plot on lower time frames
how to operate it
strikes can be pasted manually or generated automatically around price. batch mode supports optional names in quotes, while auto mode builds a strike grid around the implied cash price using preset or manually defined intervals.
levels can be drawn as lines or boxes (addresses for small deviation that may occur naturally). mitigated mode stops the historical extension where price previously interacted with the level, while full-left mode keeps it extended. styling, box size, labels and positioning are all configurable.
v6 also includes an optional conversion table, live two-symbol monitor and touch alerts for converted lines or zones. lower timeframes generally give the conversion more responsiveness, while higher smoothing produces steadier levels.
please stop taking it down
they keep taking this script down for the description not being good enough (???) i dont know despite me clearly explaining how to work it. anyways enjoy this along with my series of other scripts 指標

Fibonacci Cloud | Multi-Timeframe Fibonacci ScannerFibonacci Cloud stacks three independent retracement grids (short, medium, and long lookback windows) on top of each other and watches for the moments when price sits near multiple levels from multiple grids at once.
The idea is simple: a fib level that only shows up on one lookback length is easy to dismiss as coincidence, but a zone where the short-term 0.618 lines up with the medium-term 0.5 and the long-term 0.382 is a lot harder to ignore. The script counts how many of the fifteen tracked levels price is currently touching (within a configurable tolerance band) and only considers a trade when that confluence count clears your threshold.
From there, two optional filters can sharpen the signal further: an EMA trend filter (only take longs above the trend line, shorts below it) and an RSI momentum filter (skip longs when momentum is deeply negative, skip shorts when it's deeply positive). Both are off/loose by default so the confluence logic itself stays the star of the show — tighten them if you want fewer, higher-conviction trades.
Features
Three-lookback Fibonacci confluence engine (15 levels tracked simultaneously)
Adjustable confluence tolerance and minimum-overlap threshold
Optional EMA trend filter with clean directional fill
Optional RSI momentum filter (confirmation-style, not fade-style)
Long-only / short-only / both trade direction control
Fixed % stop-loss with configurable R:R take-profit
Minimal two-tone visual design — trend fill, soft confluence background tint, triangle entry markers
Built-in alert conditions for both long and short signals
Tips
Start loose (Min Confluent Levels = 1, wide tolerance) to see how many setups the confluence engine finds on your instrument, then tighten gradually rather than starting strict and wondering why trade count is low.
The three lookback lengths (default 20/50/100) are tunable — pairing a short scalping lookback with a much longer swing lookback tends to produce more meaningful confluence zones than three lookbacks bunched close together.
Try disabling the trend filter entirely on ranging instruments and re-enabling it on trending ones — this single toggle changes the strategy's character more than almost any other input.
Backtest the R:R and stop % together rather than in isolation; a looser confluence threshold usually pairs better with a tighter R:R target.
Warnings
This is a mean-reversion/confluence-zone tool, not a breakout system — it will underperform in strongly trending, low-pullback conditions.
Backtest results are historical and do not guarantee future performance. Past performance shown in the strategy tester does not account for slippage, liquidity gaps, or execution differences on your specific broker/exchange.
The looser default settings favor trade frequency over precision — verify the win rate and expectancy for your instrument and timeframe before trading it live.
This script is provided for research and educational purposes only and is not financial advice.
策略

Camarilla S6-R6 + Day # Camarilla S6–R6 + Day Type
## Short title
Camarilla S6-R6 + Day Type
---
## Description
Camarilla pivots plotted with the full six-level set (S6 through R6 plus the central pivot), using the level naming most execution platforms display, with a session-locked calculation and a dashboard that classifies the developing period as a rotation day or a breakout day.
**Levels**
All levels derive from the previous completed period's high, low and close:
Range = prior High − prior Low
PP = (H + L + C) / 3
R1 = C + Range × 1.1/12 S1 = C − Range × 1.1/12
R2 = C + Range × 1.1/6 S2 = C − Range × 1.1/6
R3 = C + Range × 1.1/4 S3 = C − Range × 1.1/4
R4 = C + Range × 1.1/2 S4 = C − Range × 1.1/2
R5 = R4 + 1.168 × (R4 − R3) S5 = S4 − 1.168 × (S3 − S4)
R6 = (High / Low) × C S6 = C − (R6 − C)
Note for anyone comparing against other Camarilla scripts: in the five-level version, the (H/L) × C calculation is labelled H5. In the six-level set used here it is R6, and R5 is the separate 1.168 extension of the R3–R4 leg. If the outer line looks misnamed against another indicator, this is why.
**Session basis — the part that usually causes mismatched levels**
Camarilla levels are only as good as the prior high, low and close feeding them, and on an intraday chart with extended hours enabled it is easy to end up mixing sessions without noticing. This script pins the calculation explicitly. The Session basis input rebuilds the data request on regular-hours data (the default, matching most execution platforms), extended-hours data, or whatever your chart is currently set to. The levels stay on that basis regardless of your chart's extended-hours toggle.
The developing period's open, high and low are requested from that same source, so both sides of every inside/outside comparison are measured on one session. The period boundary is taken from the higher-timeframe bar's own timestamp rather than the chart's calendar-day roll, which matters on extended-hours charts where the chart day rolls before the daily bar has advanced.
A Prior H/L/C row in the dashboard shows the three numbers actually being used. Check those against your broker or platform for the same date — if they match, every level below them matches by construction.
**Timeframe handling**
Auto resolves to daily levels on every intraday chart and on the daily chart itself, weekly on a weekly chart, yearly on monthly. Keeping daily pivots on the daily chart is deliberate: each daily candle is then drawn against the prior day's level set, so a run of inside and outside days reads directly off the staircase. Raise "Periods shown" to 10–20 for that view and leave it at 1–2 intraday. Daily, weekly, monthly and a free custom timeframe can also be selected manually.
**Opacity gradient**
Transparency steps down as levels move away from the pivot. The inner S3–R3 band is the most transparent so price action stays readable through it, R4/S4 and R5/S5 grow progressively more solid, and R6/S6 are the darkest and heaviest lines on the chart. Starting transparency and the per-band step are both inputs, so the gradient can be flattened or exaggerated. R and S levels have separate colour inputs.
**Day type dashboard**
Open type — where the period opened relative to the prior band. Inside S3–R3 suggests rotation and levels worth fading; between R3 and R4 (or S3 and S4) marks a gap that often reverts to the band; beyond R4/S4 flags a breakout open that should not be faded.
Range — the containment read. INSIDE when the developing high and low sit within the prior range, OUTSIDE when they engulf it, otherwise a one-sided extension.
Range vs prior — developing range as a percentage of the previous one. A contraction and expansion gauge: a low reading through the middle of the session supports mean reversion at the bands, above 100% says the session is in expansion.
Price in — which band price currently occupies, from above R6 down to below S6.
An optional background tint marks inside and outside periods on the chart itself.
**Alerts**
Crossings of R3/S3 and R4/S4 in both directions, rejection back inside the R3/S3 band, and tags of R6/S6.
**Notes on repainting**
Prior-period values use a bar offset so the levels lock in when the period closes and do not repaint. The developing period is requested without lookahead, so it updates bar by bar without using future data. That does mean the Range and Range-vs-prior rows are live reads that can change until the period closes — a day showing INSIDE at midday can finish as an outside day. When regular-hours levels are selected and the session has not opened yet, the dashboard reports that state rather than computing a range against the prior day's own numbers.
Works on any symbol and any chart timeframe at or below the pivot timeframe; a warning label appears if the chart timeframe is higher than the selected pivot timeframe.
Open source. The level maths is the standard published Camarilla set; the code is commented throughout for anyone who wants to adapt it. 指標

ATR + True RTH Day RangeRTH Range & Daily ATR Monitor
Track the regular trading session’s price range and compare it with the daily Average True Range (ATR), using a compact panel on your chart.
Panel Values
• ATR(D): Daily ATR with a configurable lookback, set to 14 periods by default.
• Range RTH: The difference between the highest and lowest prices recorded during the regular session.
• Used: The RTH range expressed as a percentage of daily ATR.
Used = RTH Range ÷ Daily ATR × 100
For example, a session range of 3.87 and a daily ATR of 6.22 produces approximately 62.23%. The calculation uses unrounded values.
Regular Session Only
The session range uses standard one-minute candles from the regular-session data feed, filtered to 9:30 a.m.–4:00 p.m., Monday through Friday, in America/New_York time. Daylight saving time is handled automatically.
Premarket and after-hours prices are excluded from the range calculation, whether extended hours are visible on the chart or hidden.
The daily ATR also uses an explicitly selected regular-session feed.
Session Tracking
At the first available RTH candle of each new session, the indicator saves the preceding session’s high and low, then resets the current range.
During RTH, the range expands as new highs or lows form. Outside RTH, the panel retains the latest available regular-session values until the next session begins.
Panel Colors
The background compares the latest RTH price with the preceding RTH session’s range:
• Green: Above the previous session’s high.
• Red: Below the previous session’s low.
• Gray: Inside the previous session’s range, equal to either boundary, or without sufficient previous-session data.
Extended-hours price movements do not change this directional comparison.
Display Options
• Always: Displays the latest available RTH information, including after the session ends.
• Only Today: Displays the panel only when its RTH data belongs to the current New York calendar date. Before today’s RTH session begins, the panel remains hidden.
Understanding the ATR Percentage
The percentage compares the session’s high-to-low range with daily ATR. It does not measure the total distance traveled by price or predict how much movement remains.
Values above 100% are possible when the session range exceeds the ATR.
ATR uses True Range, which accounts for gaps relative to the previous daily close. Range RTH measures only the session’s high minus its low. These are related but different measurements.
Timeframes and Updates
Designed for intraday charts, the indicator calculates the session range from one-minute data rather than the visible chart candles. Update timing depends on the chart timeframe and available data.
The daily ATR includes the developing daily candle and can change during the regular session. It is not a fixed previous-day ATR reference.
Purpose
A compact tool for monitoring regular-session range expansion, daily volatility, and price position relative to the previous RTH session. It does not generate trade entries, execute orders, or provide backtest results. 指標

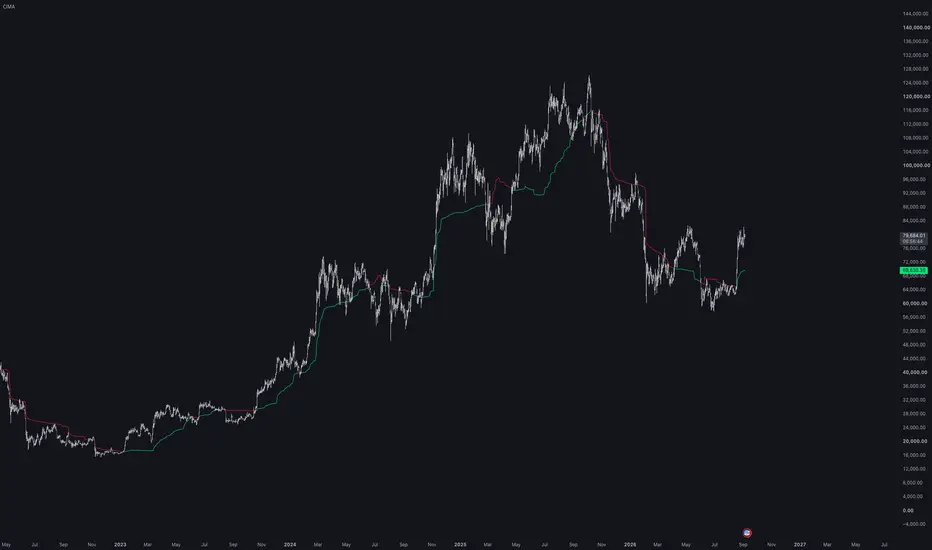
Composite Institutional Moving Average (CIMA)Composite Institutional Moving Average (CIMA)
Overview
The Composite Institutional Moving Average (CIMA) is a high-conviction cost-basis anchor designed to replace primitive volume-weighted indicators. Standard VWMAs treat every volume tick identically regardless of intent. CIMA evaluates the quality and composition of institutional order flow behind each bar.
By anchoring price action to a macro 126-period lookback, CIMA constructs a dynamic baseline weighted by intrabar cumulative volume delta (CVD) and stealth limit-order absorption.
Core Formula & Architecture
Rather than relying on raw volume alone, CIMA calculates a dynamic Composite Weight for every single candle using three distinct market mechanics:
$$\text{Composite Weight} = \vert{}\text{CVD Factor}\vert{} \times \text{Absorption Weight} \times \text{Volume}$$
* Order Flow Delta Proxy (cvdFactor): Measures intrabar buying versus selling pressure based on close position relative to high/low wicks. Directional imbalances pull the baseline toward true aggressive market orders.
* Stealth Absorption Efficiency (absorptionWeight): Measures total volume relative to candle range ($\text{volume} / \text{spread}$). Heavy volume printed inside narrow candle ranges highlights passive limit-order absorption (smart money accumulating or distributing without letting price move).
* 126-Period Macro Baseline Anchor: Applies the Composite Weight across a 126-period lookback using double-weighted VWMA logic ($\text{close} \times \text{compositeWeight}$). The 126-period setting represents exactly two quarters (6 months / semi-annual) of trading data on daily charts—the core timeframe used by institutional fund managers and execution algorithms to track semi-annual cost basis. On intraday charts, 126 bars provides a deep structural sample size that filters out high-frequency noise, ensuring the line only shifts when major institutional volume shelves are formed.
How to Read the Raw Baseline
Because CIMA remains un-smoothed, the indicator creates sharp vertical steps and flat horizontal shelves:
* Vertical Steps: Highlight points where sudden institutional volume injections or aggressive order sweeps occurred.
* Flat Horizontal Shelves: Function as dynamic Institutional Support & Resistance Floors. Expect smart money to defend these cost-basis shelves on the first retest.
* Trend Bias:
* Price > CIMA (Bright Green): Institutional buyers control the macro cost basis. Look for long continuation setups off CIMA shelf retests.
* Price < CIMA (Bright Red): Institutional sellers control the macro cost basis. Look for short continuation setups off CIMA shelf retests.
Key Features & Toggle Options
* Enable Volatility Bands ($\pm\sigma$): Displays optional standard deviation channels derived from the CIMA baseline to identify objective overbought/oversold value area extremes (Disabled by default for a clean chart).
* Multi-Timeframe (MTF) Engine: Toggle higher timeframe execution (e.g., Daily CIMA overlaid on a 15m chart) without code lag or repainting errors.
Default Inputs
* Institutional Lookback Length: 126 (Optimized for semi-annual structural anchoring).
* Enable Order Flow Delta Factor: True
* Enable Stealth Absorption Factor: True
* Best Applied To: Equities, Crypto, Futures, and Forex across any timeframe.
Disclaimer
This indicator is designed for educational and informational purposes only and does not constitute financial or investment advice. Past performance is no guarantee of future results. Financial market trading involves substantial risk of loss, and traders should perform their own independent technical analysis and manage their risk strictly before executing trades. 指標

Percent Line/Box Toolkit
Percent Line/Box Toolkit is an overlay tool that draws horizontal lines and rectangles at percentage distances from the current price.
It is built for anyone who reads a chart in percentage terms rather than in absolute prices: eight percent above the market means the same thing on any symbol and at any price level, while a fixed price distance has to be worked out again whenever the price moves or the instrument changes.
Every drawing is anchored to the latest close, and its vertical position is expressed as a percentage of that close, so the whole set travels with the market instead of standing still.
The horizontal geometry of each drawing is measured in bars of a reference timeframe chosen separately for that drawing, rather than in bars of the chart.
Six lines and four rectangles are available, each one positioned, sized, labeled and colored independently of the others.
Line (present six times, Line 1 to Line 6, each instance identically structured)
Switch, label text, label size: The switch turns the line on or off, the text field holds the label, and the dropdown sets the size it is drawn in. An empty text field means no label.
Level (%): Vertical position of the line, as a percentage of the current close.
Offset (Bars): Horizontal position, measured in bars. Positive values move the line to the left, negative values to the right.
Length (Bars): Width of the line, measured in bars.
Reference Timeframe: Offset and length are counted in bars of this timeframe. If it is left empty, the chart's own timeframe is used.
Style, width, color: The line style (solid, dotted or dashed), the thickness of the line, and its color.
Box (present four times, Box 1 to Box 4, each instance identically structured)
Switch, label text, label size: The switch turns the box on or off, the text field holds the label, and the dropdown sets the size it is drawn in. An empty text field means no label.
Upper (%): One edge of the box, as a percentage of the current close.
Lower (%): The other edge, also as a percentage of the current close. The two fields can be filled in either order.
Offset (Bars): Horizontal position, measured in bars. Positive values move the box to the left, negative values to the right.
Length (Bars): Width of the box, measured in bars.
Reference Timeframe: Offset and length are counted in bars of this timeframe. If it is left empty, the chart's own timeframe is used.
Border width, border color, fill color: The thickness of the outline, its color, and the color of the area inside. A border width of zero leaves the box without an outline.
Every enabled line is drawn as a horizontal segment at its percentage level, and every enabled box as a rectangle spanning its two levels.
Everything is rebuilt from the current close on each new bar, so the drawings follow the price instead of staying where they were put.
Nothing remains on past bars: there is no history to scroll back through, only the state the chart is in right now.
The two edges of a box are sorted before it is drawn, so the higher value always becomes the top edge and the order in which they are entered makes no difference.
Offset shifts a drawing along the time axis: positive values move it left into the existing bars, negative values right into the empty space beyond the last bar.
Because offset and length count bars of the reference timeframe rather than bars of the chart, a drawing holds its size when the chart timeframe is changed; a line 50 bars wide on a 4-hour reference stays that wide whether the chart shows 5-minute or daily bars.
On instruments that do not trade continuously the time axis runs through the closed periods as well, so a drawing covers its length in calendar terms rather than in visible bars and appears shorter than the bar count suggests.
Any drawing can carry a label at its right-hand end, drawn in the color of the line or of the box border; it appears as soon as its text field is filled and disappears when the field is cleared, without affecting the drawing itself.
This indicator is intended solely for market analysis and does not constitute investment advice or a guarantee of success.
Use it at your own discretion and risk; past results are not indicative of future performance.
指標

Algogram Trend IdentifierAlgogram Trend Identifier (ATI) is an advanced oscillator designed to identify trend direction, momentum strength, volatility shifts, and potential reversal points. It uses Arnaud Legoux Moving Average (ALMA) applied to percentage price changes, wrapped in Root Mean Square (RMS) dynamic bands, and features built-in divergence detection.
Key Features:
* ALMA Percentage Change Engine: Smooths price percentage changes using ALMA to eliminate lag while reducing noise.
* Dynamic RMS Volatility Bands: Automatically adjusts band boundaries based on recent volatility to define overbought, oversold, and trend continuation zones.
* Preset Profiles: Built-in presets for 5m, 15m, 30m, 1h, and Daily timeframes that automatically apply optimized calculation parameters.
* Divergence Detection Engine: Detects regular bullish and bearish divergences between price and oscillator fractals, drawing custom lines and dots.
* Consolidation Detection: Visual thresholds highlight periods of market squeezes and low-volatility consolidation.
* Multiple Alert Triggers: Pre-configured alert conditions for threshold crossings, zero-line breaches, trend switches, and divergences.
How It Works:
1. Trend Calculation: Measures smoothed percentage change via ALMA to establish a core directional oscillator line.
2. Dynamic RMS Bands: Calculates upper and lower bands using root mean square volatility to gauge strong directional breakout momentum versus consolidation ranges.
3. Trend States:
* Green Zone: Strong bullish momentum above the upper RMS band.
* Red Zone: Strong bearish momentum below the lower RMS band.
* Consolidation: Oscillator activity within inner threshold bounds indicates sideways ranges.
4. Divergence Signals: Automatic detection plots dots and trendlines whenever price makes higher highs/lower lows that diverge from oscillator peaks.
Inputs and Settings:
* Preset: Quickly switch between 5 Minute, 15 Minute (Default), 30 Minute, 1 Hour, and Daily parameters.
* Trend Calculation Settings: Adjust ALMA length, offset, sigma, and smoothing bars.
* Threshold Settings: Custom upper/lower boundary levels (Default: 60 / -60).
* Consolidation Settings: Adjust upper and lower thresholds for identifying low volatility (Default: 20 / -20).
* Divergence Settings: Toggle divergence visualization, lookback length, line thickness, and shape styles.
How to Use:
* Trend Continuation: Trade in the direction of the color-coded oscillator when it expands outside the RMS bands.
* Range / Reversal Trading: Look for divergence dots near extreme upper or lower thresholds to anticipate trend exhaustion or reversals.
* Squeeze / Expansion: Watch for the oscillator breaking out of inner consolidation thresholds after a low-volatility period.
指標

Relative Correlation RegimeA general-purpose tool for measuring the rolling relationship between two markets.
The indicator calculates correlation from price returns and classifies the current relationship into five regimes: Strong Positive, Positive, Neutral, Negative, and Strong Negative.
I designed it as a simple way to observe when relationships between markets strengthen, weaken, or diverge.
It can be applied across forex, commodities, indices, and crypto markets.
This indicator is intended for market research and analysis, not as a standalone trading signal. 指標

Implied Market StructureYou have seen the day. The S&P 500 closes green, the financial press calls it a rally, and half the names in a typical portfolio did not participate. Or the index is flat while a handful of stocks you actually own move several percent. The cash print of SPX is a weighted average. It can look healthy while the market underneath is narrow, and it can look dull while single names are already running. Breadth indicators catch that after the close, once advancing issues and new highs have printed. The options market is already quoting a related question, because index options and single-stock options together imply how much the constituents are expected to move, and how much they are expected to move together, over the next month. That is not the same as knowing what realised breadth will do next week. It is a reading of the surface that is being priced now.
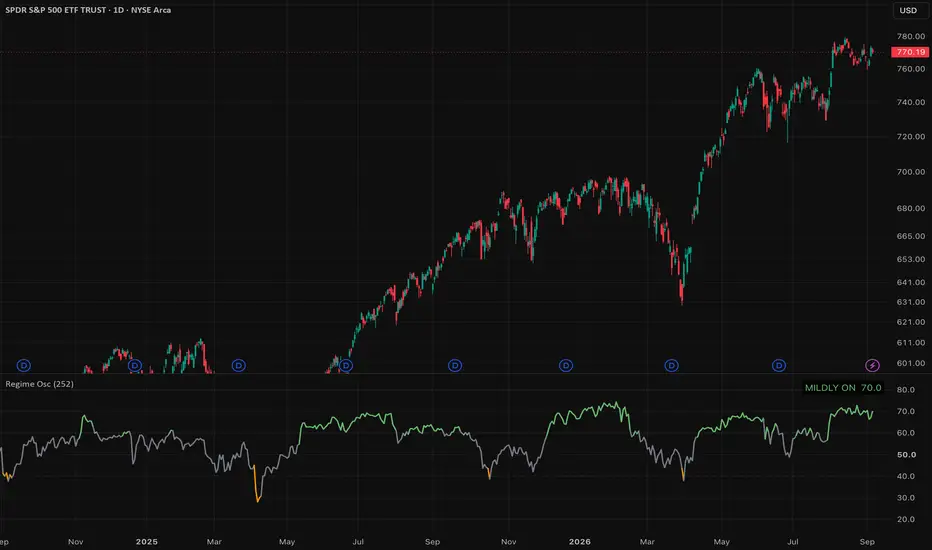
Implied Market Structure is that reading, turned into a pane. It does not look at the price of the chart you dropped it on. It reads three Cboe indices that already live on TradingView (DSPX, COR3M, VIXEQ) and maps them into an options-derived forward-looking market structure: what kind of tape the listed surface is paying for. Direction still comes from your own setup. This script answers how that setup should be expressed, whether as an index overlay, a single-stock book, a hedge, or a smaller size. Open a daily SPX, ES or SPY chart, add the script, and read the dashboard before you argue with the line.
What you are looking at, from the pane outward. The thick line is the IMS score on a 0 to 10 scale, a one-dimensional summary of two ranks: high DSPX percentile plus low COR3M percentile. Near 10 the surface is paying for stock-level divergence. Near 0 it is paying for a herd. The line is green at or above 7.5, red at or below 2.5, and blue in between. Those two horizontal marks are not regime thresholds. They are score tails. The faint grey line at 5 is the midpoint of the summary, nothing more. The thinner, smoother line is a 21-day EMA of the same score, updated on daily changes. If it has fallen by at least 0.20 over five days the dashboard says FALLING; the opposite move is RISING; anything smaller is FLAT, so a one-tick wriggle does not rename the trend. The shaded band between 2.5 and 7.5 is only a mid-score fill. Optional grey bands around the line, off by default, are a 21-day standard deviation of the score, not a forecast interval. Two further optional lines, also off by default, plot the DSPX rank and the inverse COR3M rank on the same 0 to 10 scale when you want to see which factor is doing the work. Background colour, in the default Position mode, follows the two-dimensional regime rather than the score, so a mid-range line can still sit in a blue COMPRESSED patch. Dynamic mode instead tints the pane by the 0 to 10 reading. Off leaves the pane unshaded.
The same regime colours the candles, or the price line if you are not on candlesticks. Green is STOCK PICKING. Red is INDEX TAPE or BROAD STRESS, with tape drawn a little more faded than stress. Blue is COMPRESSED. MIXED is a weaker blue. That colour is a weather reminder. It is not a long or a short in ES or SPX.
The table at the top right is the actual reading, row by row. IMS score is the 0 to 10 summary, printed to two decimals, with confirmed D or live D on the right. Confirmed D, the default, uses the last completed daily Cboe print, so the last bar on a daily chart is yesterday’s structure and does not wander with the developing session. Live D uses the current daily close and can flip while cash is open. Regime is the two-dimensional class: INDEX TAPE, STOCK PICKING, BROAD STRESS, COMPRESSED or MIXED. INDEX TAPE is high implied correlation and low expected dispersion, the index treated as one factor, which is when ES and SPY trades and index puts are the more natural tools and single-stock selection is swimming against a herd. STOCK PICKING is the opposite corner, high dispersion and low correlation, which is Cboe’s stated use of DSPX as a read on the opportunity set for names (Cboe, n.d.a), not a long signal in the index. BROAD STRESS is both high, movement with togetherness, when reducing size and using index hedges tends to hurt less than hunting for the one name that will decouple. COMPRESSED is both low, quiet on both axes. MIXED means at least one series is still in the middle, so you leave IMS in the background. Why restates the corner in words, DSPX HIGH, MID or LOW and COR3M the same, which is the reason the regime is what it is. A score of 5.4 with both factors LOW is still COMPRESSED. The line looks mid because low dispersion and low correlation pull the summary in opposite directions. That is why the table exists.
DSPX shows the raw Cboe dispersion level, then the trailing percentile in parentheses, then HIGH, MID or LOW. Green on that row is high dispersion. Red is low dispersion, the herd side of that axis, even when the regime as a whole is the quieter blue of COMPRESSED. COR3M shows the raw implied-correlation level the same way. Green there is low correlation, the picking side. Red is high correlation, the tape side. The percentiles in those rows are rounded to whole numbers. The score above them uses the unrounded ranks, so 25p and 18p can sit next to 5.4 without a contradiction. Vol overlay is VIXEQ’s percentile, labelled ELEVATED at or above 70, SUBDUED at or below 40, otherwise NORMAL, with the word overlay on the row so it is not mistaken for a third term in the score. VIXEQ does not enter the 0 to 10 line and does not move the regime. You can hold STOCK PICKING and still see constituent implied volatility elevated. The first fact is structure. The second is the vol climate around it. Trend is the EMA slope already described. Status is ACTIVE once DSPX and COR3M both have a rank, and WARMING UP until the lookback fills. If a feed is late the score stays blank rather than collapsing toward zero.
The grid under those rows is the same two-dimensional plane drawn as a table. Rows are DSPX, high at the top, low at the bottom. Columns are COR3M, low on the left, high on the right. PICK is high dispersion with low correlation. STRESS is both high. COMP is both low. TAPE is low dispersion with high correlation. MIXED sits in the centre, and the dotted cells are the mixed edges where only one factor has left the middle. The highlighted cell is the current corner. The footer under the grid says score = summary and matrix = 2D grid, which is the whole design in six words: the line compresses two ranks, the grid keeps them apart.
The small block at the bottom right of the pane is the watermark, the same facts for screenshots: ticker and timeframe, the score, the regime with the Why line, and confirmed daily or live daily. Colour across every theme keeps the same jobs. Green is high dispersion, low correlation, stock picking, subdued VIXEQ. Red is high correlation, index tape, broad stress, elevated VIXEQ. Blue, the primary colour of the theme, is compressed or mid. The eight themes only change the paint, not the meaning.
Cboe built DSPX to measure expected 30-day dispersion in the S&P 500 from index options and from selected single-stock options (Cboe Global Markets and S&P Dow Jones Indices, 2023; Cboe, n.d.a). COR3M is the ATM constant-maturity estimate of average correlation among the top 50 names (Cboe, n.d.b). VIXEQ is the cap-weighted 30-day implied volatility of that same basket, published as a DSPX component and scheduled for live calculation in November 2024 (Cboe Global Markets and S&P Dow Jones Indices, 2024). IMS does not rebuild those formulas. It ranks the published daily closes over a trailing window of daily prints, default 252 sessions, inside the daily request, so the lookback remains 252 daily observations on an hourly chart as well as on a daily chart. The ranks are smoothed with a short daily EMA. High and low for the corners enter at the 60th and 40th percentiles and, with hysteresis on, leave only after 55 and 45, which stops a one-percentile wobble from renaming the tape. Daily is the timeframe this was written for. Trend and bands follow daily changes on the host chart, so they are exact on a daily pane and only as fine as the host timeframe on a weekly one.
Alerts fire on a confirmed bar for the step from one regime into another, including MIXED -> STOCK PICKING, for leaving a corner, for the score crossing 7.5 or 2.5, for a turn in the daily EMA slope, and for VIXEQ first reaching the elevated overlay band. Wire them to a notification, not to an order. The script will not tell you whether SPX is going up, and it does not claim to forecast next week’s realised breadth. It tells you, each morning, whether the listed options surface is treating the next month as a crowd or as 500 separate stories.
DSPX has been live since 27 September 2023. VIXEQ’s live window is shorter, so its percentile can stay blank until the lookback fills. The ranks are relative to that window, not to a decade of history. No return forecast is claimed, and Cboe, S&P DJI and VIX remain trademarks of their owners.
References
Cboe (n.d.a) Cboe S&P 500 Dispersion Index. Available at: www.cboe.com
Cboe (n.d.b) Implied Correlation. Available at: www.cboe.com
Cboe Global Markets and S&P Dow Jones Indices (2023) S&P Dow Jones Indices and Cboe Global Markets to Launch the Cboe S&P 500 Dispersion Index. Available at: www.prnewswire.com
Cboe Global Markets and S&P Dow Jones Indices (2024) Cboe Global Markets and S&P Dow Jones Indices Plan to Launch New Cboe S&P 500 Constituent Volatility Index (VIXEQ). Available at: www.prnewswire.com
指標

Oleg AlgoWelcome to Oleg Algo, a heavy-duty, multi-layered statistical mean-reversion and trend-following strategy designed for traders who like to scale into volatility like a crazy. This script allows you to harvest profits from market extremes using dynamic gap thresholds, aggressive scale-in martingale sizing, and built-in risk boundaries.
Key Features
Dual Strategy Modes: Switch effortlessly between Reversal Mode (catching extreme overextended moves by fading the gap) and Trending Mode (riding the momentum wave).
Flexible Band Calculations: Measure market boundaries using either ATR (Average True Range) for pure volatility-based distance or Bollinger Bands (Standard Deviations) for statistical dispersion.
Scale-In Martingale System: Automatically scale into positions as the market moves against you. Choose between an exponential Multiplier or a linear Quantity Step to average down like a true strategist.
Win/Loss Outcome Sizing: Optionally adjust your base position size up or down following a win or loss to dynamically manage your exposure streak.
Time Windows: Built-in EST market-session filters that strictly lock your trading window and automatically flatten all open positions before the closing bell rings.
Max Dollar Loss Circuit Breaker: An absolute safety switch that liquidates everything if unrealized open drawdowns cross your predefined dollar risk threshold.
Input Guide
Strategy Execution Mode: Choose whether we hunt the reversal when price crashes hard away from the line, or follow the big bear/bull wave.
Trade Direction: What kind of hunt we do—go both ways like a smart trader, or stick strictly to long-only or short-only.
Moving Average Type & Length: Pick your line flavor (SMA, EMA, HMA).
Band Calculation & Initial Gap: Define how far price must run away from the baseline before enter trade.
Scale-In Step & Martingale Settings: Control how deep price must drop before adding more size, and how aggressively each stacked layer grows.
Take Profit & Stop Loss Multipliers: Set your distance for collecting big feasts when the average entry price bounces back, alongside the emergency parachute stop loss.
Prop Mode & Start/End Times: Lock your trading strictly inside capitalist working hours so you never violate risk rules or hold overnight risk. 策略

ATK/DEF Temporal Dual-Axis Market Engine# ATK / DEF — Temporal Dual-Axis Market Engine
ATK / DEF — Temporal Dual-Axis Market Engine is a multi-layer market analysis framework that dynamically combines multiple timeframes with three major market sessions: Asia, Europe, and America.
The framework processes higher, middle, and lower timeframe data together with session-based calculations to organize market conditions across different temporal layers.
## Core Framework
* HTF / MTF / LTF multi-timeframe structure
* Monthly / Weekly / Daily / 4-Hour / 1-Hour data
* Asia / Europe / America session framework
* Dynamic session-based calculations
* Price-layer classification
* Liquidity and volume-based conditions
* Direction and momentum states
* Drive and breakout conditions
* Market structure and swing levels
* Fibonacci-based retracement levels
* POC reference and price deviation
* Support / resistance reference levels
* Multi-layer analytical dashboards
## Temporal Analysis
The engine combines timeframe structure and session structure into a unified analytical view.
Each layer provides calculated information related to:
Price Position · Liquidity · Direction · Momentum · Drive · Breakout · Structure · Retracement · POC · Deviation
The dashboard organizes these calculated conditions so different timeframe and session states can be observed together.
## POC & Deviation
The framework includes a calculated POC reference based on the selected price rang, together with price deviation from the POC.
These values provide additional reference points for observing price concentration and distance within the calculated range.
## Market Structure
Swing High / Low calculations provide dynamic structural reference levels, including calculated support and resistance areas.
The framework also incorporates Fibonacci-based retracement classification to describe the current position within the calculated price range.
## Analytical Framework
ATK / DEF is designed as an observation and analysis framework rather than a system.
The displayed values are calculated from market data, timeframe conditions, session ranges, volume relationships, price movement, swing structure, retracement levels, POC, and deviation.
The dashboard is intended to provide customizable analytical references across different market layers. Interpretation remains dependent on the use own market analysis and decision-making process.
This indicator does nt provide , recommendations, or rik raos.
Market observation and analysis only.
指標

KIRON Universal Pattern Engine KIRON Universal Pattern Engine
The KIRON Universal Pattern Engine is a multi-pattern technical-analysis indicator designed to identify developing and completed chart formations, draw their full structure directly on the chart, and construct an objective trade plan for the strongest eligible setup.
The indicator is designed for use across liquid markets—including forex, gold, indices, commodities, equities and cryptocurrencies—and can be applied to different chart timeframes. Volatility-sensitive calculations are normalised using Average True Range (ATR), allowing the detection thresholds and trade levels to adapt to the instrument being analysed.
PATTERNS DETECTED
The engine searches for:
• Double Bottom
• Double Top
• Triple Bottom
• Triple Top
• Head and Shoulders
• Inverse Head and Shoulders
• Rectangle
• Ascending Triangle
• Descending Triangle
• Symmetrical Triangle
• Bull Flag
• Bear Flag
• Bull Pennant
• Bear Pennant
• Rising Wedge
• Falling Wedge
• Cup and Handle
FULL PATTERN VISUALISATION
Each formation is drawn using its actual structural points rather than represented by a generic box.
Depending on the formation, the indicator can display:
• Pattern highs and lows
• Peaks, troughs and shoulders
• Head and shoulder points
• Necklines
• Support and resistance boundaries
• Upper and lower trendlines
• Flagpoles and consolidation channels
• Pennant and triangle boundaries
• Wedge convergence
• Pattern apex
• Cup and handle geometry
• Breakout or invalidation information
Bullish structures use bullish colours, while bearish structures use bearish colours. Neutral structural levels—such as necklines and horizontal boundaries—are displayed separately for clarity.
DEVELOPING PATTERNS
The indicator is designed to identify formations while they are developing, rather than waiting until the entire subsequent price move has already occurred.
A developing formation can change as new confirmed swing points become available. Once its structural pivots have been confirmed, those historical pivot points are not moved retrospectively.
This distinction is important:
• Confirmed pivot points do not repaint.
• An unfinished formation may evolve, be replaced or become invalid as new price information arrives.
• A breakout is not guaranteed simply because a developing structure has been identified.
CANDIDATE SELECTION
Several formations may be detected within the same market structure. The engine therefore evaluates each eligible candidate using:
• Structural validity
• Pattern quality
• Direction
• Pattern priority
• Formation age
• Volatility-adjusted tolerances
• Availability of the required confirmed pivot sequence
Where several patterns compete for the same area of price action, the engine ranks them and selects the strongest current candidate for the trade plan.
The number of visible historical patterns is limited to prevent excessive chart clutter.
PATTERN QUALITY
Every valid formation receives a quality measurement based on how closely its confirmed swing structure matches the expected geometry of that pattern.
A higher score represents a closer geometric match. It does not represent a guaranteed probability of success.
The minimum quality setting can be increased to produce fewer but more selective formations, or reduced to allow more developing candidates to appear.
ENTRY, STOP LOSS AND PROFIT TARGETS
The strongest eligible directional pattern receives a complete volatility-adjusted trade plan.
The plan includes:
• Entry
• Stop Loss
• Take Profit 1
• Take Profit 2
• Take Profit 3
• Initial price risk
• Direction of the setup
The entry is calculated from the relevant breakout boundary with an optional ATR-based entry buffer.
The stop loss is placed beyond the pattern’s structural failure point, with an additional ATR-based protective buffer.
Profit targets are calculated as configurable multiples of the initial risk:
• TP1 = Entry plus or minus the selected first risk multiple
• TP2 = Entry plus or minus the selected second risk multiple
• TP3 = Entry plus or minus the selected third risk multiple
For bullish setups, targets are projected above the entry. For bearish setups, targets are projected below the entry.
Trade levels are only produced when the engine can construct a logically valid directional plan with positive risk.
DASHBOARD
The dashboard provides a concise summary of the strongest current setup, including:
• Current verdict
• Selected pattern
• Bullish, bearish or unresolved direction
• Pattern quality
• Number of live candidates
• Entry price
• Stop-loss price
• TP1
• TP2
• TP3
• Initial risk
• Number of stored patterns
If no eligible formation is available, the dashboard reports that there is no valid setup rather than manufacturing trade levels.
MAIN SETTINGS
Confirmed Pivot Length
Controls how many bars are required on each side of a swing before that pivot is confirmed. A smaller value increases sensitivity, while a larger value identifies broader market structures.
ATR Length
Controls the volatility measurement used by the pattern tolerances, entry buffer and stop-loss calculation.
Level Tolerance
Determines how closely two or more swing prices must align to be treated as equivalent support, resistance, tops or bottoms.
Minimum Pattern Height
Prevents extremely small price fluctuations from being classified as meaningful formations.
Minimum Pattern Quality
Controls the minimum structural quality required before a candidate is accepted.
Maximum Pattern Age
Determines how long a detected formation remains eligible for current analysis.
Maximum Visible Patterns
Limits the number of formations displayed simultaneously to preserve chart readability.
Entry Buffer
Adds volatility-adjusted confirmation beyond the breakout boundary.
Stop Buffer
Adds volatility-adjusted protection beyond the structural invalidation point.
Target Risk Multiples
Controls the risk-to-reward calculations used for TP1, TP2 and TP3.
SUGGESTED WORKFLOW
1. Begin with a higher timeframe to establish the broader market structure and directional context.
2. Use the indicator to identify a developing or completed formation.
3. Examine the full visual geometry rather than relying only on the pattern name.
4. Review the quality score and direction shown on the dashboard.
5. Wait for appropriate breakout confirmation where required.
6. Confirm that the proposed entry, stop and targets are suitable for current liquidity, spread and market conditions.
7. Avoid entering immediately before major economic announcements or during abnormal volatility.
8. Apply independent position sizing and account-level risk management.
IMPORTANT LIMITATIONS
Chart-pattern recognition is inherently interpretative. Two traders may identify different formations within the same price structure.
Confirmed pivots require future bars before they become established. This introduces confirmation delay but prevents historical swing points from being treated as confirmed prematurely.
A detected pattern can fail, remain range-bound or break in the opposite direction. Pattern quality measures geometric conformity—not future performance or certainty.
ATR-based calculations adapt to volatility but cannot account for every market condition, including gaps, slippage, illiquidity, news shocks or sudden spread expansion.
The indicator should be used as a structured decision-support tool and not as a standalone instruction to enter a trade.
RISK DISCLAIMER
This indicator is provided for educational and analytical purposes only. It does not constitute financial or investment advice.
Trading leveraged products, forex, commodities, indices and cryptocurrencies involves substantial risk. Historical formations and projected targets do not guarantee future results. Users remain responsible for independently evaluating every setup, selecting appropriate position size and managing their own risk.
指標

Signal Follow-Through Ledger [MQLSoftware]OVERVIEW
Signal Follow-Through Ledger measures what price actually did after a signal you already have. You point it at any numeric plot on your chart — a built-in price source, your own indicator, or a third-party one — tell it what counts as an event on that series, and it keeps an audit trail of how each event turned out. It owns no signal of its own and creates no entries, stops, targets or position sizing. It answers one question about a signal you already use: when this fired before on this chart, what usually happened next?
CONCEPTS
Each event opens a sample. The reference price is the close of the confirmed signal bar, and the favourable and adverse distances come from an ATR snapshot taken on that same bar and then frozen for the life of that sample. Rescaling old samples by today's volatility is the usual way this measurement goes wrong, so each sample is judged by the volatility that existed when it was taken.
Evaluation starts on the bar after the signal and runs for a configurable horizon, twenty bars by default. The signal bar's own high and low were printed partly before its close, so testing them would read its past as the signal's future.
When one later bar contains both thresholds, OHLC data cannot say which came first. That sample is recorded as ambiguous and kept out of the headline rate rather than guessed either way, which is the largest single source of overstated numbers here. A sample that reaches neither threshold inside the horizon is a real answer and stays in the denominator.
MFE and MAE keep accumulating for the whole horizon even after a sample resolves; stopping them at resolution would floor MFE at your own favourable multiple and describe your setting rather than the market.
FEATURES
Seven event types: cross up or down through a level, cross up or down through a reference (a moving average of the source, or a second plot), a new N-bar high or low, and a first non-blank value for sources that are blank except when they signal. Direction follows the event or can be forced. The panel reports the share of samples that reached the favourable target before the adverse one, the sample size, the favourable / adverse / neither split, median MFE and MAE in ATR, median bars to the peak, and the ambiguous, still-open and declined counts. Signal markers, outcome markers and the measurement corridor are drawn on the chart. Two confirmed-bar alerts: a sample recorded, and a sample resolved.
HOW TO USE
Open Settings and set Signal source to the plot you want audited; the dropdown lists the indicators already on your chart. Choose the event, and for level modes type the level in the units of that source — 30 or 70 for RSI, 0 for a zero-centred oscillator. Out of the box it audits price crossing above its own fifty-bar average, so it produces numbers before you configure anything.
Read the headline with the sample size beside it, never alone. Rates stay behind a minimum-sample gate and read "collecting" until enough samples complete. One sample runs at a time by default, so events arriving inside an open horizon are declined and counted separately: that declined figure tells you the signal fires more often than the ledger samples it.
Everything in the ledger is written on confirmed bars and is never revised. The single live figure is the raw source readout in the panel footer, so you can confirm the source is wired up.
CONCLUSION
This is a measurement tool, not a strategy tester. It models no fills, spread, commission, slippage, position sizing or intrabar sequencing, so nothing here is a profitability result. The figures describe what this chart's loaded bars did after these events, on this symbol, timeframe and source, shown with the sample size that produced them. And it cannot make a repainting source stable: if the indicator you point it at rewrites its own history, the events change and this audit changes with them. 指標

Cross-Asset Regime OscillatorA daily 0–100 gauge of US market risk appetite, built from five cross-asset
signals rather than price alone. It answers one question: is the broader
tape leaning risk-on or risk-off right now?
METHOD
Each signal is z-scored against its own trailing distribution on daily bars
("Lookback (bars)" input, default 252 ≈ one trading year, range 60–1000),
clamped to ±3 so no single blown-out signal dominates, averaged with equal
weight, then mapped linearly onto 0–100. The lookback always counts daily
bars, whatever the chart timeframe.
SIGNALS (all free-tier data, no premium feeds)
1. Credit — HYG/IEF: high yield vs. Treasuries. Higher = risk-on.
2. Equity volatility — VIX, inverted. Lower vol = risk-on.
3. Cyclical vs. defensive — XLI/XLU: industrials vs. utilities. Higher = risk-on.
4. Yield curve — US10Y minus US03MY (10-year minus 3-month). Steeper = risk-on.
5. US dollar — DXY, inverted. Weaker dollar = risk-on.
READING IT
0–20 RISK-OFF · 20–40 MILDLY OFF · 40–60 NEUTRAL · 60–80 MILDLY ON · 80–100 RISK-ON
The line is colored by band, with dotted guides at 20/40/60/80, and the
corner readout shows the current band and score. Enable "Show signal
breakdown" to see each signal's clamped z-score and the composite in the
corner table — useful for seeing WHICH channel is driving a move (e.g. credit
still positive while vol and cyclicals roll over). "Color chart bars by
regime" paints the price bars with the band color.
MISSING DATA
A signal that has not loaded, has fewer daily bars than the lookback, or is
flat over the lookback is skipped, and the composite averages the rest. The
readout warns when fewer than 3 of the 5 signals have data.
NON-REPAINTING
Every value is the clamped z-score of the last CONFIRMED daily bar, computed
inside the daily security context. The one-bar offset makes the request
confirmed-only, so the forming daily bar never leaks in and values never
change on refresh. Each day's value is aligned to the start of the daily
period, so the reading is identical on every supported chart timeframe.
During a live session the reading reflects the prior session's close.
SUPPORTED TIMEFRAMES
Daily and intraday charts. On any chart timeframe above daily (weekly,
monthly, multi-day) the script stops with a runtime error by design:
"Cross-Asset Regime Oscillator is a daily indicator. Use a 1D or lower
chart timeframe." It is a daily oscillator, and above-daily requests cannot
be pinned reliably to the same confirmed session.
LIMITATIONS
This is a deliberately simple, transparent construction: equal weights, one
lookback, five signals. It describes current conditions; it does not
forecast. Short lookbacks react fast and can whipsaw. Not investment advice. 指標

指標

Liquidation Map Liquidation Map Pro: Adaptive Neon Edition** estimates where leveraged longs/shorts are likely to get liquidated, then draws those zones as neon lines on the chart. Line intensity follows Open Interest from Binance, Bybit, and OKX (falls back to a volume proxy if OI is missing)
What it is
An overlay that maps estimated liquidation clusters around recent swing highs and lows. It is a **heatmap of likely stop/liquidation zones**, not a buy/sell signal.
How it works
1. Finds pivot highs and lows (sensitivity is adjustable).
2. Places **100x** levels ~1% beyond the pivot (neon red) and **50x** levels ~2% beyond (neon cyan).
3. Only draws when Open Interest change ranks as “large player” activity. OI is averaged across Binance / Bybit / OKX; if those feeds are unavailable, it uses `(high − low) × volume` as a proxy.
4. Lines stay active until price **sweeps** them (high/low crosses the line). Older lines are dropped after ~480 so the chart stays clean.
How to read it
- **Red (100x)** — tighter, more aggressive liquidation.
- **Cyan (50x)** — wider, slightly less leveraged.
- **Brighter / denser lines** — stronger OI spike (bigger flow).
- A sweep of a cluster often means that pocket of leverage has been flushed.
Settings
Lookback, MA length, pivot sensitivity, large-player threshold, colors, line width, and opacity. Exchange OI tickers are hardcoded and not shown in the UI.
這是什麼
疊加在 K 線上的「清算地圖」:在近期波段高點/低點附近,估算槓桿多空可能被強平的價位。這是**可能的停損/清算熱區視覺化**,不是買賣訊號。
怎麼算
1. 找出樞軸高點、低點(靈敏度可調)。
2. 在樞軸外約 **1%** 畫 **100x** 清算線(霓虹紅),約 **2%** 畫 **50x**(霓虹青)。
3. 只有當未平倉量(OI)變動被判定為「大戶級」時才畫線。OI 會綜合 Binance、Bybit、OKX;抓不到就改用 `(最高−最低) × 成交量` 當代理。
4. 價格**掃過**該線(高低價穿越)後,該線失效。圖上最多約 480 條,舊線會自動刪除。
**怎麼看**
- **紅線(100x)**:距離更近、槓桿更高,較容易被掃。
- **青線(50x)**:距離稍遠、槓桿較低。
- **越亮、越密**:OI 衝得越猛,資金越集中。
- 某一帶被掃掉,通常代表那一層槓桿已被清算。
可調參數
回看根數、均線長度、樞軸靈敏度、大戶門檻、顏色、線寬、透明度。三所 OI 代碼寫死在腳本裡,介面上不顯示。
一句話
EN: See where leveraged positions may get flushed — neon lines, OI-weighted, until price takes them out.
中:用霓虹線標出槓桿可能被掃的價位;強度跟 OI 走,被掃過就熄燈。 指標

CTZ Bitcoin Cycle Master
**CTZ Cycle Trader + Confluence**
Three independent forecasting methods on one chart, gated so a signal only counts when they agree. Cyclical timing, statistical swing projection, and momentum triggering work together to show where price is likely to turn, when, and whether to act.
**① The Cycle Framework**
A four-tier cycle model — Daily (DCL), Weekly (WCL), Yearly (YCL) and 4-Year (4YCL) cycle lows — each with confirmation logic, running counts, and forward-projected timing windows. Asset presets auto-tune the cycle lengths to the instrument you load (Bitcoin, metals, indices, forex, energy). A live dashboard tracks days since each low, which windows are open, and the projected dates for the next turns.
**② Dual Swing Prediction Zones**
Drawing on the full history of the instrument's price swings, the tool projects **two forward target zones at once** — a green LOW-target box below price and a red HIGH-target box above it. Each is built from the statistical spread of past swings in that direction: how far they typically ran, and how long they lasted. Rather than guessing a single direction, it brackets the expected reversal range on both sides, so you can see where the next swing low and swing high are statistically due before price arrives. Green and red shading also colours every completed swing across history, making the market's rhythm visible at a glance.
**③ The Tidewave Trigger**
A WaveTrend + RSI momentum engine fires bull and bear reversal arrows, auto-adjusting from scalping frames to the macro. These are the entries — the moment the turn actually begins.
**The confluence**
The layers gate each other. A bull arrow carries full weight only inside the green low zone and near a projected cycle low; a bear arrow only in the red high zone near a cycle high. The cycle says a turn is *due*, the zone says *where and by how much*, momentum says *it's happening now*. A dedicated confluence alert fires only when all three agree.
**⚓ The 4-Year Anchor — and keeping it current**
Bitcoin's cycles nest inside the 4-year rhythm — every daily, weekly, and yearly low sits within the larger cycle that begins at each bear-market bottom. This tool lets you anchor the entire cycle clock to that bottom with a single date.
By default the anchor is set to **21 Nov 2022**, Bitcoin's last bear-market low. Every cycle phase and projection counts forward from there, so the timing is measured from a structurally meaningful origin rather than a mid-cycle pivot.
**Updating it:** each cycle bottom is a moving reference. When the next 4-year low forms and confirms, open the indicator settings, find the **4YCL Master Anchor** group, and change the **4YCL Anchor Date** to the new bottom (for the current cycle, that will be the 2026 low once it's in). The whole cycle clock re-bases from the new date instantly — no code editing required. Set it to the exact bottom candle, since the anchor is load-bearing: a few days off shifts every downstream projection by those days. Because you update it only after the low has confirmed, you'll always know the precise date. You can also toggle the anchor off to fall back to auto-detected pivots.
**Built to be read at a glance**
The dashboard consolidates cycle counts, open windows, due-dates, prediction-zone status, and anchor position into one panel. State labels, arcs, and extras stay off by default for a clean chart, and every layer has its own toggle — run pure cycles, pure signals, or the full confluence view.
*The cycle tells you when. The zones tell you where. Momentum tells you it's happening. Together they tell you whether to act.*
*For educational purposes. Not financial advice — always confirm with your own analysis and test on your own instruments and timeframes before trading live.*
指標

CHoCH Fib Setup [Almaghamsi]CHoCH Fib Setup is an educational overlay indicator that combines Change of Character (CHoCH) detection with Fibonacci retracement and extension levels.
The script is designed to help traders study one structured workflow on a single chart:
Identify a CHoCH on the current timeframe.
Draw Fibonacci levels on the impulse that produced that CHoCH.
Highlight a 0.5-0.618 pullback zone as a study area for potential entries.
Project extension targets at 1.272, 1.414, 2, 1.618 and 2.618.
Optionally filter setups with a higher-timeframe structure bias.
This is not a buy/sell signal service and it does not place trades. It is a visual study tool.
What the script does
The script uses pivot highs and lows to track the latest swing points. A bullish CHoCH is marked when price breaks above the last relevant swing high after a non-bullish bias. A bearish CHoCH is marked when price breaks below the last relevant swing low after a non-bearish bias. Users can require a close beyond the level or allow a wick break.
After a valid CHoCH, the script anchors a Fibonacci range to that impulse:
Retracement levels: 0, 0.236, 0.382, 0.5, 0.618, 0.786, 1.0
Entry study zone: 0.5 to 0.618
Stop-loss line at the opposite extreme of the impulse
Extension targets: 1.272, 1.414, 1.618 ,2 and 2.618
Each level is printed with its ratio and the actual price.
An optional higher-timeframe module reads the same structure logic on a user-selected timeframe. When enabled, long Fibonacci setups are drawn only if HTF bias is bullish, and short setups only if HTF bias is bearish. Counter-trend CHoCH events can still appear as faded labels ending with "x".
The settings panel is bilingual (English / Arabic), with English first. On-chart labels default to English and can be switched to Arabic.
Why this combination exists
CHoCH, Fibonacci retracements, Fibonacci extensions, and multi-timeframe bias are established public concepts. This script does not invent those concepts. Its purpose is to keep them in one readable workflow so the user does not have to draw the Fib range manually after every CHoCH.
The script is original as a packaged study layout: aligned CHoCH-to-Fib mapping, optional HTF gating, price labels on targets, and a bilingual interface. It does not claim to reverse-engineer any closed-source vendor tool.
How to use
Add the indicator to a standard candlestick chart.
Choose a working timeframe. Example: 15 minutes for entries.
Enable the HTF filter if desired and set a larger interval. Example: 60 on a 15-minute chart.
Wait for a CHoCH in the direction of the HTF bias.
Use the 0.5-0.618 box only as a pullback study zone, not as an automatic order.
Treat the red line as a structural invalidation reference, not a broker order.
Treat 1.272 / 1.414 / 1.618 /2 /2.618 as measured extension references only.
Confirm context with your own analysis and risk limits.
Limitations
Pivot length changes the CHoCH results. This is a simplified swing-break model and not a full Smart Money Concepts suite. It does not plot order blocks, FVGs, or liquidity pools. HTF bias can change until the higher-timeframe bar closes. The script keeps the latest aligned Fibonacci setup, not unlimited history. Pivot confirmation needs right-side bars, which is normal for pivot logic. There is no win rate because this is an indicator, not a strategy().
Disclaimer
This script is provided for education and chart study only. It is not investment advice, financial advice, trading advice, or a recommendation to buy or sell any instrument. Markets involve a high risk of loss. Past behavior around CHoCH or Fibonacci levels does not predict future results. Users are responsible for their own decisions, position sizing, and local regulations.
Open-source note
This publication is open-source so users can inspect the logic. If you reuse parts of the code in a public script, credit this publication and add a meaningful improvement before publishing.
مؤشر CHoCH Fib Setup أداة تعليمية على الشارت تجمع بين اكتشاف تغيير صفة الحركة (CHoCH) ومستويات فيبوناتشي للتصحيح والامتداد.
الهدف هو دراسة مسار واحد على نفس الشارت:
تحديد CHoCH على الفريم الحالي.
رسم فيبوناتشي على موجة الاندفاع التي صنعته.
تظليل منطقة 0.5 إلى 0.618 كمنطقة دراسة للدخول المحتمل.
إسقاط أهداف 1.272 و 1.414 و 1.618 و 2 و2.618.
إمكانية فلترة السيتب باتجاه الفريم الأعلى.
هذه ليست خدمة توصيات ولا تفتح صفقات تلقائيًا. هي أداة بصرية للدراسة.
ماذا يفعل المؤشر
يستخدم قممًا وقيعانًا محورية لتتبع آخر نقاط التأرجح. يُعلَّم CHoCH الصاعد عند كسر آخر قمة محورية بعد انحياز غير صاعد، والهابط عند كسر آخر قاع محوري بعد انحياز غير هابط. يمكن اشتراط الإغلاق أو السماح بكسر الظل.
بعد CHoCH صالح يُثبَّت فيبوناتشي على الموجة، مع منطقة 0.5-0.618 وخط إبطال عند طرف الموجة وأهداف امتداد 1.272 و 1.414 و 1.618 و 2 و 2.618، وكل مستوى يظهر مع سعره.
فلتر الفريم الأعلى اختياري. عند تفعيله يُرسم سيتر الشراء فقط إذا كان الفريم الأعلى صاعدًا، وسيتر البيع فقط إذا كان هابطًا. أحداث CHoCH المخالفة يمكن أن تظهر باهتة وتنتهي بـ x.
لوحة الإعدادات ثنائية اللغة والإنجليزية أولًا. نصوص الشارت افتراضيًا بالإنجليزية ويمكن تحويلها للعربية.
لماذا هذا التجميع
المفاهيم عامة ومعروفة. المؤشر لا يدّعي اختراعها. الغرض جمعها في مسار واحد حتى لا يُرسم الفيبو يدويًا بعد كل CHoCH. الأصالة في التغليف: ربط CHoCH بالفيبو، فلتر الفريم الأعلى، السعر على الأهداف، وواجهة ثنائية اللغة.
طريقة الاستخدام
أضف المؤشر على شارت شموع قياسي، اختر فريم العمل، فعّل الفلتر إن أردت، وانتظر CHoCH مع اتجاه الفريم الأعلى. صندوق 0.5-0.618 منطقة دراسة فقط، والخط الأحمر مرجع إبطال، والأهداف مراجع قياس. أكّد دائمًا بتحليلك وحدود المخاطرة.
القيود
النتيجة تتغير مع طول المحور. النموذج مبسّط ولا يرسم كتل أوامر ولا فجوات قيمة عادلة. انحياز الفريم الأعلى قد يتغير قبل إغلاق شمعة ذلك الفريم. لا توجد نسبة نجاح لأن هذا مؤشر وليس استراتيجية.
إخلاء المسؤولية
هذا المؤشر للتعليم ودراسة الشارت فقط، وليس استشارة استثمارية ولا توصية بشراء أو بيع أي أداة. التداول ينطوي على مخاطر خسارة مرتفعة، والسلوك السابق لا يتنبأ بالنتائج المستقبلية. المستخدم مسؤول عن قراراته وحجم المخاطرة والأنظمة المحلية.
ملاحظة المصدر المفتوح
نُشر السكربت مفتوح المصدر لمراجعة المنطق. إذا أعدت استخدام أجزاء منه في منشور عام، اذكر هذا المنشور وأضف تحسينًا حقيقيًا قبل النشر. 指標

Equalhigh Fair Value & UpsideEqualhigh — Fair Value & Upside | SBC v1.1
Equalhigh Fair Value & Upside is a fundamentals-based valuation indicator for stocks. It combines financial data available through TradingView with user-defined valuation assumptions to display fair value, a margin-of-safety buy zone, and an optional future price target.
The FCF component explicitly deducts stock-based compensation (SBC).
This is a valuation tool. It does not predict market turning points or calculate the probability of a price increase.
WHAT THE INDICATOR DISPLAYS
• Orange — Base-case fair value.
• Green — Buy-zone threshold after applying your margin of safety.
• Blue dashed line — Optional nominal target at your selected horizon.
Labels display price levels and potential upside or downside. The dashboard shows the underlying financial inputs, valuation multiples, calculation status, and projected annualized price return.
The green level marks the maximum price within the model’s buy zone. It is not an automatic entry signal.
VALUATION MODELS
Choose between three methods:
• EPS: diluted earnings per share × target P/E.
• FCF after SBC: FCF after deducting SBC, divided by diluted shares, multiplied by the target FCF multiple.
• Hybrid: a weighted combination of both methods.
In Hybrid mode, an EPS weight of 50% gives equal weight to the two components. A weight of 100% uses only EPS; 0% uses only FCF.
Core calculations:
FCF after SBC = FCF before SBC − SBC
FCF after SBC per share = FCF after SBC ÷ diluted shares
Hybrid fair value = EPS weight × EPS valuation + remaining weight × FCF valuation
Buy-zone threshold = fair value × (1 − margin of safety)
Upside/downside (%) = (fair value ÷ chart price − 1) × 100
A negative percentage means the chart price exceeds the model’s fair value.
QUICK START
1. Open the stock’s chart and add the indicator.
2. Select FY or TTM as the financial period.
3. Select the valuation model and, if applicable, the EPS weight.
4. Enter your target P/E and target FCF multiple.
5. Enter SBC for the same period as the FCF and confirm that the amount and period have been checked.
6. Review the retrieved financial data and apply manual overrides where necessary.
7. Optionally enable the projection and enter growth assumptions.
Target multiples default to zero. The relevant valuation component remains suspended until a positive multiple is entered.
DATA AND FINANCIAL PERIODS
The indicator requests diluted EPS, free cash flow, and diluted shares through TradingView’s financial data service. Availability depends on the stock and reporting frequency.
• FY: latest available fiscal-year data.
• TTM: trailing-twelve-month EPS and FCF data.
Selecting TTM does not automatically reconstruct missing financial data from individual reports. If a required field is unavailable, use a verified manual override.
Financial data updates independently of the chart timeframe. Switching from a daily to a weekly chart does not turn annual fundamentals into weekly fundamentals.
STOCK-BASED COMPENSATION
SBC must be entered manually in this version.
Enter the amount in millions of the chart currency. For example, 132 means 132 million.
Use the same reporting period for FCF and SBC. Do not combine annual FCF with six-month SBC.
The confirmation checkbox is required even when SBC is zero. Missing SBC is never silently treated as zero.
The FCF input should be before the SBC deduction applied by this script. Entering an already SBC-adjusted FCF and then entering SBC again would deduct the expense twice.
The EPS component uses the supplied diluted EPS without an additional SBC deduction.
SHARE DATA: FQ, FH AND FY
In TTM mode, select the share-data frequency:
• Auto: uses a positive FQ value first, otherwise FH, otherwise FY.
• FQ: quarterly share data.
• FH: semiannual share data.
• FY: annual share data.
Auto follows an availability order; it does not compare publication dates to identify the newest report.
In FY mode, automatic share retrieval uses FY data regardless of the TTM frequency setting.
The dashboard identifies the selected frequency. Combining TTM cash flows with a quarterly or semiannual average share count is an approximation.
A manual share-count override takes priority over automatic retrieval.
MANUAL OVERRIDES
You can replace:
• Diluted EPS — enter a per-share amount in the chart currency.
• FCF before SBC — enter a total amount in millions of the chart currency.
• Diluted shares — enter the number of shares in millions.
For example, 105.002977 represents 105,002,977 shares.
Record the source and period end in the source field. Manual values remain fixed until you change them and should be reviewed whenever you switch stocks.
Check whether your FCF source deducts lease repayments. The script does not automatically harmonize different FCF definitions.
FUTURE PROJECTION
Enable “Enable projection assumptions” to display the blue target.
Enter:
• Horizon in years.
• Annual diluted EPS growth.
• Annual FCF after SBC per share growth.
Each active valuation component grows at its own rate. Target multiples and Hybrid weights remain constant.
Projected component = current component × (1 + annual growth rate)^years
Annualized price return = × 100
Growth rates are entered as percentages: enter 8 for 8%.
FCF growth must already be expressed per share and after SBC. The script does not apply an additional dilution adjustment.
The blue line is a reference level for a future nominal target. It is not a forecast price path or a discounted present value.
Growth inputs are your assumptions. They are not automatically retrieved company guidance or analyst consensus.
WHY “SUSPENDED” MAY APPEAR
The dashboard explains what prevents calculation. Possible causes include:
• Missing or non-positive EPS.
• Missing FCF.
• Missing or non-positive share count.
• Unverified SBC.
• Non-positive FCF after SBC.
• An unconfigured target multiple.
Only components required by the selected model and weight must be valid. In Hybrid mode, the script does not silently redistribute weight when a required component is unavailable.
If shares are unavailable in Auto or FQ mode, try FH for a semiannual reporter, or enter a verified diluted share count manually.
DISPLAY SETTINGS
The dashboard can be positioned in any chart corner.
“Label offset (bars)” moves the labels horizontally relative to the latest bar. Labels are not pinned to the price axis.
Valuation lines begin at the latest bar and extend to the right. The indicator deliberately avoids applying today’s manual inputs retrospectively across the chart.
IMPORTANT LIMITATIONS
• Fair value depends on the selected multiples, weights, growth rates, and financial definitions.
• The indicator does not automatically normalize exceptional items or independently audit company filings.
• It does not separately add net cash or subtract net debt.
• The model may be unsuitable for banks, loss-making businesses, or companies requiring specialized valuation methods.
• Financial-data revisions and manual overrides make this version unsuitable as a historical point-in-time valuation backtest.
• Projected returns exclude dividends, fees, taxes, and currency changes.
• A stock can remain above or below modeled fair value for an extended period.
Use the indicator to make valuation assumptions visible and comparable. Combine its output with company research, financial-statement review, and your own risk-management process.
指標