Order Flow Footprint & DeltaOrder Flow Footprint & Delta
OVERVIEW
Order Flow Footprint & Delta is a candle + volume proxy scanner for the Order Flow playbook on TradingView.
It marks three educational setups — OF1 Continuation, OF2 Absorption reversal, and OF3 Break & retest — using structure bias, volume impulse, absorption proxies, and break/retest logic.
Important: TradingView does not provide true bid/ask footprint data for most symbols. This script uses candle and volume proxies. The on-chart dashboard shows Proxy = no footprint.
Built by the Xcelerate Trade team.
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
BEST USED WITH
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
Works much better together with:
→ “Fluid Liquidity Zones - CHoCH + Mitigation + HTF | Xcelerate Trade”
(or “Fluid Liquidity Zones - CHoCH | Xcelerate Trade”)
Use SUPPLY / DEMAND zones + CHoCH / market structure first, then OF labels as confirmation.
CONCEPT
Order flow tools help traders read aggression and reaction around levels. On TradingView, those ideas are approximated from open/high/low/close and volume.
Use this indicator as confirmation after higher-level context (supply/demand or liquidity zones + market structure), not as a standalone entry system.
GOLDEN RULE
Zone (SUPPLY/DEMAND) + structure first → then OF1/OF2/OF3 as confirmation — never the reverse.
Recommended timeframes: 15m–1h. Lower timeframes (1m/3m) are noisier and produce more false signals.
HOW THE SETUPS WORK
OF1 — CONTINUATION (cyan)
Idea: trend + stacked impulse + pullback + continuation.
Long OF1 when:
1) Bull bias (HH/HL structure + optional HTF up filter)
2) A bullish impulse / stacked strong bars existed
3) Price pulled back into the impulse zone
4) Confirmation (bullish bar / positive delta proxy)
Short OF1 is the mirror for bearish continuation.
OF2 — ABSORPTION REVERSAL (violet)
Idea: sweep of a level + absorption + reclaim.
Long OF2 when:
1) Sweep below a low / level (wick down)
2) Absorption (high volume, little progress)
3) Reclaim above the level with upside aggression
Short OF2 is the mirror after a sweep above a high.
OF3 — BREAK & RETEST (green long / red short)
Idea: volume break → retest → rejection.
Long OF3: break up → retest broken level as support → rejection up.
Short OF3: break down → retest as resistance → rejection down.
FEATURES
• Toggle OF1 / OF2 / OF3 independently
• Structure bias with optional HTF filter for OF1
• Volume / delta / imbalance / absorption proxies
• Optional break level lines
• Live dashboard (bias, delta proxy, stack status, setup wait/active)
• Alerts for each OF1/OF2/OF3 long and short condition
HOW TO USE (WITH FLUID LIQUIDITY ZONES)
1) Read bias / structure (HH HL / LH LL, CHoCH) for higher-level direction
2) Note where price is: DEMAND = long bias area, SUPPLY = short bias area
3) Then use OF labels:
• DEMAND + OF2 or green OF3 → long candidates
• SUPPLY + OF2 or red OF3 → short candidates
• OF1 only with the trend (not counter-trend in a range)
4) Dashboard “wait” means no signal on the current bar; older labels remain on history
SKIP / AVOID
• Bias = RANGE and you are not clearly on a zone
• Labels in the middle of a range with no level
• OF1 against SUPPLY/DEMAND
• Chaotic OF1+OF2+OF3 overlap with no clear level
• Acting on a label alone with no zone/structure context
EXAMPLES
• DEMAND + green OF3 / OF2 → look for LONG after reclaim/confirm
• SUPPLY + red OF3 / OF2 → look for SHORT
• Cyan OF1 in uptrend, pullback into DEMAND → continuation LONG
• Label only, no zone/structure → do not enter
LIMITATIONS
• This is not real footprint / DOM / bid-ask data. Signals are proxies and can be wrong.
• Especially noisy on 1m/3m charts.
• The script does not place trades and does not guarantee results.
• Always combine with your own risk management and market context.
指標

SMC Analytics Pro Hey traders! 👋
Finding a clean, non-lagging Smart Money Concepts (SMC) indicator on TradingView can be frustrating. Most public scripts end up squishing your chart scale , lagging your browser, or cluttering your screen with hundreds of overlapping boxes. 😩
So I decided to code a complete, ultra-precise Smart Money Concepts engine in Pine Script v5—rebuilt from the ground up to keep your charts smooth, clean, and 100% accurate! 🚀✨
The Core Idea: Institutional trading isn't about guessing where price is going—it's about tracking where bank liquidity lives. This indicator maps out market structure, institutional order blocks, and imbalance gaps without crowding your price action.
🔥 Key Features That Make This Unique
Dual Structure Architecture: Automatically plots both Internal Structure (micro scalp breaks) and Swing Structure (macro trend breaks) so you never trade against the major market trend.
Structure-Triggered Order Blocks (OB): No more clutter! OBs are drawn only when a real Break of Structure (BOS) or Change of Character (CHoCH) occurs at the origin of the impulse move.
Real-Time Mitigation Engine: When price retraces and touches an Order Block or fills a Fair Value Gap (FVG), the zone automatically vanishes in Present Mode to keep your chart tidy.
Fixed Chart Scale Guarantee: Unlike other SMC scripts that distort your vertical price scale and make candles look flat, this indicator keeps your chart scaling perfectly proportioned on every single timeframe! 📈
Fair Value Gaps (FVG): Identifies genuine 3-candle imbalance gaps where big money stepped in with aggressive market orders.
Liquidity Pools (EQH / EQL): Highlights Equal Highs and Equal Lows where retail stop losses are sitting waiting to be swept.
Dynamic Equilibrium (50%) Level: Displays the exact 50% midpoint of the active swing range so you always know if you're buying in Discount or selling in Premium .
🛠️ How to Use This in Your Trading Setup
Identify the Macro Trend: Look for solid green/red BOS lines and check if swing points are making Higher Highs (HH) or Lower Lows (LL).
Wait for Price to Enter a Zone: Look for price to retrace back down into an unmitigated Bullish Order Block or fill a Bullish FVG below the Equilibrium (50%) line.
Look for Internal Confirmation: Drop down to a lower timeframe and wait for a dashed iBOS / CHoCH break in your direction before taking the trade! 🎯
⚡ Multi-Timeframe Compatibility
Whether you are scalping the 1-minute chart on CAPITALCOM:NAS100 , day trading Forex on the 15-minute, or swing trading Crypto on the Daily, the logic adapts dynamically to any market and timeframe! 🌍
Inputs can be customized in the settings panel—feel free to tweak the pivot lookbacks to match your personal trading style.
If you find this indicator helpful for your daily analysis, please hit the Boost button 🚀 and leave a comment below! Happy trading! 🙌 指標

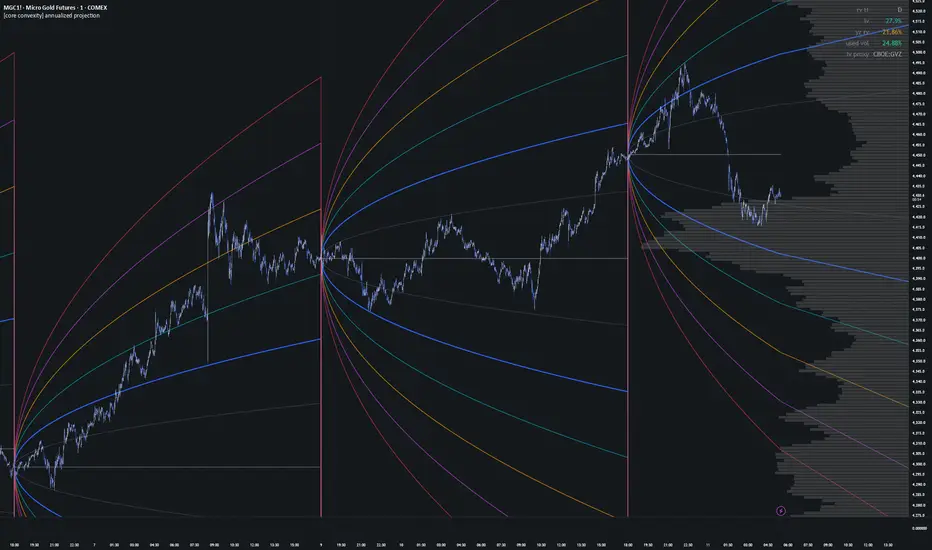
[core convexity] annualized projectionold project
a volatility framework for mapping expected price movement around an anchor using annualized implied and realized volatility.
the core idea is pretty simple: volatility is expressed on a yearly basis, then scaled down to whatever amount of time has actually passed. if annualized volatility is v, the expected standard deviation over some fraction of a year is approximately v × √t. the bands then translate that volatility into price space around the selected anchor using a lognormal-style exponential projection.
that lets the same volatility estimate be used consistently across different horizons. a 20% annualized volatility input does not mean price is expected to move 20% today — it means the one-year standard deviation is roughly 20%, and shorter horizons are scaled by the square-root-of-time relationship.
realized volatility uses the yang-zhang estimator only. it combines overnight moves, open-to-close variance and the rogers-satchell range component, which makes it useful for markets where gaps and intraday range both matter. the result is annualized using the selected number of rv periods per year.
implied volatility can come from an automatically selected volatility proxy, a manual symbol, or a fixed percentage. the volatility model can use iv only, yang-zhang rv only, or blend the two. conceptually, iv represents what the options market is pricing forward while rv represents what the underlying has actually been realizing.
in anchored cone mode, volatility expands outward from a fixed price anchor as elapsed time increases. the width grows with √t, so the cone naturally widens more slowly over time rather than linearly.
in rolling bands mode, the structure behaves more like live volatility bands: the center follows current price and the envelope continuously expands or contracts as the active volatility estimate changes. instead of asking “how far could price move from this old anchor by now?”, it asks “given volatility right now, what does the current expected-move envelope look like?”
standard bands are expressed in sigma multiples, with optional fibonacci-style deviation levels for finer subdivisions. these are volatility-based reference levels, not probability guarantees or directional forecasts.
yang-zhang can run on its own timeframe independently of the chart, including lower-timeframe rv sampling when used on a higher-timeframe chart. the anchor and cone geometry remain separate from the rv timeframe so changing the volatility sampling resolution does not redefine where the cone starts.
forward projection extends the current structure beyond the last bar. anchored mode continues widening from the original anchor, while rolling mode projects the current recalculated envelope as a live snapshot.
all plot colors are implemented with compile-time constant colors so tradingview keeps the normal color controls available in settings → style. 指標

指標

Smart Money Liquidation Exploits [AlgoAlpha]🟠 OVERVIEW
Smart Money Liquidation Exploits maps recent swing highs and lows as liquidity levels, then watches how price reacts when these levels are reached. It focuses on liquidity sweeps where price moves beyond a prior swing with the wick but the candle body remains on the other side of the level.
The indicator combines pivot-based liquidity mapping, wick rejection signals, and structure-based take-profit levels. This helps traders separate a liquidity sweep from a simple break through a previous high or low.
It can use the current chart timeframe or a selected higher timeframe. This lets traders view liquidity and sweep signals from broader market structure while staying on a lower-timeframe chart.
🟠 CONCEPTS
Liquidity Level — A price level formed from a confirmed pivot high or pivot low. Pivot highs represent potential buy-side liquidity, while pivot lows represent potential sell-side liquidity.
Liquidity Sweep — A move where the wick crosses a liquidity level but the candle body stays beyond neither side of that level. A sweep below a pivot low is treated as bullish, while a sweep above a pivot high is treated as bearish.
Pivot Structure — Confirmed swing highs and lows defined by the Pivot Length setting. Consecutive pivots in the same direction are updated when a more extreme high or low forms.
Take-Profit Level — A target created after a valid sweep. For bullish sweeps, the target is the midpoint between the swept low and the latest swing high. For bearish sweeps, it is the midpoint between the swept high and the latest swing low.
Level Expiry — The period during which a liquidity or take-profit level remains active. Levels stop extending after they are reached or after the selected number of bars expires.
🟠 FEATURES
Liquidity Levels — Displays active pivot-based liquidity levels above and below price.
Sweep Signals — Marks bullish sweeps with ▲ and bearish sweeps with ▼ when price wicks through a liquidity level without the candle body crossing it.
Take-Profit Levels — Displays a dotted target after a valid liquidity sweep when an opposing swing is available.
Target Confirmation — Marks completed take-profit targets with a ✅ and connects the original sweep to the target hit.
Higher-Timeframe Mode — Allows liquidity levels, sweeps, targets, and expiry periods to use structure from a selected higher timeframe.
🟠 HOW TO USE
Watch the active liquidity levels around price to identify recent swing highs and lows that price may test.
Look for a ▲ below price when sell-side liquidity is swept. This shows that price moved below a pivot low but the candle body remained above the level.
Look for a ▼ above price when buy-side liquidity is swept. This shows that price moved above a pivot high but the candle body remained below the level.
After a valid sweep, use the dotted take-profit level as the indicator's structure-based target.
Watch for a ✅ when price reaches an active target. The connecting dotted line shows which sweep produced the completed target.
Increase Pivot Length to focus on broader swings, or reduce it to detect smaller local swings.
Enable Higher Timeframe mode when you want the liquidity structure and signals to come from a broader timeframe than the current chart.
Adjust Level Expiry Bars to control how long untouched liquidity and take-profit levels remain active.
🟠 CONCLUSION
Smart Money Liquidation Exploits combines pivot-based liquidity levels, wick-defined liquidity sweeps, and structure-based take-profit targets. It gives traders a visual way to identify rejected liquidity runs and track the price objective associated with each valid sweep. 指標

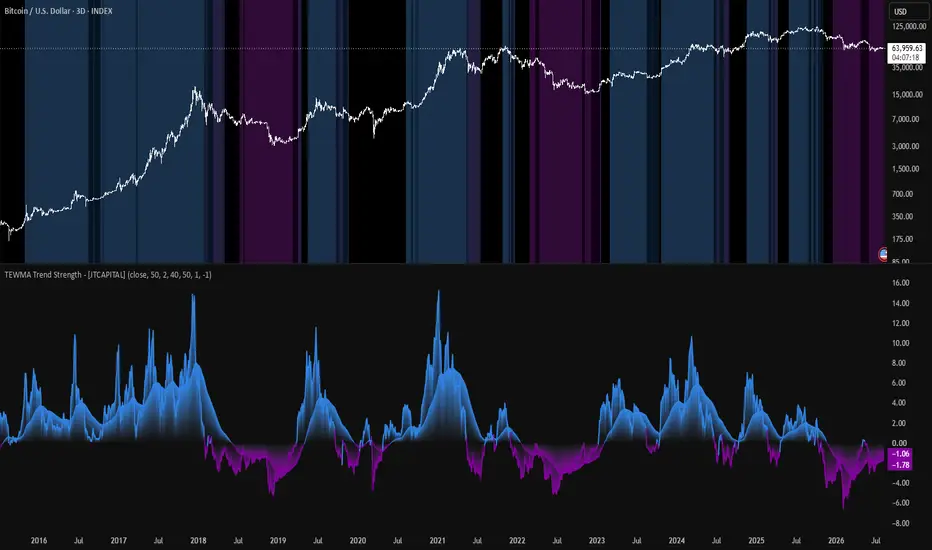
TEWMA Trend Strength - [JTCAPITAL]TEWMA Trend Strength - is a modified way to use Triple Exponentially Weighted Moving Averages (TEMA), Weighted Moving Averages (WMA), Average True Range (ATR), and EMA smoothing to measure the strength and direction of a trend.
Instead of simply determining whether price is above or below a single moving average, the indicator measures how far the current closing price is positioned from a composite trend baseline and normalizes that distance by market volatility using ATR. This produces a dimensionless trend-strength value that can be compared across different volatility environments.
The indicator combines two independently calculated TEWMA structures using different lengths. The first TEWMA is built from the selected source using the primary length, while the second uses a longer dynamically calculated length. These two TEWMA values are then averaged into one composite baseline.
The resulting distance between price and this composite baseline is divided by ATR. This normalization is important because a fixed price distance does not have the same meaning in every market or volatility regime. A move of 500 points can be extremely significant during a quiet market while being relatively insignificant during a highly volatile market. By measuring the distance relative to ATR, the indicator expresses the displacement in terms of the market's recent typical movement range.
A second, EMA-smoothed version of this strength measurement is also calculated. This provides a slower representation of the underlying trend-strength state while the raw strength value remains more responsive to current price movement.
The result is an oscillator designed to show both trend direction and relative trend strength in a single framework.
The indicator works by calculating in the following steps:
Selecting the Price Source
The script begins with a user-selectable source, which defaults to the closing price.
This source is used as the foundation for the entire trend calculation. Because the source is configurable, the underlying calculation does not have to be restricted to the close. The selected source can be changed to other available price series depending on how the user wants the trend baseline to respond to market data.
Using a configurable source makes the underlying TEWMA calculation adaptable without changing the mathematical structure of the indicator.
Defining the Primary TEWMA Length
The user specifies the primary moving-average length through the Length parameter.
This length controls the first trend component of the indicator. A shorter length makes the underlying moving averages react more quickly to price changes, while a longer length produces a slower and more stable representation of the underlying trend.
The default value is 50.
Creating the Second TEWMA Length
The script then creates a second length by multiplying the primary length by the Multiplier parameter.
The calculation is:
Second Length = Primary Length × Multiplier
The resulting value is rounded to the nearest whole number because the moving-average functions require an integer length.
With the default settings:
50 × 2 = 100
Therefore, the first TEWMA uses a length of 50 while the second TEWMA uses a length of 100.
This creates two different trend perspectives: one more responsive and one slower.
Calculating the First Weighted Moving Average
The selected source is first processed through a Weighted Moving Average using the primary length.
A WMA assigns progressively different weights to the observations within its calculation window, giving more importance to more recent observations than older ones.
This means the WMA can react to recent price changes more quickly than a traditional SMA while still providing a smoother representation of price than using raw closing prices.
The first WMA therefore acts as the input into the first TEMA calculation.
Calculating the Second Weighted Moving Average
The same process is repeated using the dynamically calculated second length.
Because this length is normally larger than the primary length, the second WMA represents a slower-moving version of the underlying price structure.
With the default settings, the first WMA uses 50 periods while the second uses 100 periods.
This creates two different smoothing horizons before the data reaches the TEMA calculations.
Applying Triple Exponential Moving Average to the First WMA
The first WMA is passed through a Triple Exponential Moving Average (TEMA).
TEMA uses multiple stages of exponential smoothing to reduce the lag associated with conventional moving averages.
Conceptually, TEMA can be represented as:
TEMA = 3 × EMA1 - 3 × EMA2 + EMA3
Where:
EMA1 is the first EMA of the input.
EMA2 is an EMA of EMA1.
EMA3 is an EMA of EMA2.
The combination of these three stages is designed to reduce lag while retaining smoothing characteristics.
In this indicator, however, TEMA is not applied directly to raw price. It is applied to the already weighted price series produced by the WMA.
This creates a two-stage structure:
Price Source → WMA → TEMA
The resulting value is the first TEWMA component.
Applying Triple Exponential Moving Average to the Second WMA
The second WMA is independently passed through another TEMA calculation using the longer second length.
This produces the second TEWMA component.
The second component reacts more slowly because its underlying WMA uses a longer period. Consequently, it provides a broader representation of the market's trend structure.
The two components therefore serve different purposes within the same baseline:
* The shorter TEWMA provides a more responsive representation of the current trend.
* The longer TEWMA provides a slower representation of the broader trend structure.
Combining the Two TEWMA Components
The two TEWMA values are then averaged together.
The calculation is:
TEWMA = (TEWMA1 + TEWMA2) / 2
This creates a composite trend baseline rather than relying on only one moving-average length.
The benefit of averaging two different smoothing horizons is that the resulting baseline incorporates both a faster and a slower view of price structure.
The shorter component helps keep the baseline responsive, while the longer component provides additional stability.
This combination can reduce the dependence on a single arbitrary moving-average period and creates a more balanced representation of the underlying trend.
Calculating Average True Range
The script independently calculates Average True Range (ATR) using the user-defined ATR Length .
The default ATR length is 40.
ATR measures the recent trading range of the market while accounting for gaps between consecutive bars through the concept of True Range.
True Range is based on the greatest of:
* Current High minus Current Low
* Absolute value of Current High minus Previous Close
* Absolute value of Current Low minus Previous Close
ATR then smooths these True Range values over the selected period.
In this indicator, ATR is not being used as a traditional stop-loss or entry mechanism. Instead, it is used as a volatility normalization factor.
Calculating the Raw Trend Strength
The script measures the distance between the current closing price and the composite TEWMA.
The calculation is:
Strength = (Close - TEWMA) / ATR
This is one of the most important calculations in the indicator.
First, the script calculates:
Close - TEWMA
This determines whether price is above or below the composite trend baseline and by how much.
If the result is positive, the closing price is above the TEWMA.
If the result is negative, the closing price is below the TEWMA.
The difference is then divided by ATR.
This converts the raw price distance into a volatility-adjusted measurement.
For example, a distance of 100 price units does not have the same significance in a market with an ATR of 20 as it does in a market with an ATR of 200.
When ATR is 20:
100 / 20 = 5
When ATR is 200:
100 / 200 = 0.5
The same absolute price distance therefore produces very different strength readings depending on the market's volatility.
This is the primary reason for incorporating ATR into the strength calculation.
Interpreting the Zero Line
Because the strength calculation is based on Close - TEWMA , the zero line has a direct mathematical meaning.
When:
Strength > 0
the closing price is above the composite TEWMA.
When:
Strength < 0
the closing price is below the composite TEWMA.
Therefore, the zero line represents the point where price and the composite TEWMA are equal.
This makes the zero line the central directional reference of the oscillator.
Smoothing the Strength Measurement
The raw strength value is then passed through an Exponential Moving Average.
The smoothing period is controlled by Smoothing Length , which defaults to 50.
The calculation can therefore be represented as:
Smoothed Strength = EMA(Strength, Smoothing Length)
Unlike the raw strength measurement, which reacts directly to changes in the current price-to-TEWMA relationship, the smoothed line incorporates previous strength values.
Because EMA gives greater weight to more recent observations, it remains responsive while filtering out some of the shorter-term fluctuations in the raw oscillator.
This creates two complementary views:
* Raw Strength shows the more immediate price displacement from the TEWMA.
* Smoothed Strength shows a slower representation of the underlying strength condition.
Assigning the Raw Strength Trend Color
The raw strength line changes color according to whether its value is above or below zero.
When strength is positive, the line uses the bullish color.
When strength is negative, the line uses the bearish color.
The color therefore directly corresponds to the mathematical relationship between price and the composite TEWMA.
It does not represent a separate calculation or additional signal filter.
Assigning the Smoothed Strength Trend Color
The same directional concept is applied to the smoothed strength line.
When the smoothed strength is above zero, it receives the bullish color.
When the smoothed strength is below zero, it receives the bearish color.
This makes it possible to visually distinguish the current normalized strength state from the slower smoothed state.
Plotting the Raw Strength
The raw strength value is plotted as the primary oscillator.
Because the indicator is declared with overlay = false , the oscillator is displayed in its own pane rather than directly over the price chart.
The raw strength plot uses a thicker line to emphasize the more responsive component of the calculation.
Filling Between Raw Strength and Zero
The script also creates an invisible zero reference plot and fills the area between the raw strength line and zero.
The fill follows the same bullish or bearish color assignment as the raw strength line.
This makes positive and negative deviations visually easier to identify.
When the oscillator is above zero, the area between the strength line and zero represents positive displacement from the TEWMA.
When it is below zero, the corresponding area represents negative displacement.
Plotting the Smoothed Strength
The smoothed strength is plotted separately using a thinner line.
Because this line is an EMA of the raw strength, it reacts more gradually to changes.
This makes it useful for visually separating short-term fluctuations in normalized trend strength from the broader strength condition represented by the smoothed value.
Filling Between Smoothed Strength and Zero
The indicator also fills the area between the smoothed strength line and zero.
The fill color follows whether the smoothed strength is positive or negative.
Consequently, the oscillator visually contains two layers of information:
* The raw strength component.
* The smoothed strength component.
Defining the Upper Strength Threshold
The Upper parameter defines a positive threshold for the background strength condition.
Its default value is 1.
The script checks whether the raw strength exceeds this threshold:
Strength > Upper
When that condition is true, the chart background receives a bullish background highlight.
The same upper threshold is also applied to the smoothed strength:
Smoothed Strength > Upper
This means the background can identify situations where normalized strength has moved beyond the selected positive threshold.
Defining the Lower Strength Threshold
The Lower parameter defines the negative threshold.
Its default value is -1.
The raw strength is checked against:
Strength < Lower
and the smoothed strength is checked against:
Smoothed Strength < Lower
When either respective condition is met, the corresponding bearish background condition is applied.
The default range therefore places the main strength thresholds at approximately +1 and -1 ATR of normalized displacement from the composite TEWMA.
Background Regime Visualization
The script uses the threshold calculations to create background highlights on the chart.
The raw strength produces a bullish background condition when it exceeds the upper threshold and a bearish background condition when it falls below the lower threshold.
The smoothed strength uses the same threshold framework.
Values between the upper and lower thresholds do not receive the bullish or bearish threshold highlight.
This creates a visual distinction between ordinary positive/negative displacement and stronger normalized displacement.
Buy and Sell Conditions:
This indicator does not contain explicit buy or sell conditions, entries, exits, alerts, or trade execution logic.
Instead, it is designed as a trend-strength oscillator .
The primary directional interpretation comes from the zero line:
* When the raw strength is above 0, price is above the composite TEWMA.
* When the raw strength is below 0, price is below the composite TEWMA.
* When the smoothed strength is above 0, the smoothed trend-strength state is positive.
* When the smoothed strength is below 0, the smoothed trend-strength state is negative.
The upper and lower thresholds provide an additional measurement of the magnitude of the normalized displacement:
* Strength above the upper threshold indicates that price is positioned more than the selected positive ATR multiple above the composite TEWMA.
* Strength below the lower threshold indicates that price is positioned more than the selected negative ATR multiple below the composite TEWMA.
The smoothed line can be used to observe whether the broader strength condition agrees with the raw strength measurement.
For example, a user may choose to interpret a positive raw strength together with positive smoothed strength as stronger directional alignment than a positive raw strength value occurring while the smoothed measurement remains negative.
However, these are interpretations of the indicator's measurements rather than coded buy or sell rules. The script itself does not automatically define a trade entry simply because one of these conditions occurs.
This distinction is important because the indicator measures market structure and normalized trend strength rather than providing a complete trading strategy.
Features and Parameters:
* Source - Selects the price series used as the input for the WMA calculations. The default source is Close.
* Length - Defines the primary length used for the first WMA and TEMA calculation. The default value is 50.
* Multiplier - Multiplies the primary length to determine the second TEWMA length. The default value is 2. With a Length of 50, this produces a second length of 100.
* ATR Length - Determines the period used to calculate ATR for volatility normalization. The default value is 40.
* Smoothing Length - Determines the EMA period used to smooth the raw strength measurement. The default value is 50.
* Upper - Defines the positive normalized-strength threshold used for the bullish background condition. The default value is 1.
* Lower - Defines the negative normalized-strength threshold used for the bearish background condition. The default value is -1.
* Raw Strength - Displays the current ATR-normalized distance between closing price and the composite TEWMA.
* Smoothed Strength - Displays an EMA-smoothed version of the raw strength measurement.
* Zero Line - Represents the point where closing price is equal to the composite TEWMA.
* Threshold Backgrounds - Visually highlights situations where raw or smoothed strength exceeds the configured upper or lower thresholds.
Specifications:
Weighted Moving Average (WMA)
The Weighted Moving Average is a moving average that assigns different weights to the observations within its calculation period.
More recent values receive greater influence than older values.
Compared with a Simple Moving Average, which gives every observation the same weight, WMA emphasizes the more recent portion of the selected price history.
In this indicator, WMA is used as the first smoothing stage before the data enters the TEMA calculation.
This creates a smoother input for TEMA while retaining greater responsiveness to recent price changes than an equally weighted average.
Triple Exponential Moving Average (TEMA)
Triple Exponential Moving Average is a multi-stage exponential smoothing method designed to reduce the lag that can occur with conventional moving averages.
The underlying calculation uses three consecutive EMA stages:
EMA1 = EMA(Input)
EMA2 = EMA(EMA1)
EMA3 = EMA(EMA2)
These are combined approximately as:
TEMA = 3 × EMA1 - 3 × EMA2 + EMA3
The mathematical combination attempts to compensate for some of the lag introduced by repeated exponential smoothing.
In this indicator, TEMA is applied after WMA rather than directly to price.
This creates the specific structure:
Selected Source → WMA → TEMA
That combination is the basis of the indicator's TEWMA concept.
TEWMA
TEWMA in this script refers to the combination of a Weighted Moving Average and a Triple Exponential Moving Average.
Each TEWMA component is therefore produced through a WMA followed by TEMA.
The script creates two separate TEWMA values using different lengths.
The first uses the primary length.
The second uses the primary length multiplied by the user-defined multiplier.
The two resulting values are then averaged.
This gives the final baseline a combination of a faster and slower trend perspective.
Dual-Length TEWMA Structure
The indicator does not rely on a single TEWMA.
Instead, it calculates:
TEWMA1 = TEMA(WMA(Source, Length), Length)
and:
TEWMA2 = TEMA(WMA(Source, Length2), Length2)
where:
Length2 = round(Length × Multiplier)
The two values are then averaged.
This is important because a single moving-average length represents only one smoothing horizon.
The dual-length structure allows the composite baseline to incorporate both a more responsive trend component and a slower trend component.
The averaging process creates a single reference value from those two perspectives.
Composite TEWMA
The final TEWMA is calculated as:
TEWMA = average(TEWMA1, TEWMA2)
or mathematically:
TEWMA = (TEWMA1 + TEWMA2) / 2
This composite value acts as the central trend baseline of the entire indicator.
Every raw strength value is calculated relative to this baseline.
Therefore, the TEWMA is not simply plotted as a moving average for visual reference; it directly determines the numerator of the strength calculation.
Average True Range (ATR)
Average True Range is a volatility measurement that estimates the typical trading range of the market over a selected period.
It is based on True Range, which accounts for both the current candle's high-low range and gaps relative to the previous closing price.
The ATR is used here as a normalization factor .
This is a critical part of the indicator because the raw distance between price and TEWMA is not directly comparable across different volatility conditions.
Dividing the price displacement by ATR expresses the distance in volatility-adjusted terms.
The resulting value can therefore be interpreted as the approximate number of ATR units that price is positioned above or below the composite TEWMA.
ATR Normalization
The core normalization is:
(Close - TEWMA) / ATR
The numerator determines direction and absolute displacement.
The denominator determines the scale of the market's recent volatility.
This combination allows the indicator to transform a raw price difference into a normalized strength measurement.
A positive result means price is above the TEWMA.
A negative result means price is below the TEWMA.
The magnitude indicates how large that displacement is relative to ATR.
Strength
Strength is the primary oscillator produced by the script.
Its exact calculation is:
Strength = (Close - TEWMA) / ATR
This value combines three important concepts:
* Price direction relative to the trend baseline.
* Distance from the trend baseline.
* Current market volatility.
The result is a normalized oscillator rather than a value expressed directly in price units.
Zero Line
The zero line is mathematically significant because it represents the point where:
Close = TEWMA
If the closing price moves above the TEWMA, strength becomes positive.
If the closing price moves below the TEWMA, strength becomes negative.
The zero line therefore separates positive and negative trend displacement.
EMA
The Exponential Moving Average assigns more weight to recent observations while retaining information from previous values.
In this script, EMA is used to smooth the calculated strength rather than the original price.
This distinction is important.
The indicator first calculates the complete ATR-normalized strength measurement and only then applies EMA smoothing.
The structure is therefore:
Price → TEWMA → ATR Normalized Strength → EMA
This allows the smoothing process to operate directly on the final trend-strength measurement.
Smoothed Strength
Smoothed strength is calculated as:
EMA(Strength, Smooth Length)
Because the input to the EMA is already normalized by ATR, the smoothed line represents the smoothed evolution of volatility-adjusted distance from the composite TEWMA.
This can help distinguish persistent strength from shorter-lived fluctuations in the raw oscillator.
The smoothing length determines how quickly the line responds.
A shorter smoothing length causes the smoothed measurement to react more quickly, while a longer smoothing length makes it more gradual.
Upper Threshold
The upper threshold determines when the strength measurement is considered sufficiently positive to trigger the bullish background condition.
With the default value of 1, the condition is:
Strength > 1
Because strength is normalized by ATR, this means the closing price is more than approximately one ATR above the composite TEWMA according to the current ATR calculation.
The same threshold is applied independently to the smoothed strength.
The threshold itself does not create a buy signal.
Lower Threshold
The lower threshold determines when the strength measurement enters the corresponding negative threshold region.
With the default value of -1, the condition is:
Strength < -1
This means the closing price is positioned more than approximately one ATR below the composite TEWMA.
The same concept is applied to the smoothed strength.
The lower threshold therefore acts as a normalized downside-strength boundary rather than a coded sell signal.
Volatility Normalization
Volatility normalization is one of the key concepts behind the indicator.
Without ATR normalization, the calculation would simply measure:
Close - TEWMA
That value is expressed in absolute price units.
By dividing it by ATR, the script asks a different question:
"How large is the price displacement relative to the market's recent typical range?"
This makes the strength value dependent on both price displacement and volatility.
That combination is particularly relevant when comparing periods in which the market's volatility changes substantially.
Trend Direction
The directional component of the indicator comes directly from the sign of the normalized strength.
Positive values indicate that price is above the composite TEWMA.
Negative values indicate that price is below the composite TEWMA.
The indicator therefore does not require a separate bullish/bearish calculation. Direction is inherently contained within the numerator of the strength formula.
Trend Strength
Trend strength is represented by the magnitude of the normalized value.
A value close to zero indicates that price is relatively close to the composite TEWMA when measured against ATR.
A larger positive value indicates greater positive displacement relative to ATR.
A larger negative value indicates greater negative displacement relative to ATR.
It is therefore important to distinguish direction from magnitude :
* The sign indicates which side of the TEWMA price is on.
* The magnitude indicates how far price is displaced relative to ATR.
Raw Strength vs. Smoothed Strength
The two oscillator components provide different information.
The raw strength responds directly to the latest relationship between closing price, TEWMA, and ATR.
The smoothed strength incorporates previous strength values through EMA smoothing.
This creates a useful distinction between immediate and persistent conditions.
A rapidly changing raw strength can reveal a developing change in the price-to-trend relationship, while the smoothed value can provide a slower representation of whether that change is becoming established.
The script therefore combines responsiveness and stability without requiring a second independent indicator.
Why Combine WMA and TEMA?
WMA and TEMA perform different roles in the calculation.
WMA provides weighted smoothing that places greater emphasis on recent observations.
TEMA then applies a multi-stage exponential smoothing structure intended to reduce lag compared with conventional moving averages.
Using them sequentially creates a trend baseline that is smoothed while still designed to remain responsive to changes in price.
The purpose is not simply to combine two moving-average names, but to create a specific transformation of the selected source before it is used in the strength calculation.
Why Use Two TEWMA Lengths?
A single moving-average length forces the indicator to represent trend using one specific time horizon.
The dual-length structure provides two different perspectives.
The shorter TEWMA can respond more quickly to changes in price structure.
The longer TEWMA changes more gradually and represents a broader trend component.
Averaging them produces the composite TEWMA used by the strength calculation.
This makes the baseline less dependent on a single smoothing horizon and combines faster and slower trend information into one reference value.
Why Combine TEWMA With ATR?
The TEWMA establishes the trend reference.
ATR establishes the volatility scale.
These measurements answer different questions.
The TEWMA asks:
"Where is the smoothed trend baseline?"
ATR asks:
"How large are the market's typical recent price movements?"
The strength calculation combines those two concepts by measuring the distance between price and trend baseline in ATR units.
This is what transforms the indicator from a simple moving-average distance oscillator into a volatility-adjusted trend-strength measurement.
Why Add EMA Smoothing to the Strength Measurement?
The raw strength calculation can fluctuate as price moves around the composite TEWMA.
Applying an EMA after normalization provides a second representation of that strength.
Importantly, the EMA is not smoothing the original price before the TEWMA calculation. It is smoothing the completed strength measurement.
This means the smoothed line represents the recent history of the normalized trend-strength state itself.
The combination therefore creates two layers:
Raw Strength = current normalized displacement
Smoothed Strength = smoothed normalized displacement
How the Components Work Together
The complete calculation can be simplified into the following chain:
Selected Source
↓
WMA using Primary Length
↓
TEMA using Primary Length
↓
TEWMA 1
And simultaneously:
Selected Source
↓
WMA using Primary Length × Multiplier
↓
TEMA using the Longer Length
↓
TEWMA 2
The two are then combined:
TEWMA 1 + TEWMA 2
↓
Average
↓
Composite TEWMA
At the same time:
High, Low and Close
↓
True Range
↓
ATR
The final strength calculation then becomes:
(Close - Composite TEWMA) / ATR
The resulting strength value is finally passed through:
EMA(Strength, Smoothing Length)
to create the smoothed strength measurement.
The entire indicator can therefore be summarized as:
Weighted price smoothing → TEMA lag reduction → dual-length trend baseline → ATR volatility normalization → strength oscillator → EMA strength smoothing
Visual Interpretation
The indicator uses several visual elements to make the calculations easier to interpret.
The raw strength line changes color according to whether it is above or below zero.
The smoothed strength line independently changes color according to its own relationship with zero.
The areas between each oscillator and the zero line are filled using the corresponding directional color.
The background highlights are reserved for conditions where the selected upper or lower threshold is exceeded.
This creates a visual hierarchy:
* Zero line = directional reference.
* Raw strength = immediate normalized displacement.
* Smoothed strength = slower strength state.
* Upper/lower thresholds = stronger normalized displacement regions.
* Background highlights = visual identification of threshold conditions.
Using the Indicator
The indicator can be used as a contextual trend-strength tool rather than as a standalone automated trading system.
The zero line can be used to identify whether price is currently above or below the composite TEWMA.
The raw strength can be observed when a trader wants a more responsive measurement of changes in the price-to-trend relationship.
The smoothed strength can be observed when a trader wants a slower representation of that same relationship.
The upper and lower thresholds can be adjusted to change how extreme a normalized displacement must become before the background highlights the condition.
Increasing the absolute threshold values makes the highlighted conditions more selective because a larger normalized displacement is required.
Reducing the absolute threshold values makes the threshold conditions easier to reach.
Similarly, changing the TEWMA lengths changes the responsiveness of the underlying trend baseline, while changing the ATR length changes the volatility reference used for normalization.
The smoothing length controls how quickly the smoothed strength responds to changes in the raw strength.
These parameters therefore influence different parts of the calculation rather than simply changing the same signal in different ways.
Important Considerations
This indicator measures the relationship between price, a composite TEWMA trend baseline, and ATR-based volatility.
It does not predict future prices and does not guarantee that a trend will continue after a strength condition appears.
A strong positive strength value means that price is currently positioned substantially above the composite TEWMA relative to the calculated ATR. It does not mathematically guarantee that price will continue higher.
Likewise, a strong negative value means that price is substantially below the composite TEWMA relative to ATR, but it does not guarantee continued downside movement.
The indicator also does not contain position sizing, stop-loss, take-profit, trade execution, or backtesting logic.
It should therefore be understood as a trend-strength and market-context tool , rather than a complete trading strategy.
Default Calculation Structure
With the default parameters, the indicator uses:
* Source: Close
* Primary Length: 50
* Multiplier: 2
* Secondary Length: 100
* ATR Length: 40
* Smoothing Length: 50
* Upper Threshold: 1
* Lower Threshold: -1
This results in a composite trend baseline constructed from 50-period and 100-period WMA-to-TEMA structures, followed by ATR normalization using a 40-period ATR and EMA smoothing of the resulting strength value using a 50-period EMA.
The default +1 and -1 thresholds represent positive and negative normalized displacement levels around the composite TEWMA.
Summary
TEWMA Trend Strength combines multiple calculations into one normalized trend-strength framework.
Rather than using a single moving average and simply checking whether price is above or below it, the script first constructs two TEWMA components using different lengths, averages them into a composite trend baseline, measures the distance between closing price and that baseline, and then normalizes that distance by ATR.
The result is a strength value where both direction and magnitude are meaningful.
The zero line identifies the side of the composite TEWMA on which price is currently positioned.
The magnitude of the value expresses that displacement relative to recent volatility.
The additional EMA smoothing provides a slower view of the strength condition, while the configurable upper and lower thresholds provide a visual way to identify larger normalized deviations.
The combination of WMA + TEMA creates the underlying trend representation, the dual-length structure combines faster and slower trend information, ATR converts the price displacement into a volatility-adjusted measurement, and EMA smoothing provides a second, slower representation of the resulting strength.
Together, these components form a single oscillator designed to help visualize trend direction, normalized trend strength, and the persistence of that strength within one calculation framework.
Enjoy!
指標

Hybrid Breakout | VCP-Inspired TrendTrend Squeeze Breakout
Trend Squeeze Breakout is a trend-following momentum strategy designed to identify stocks in strong established uptrends that are consolidating into relatively tight trading ranges before attempting a breakout.
The strategy combines a simplified Minervini-style trend template, volatility contraction, volume confirmation, and stop-entry breakout execution. It is designed primarily for swing trading and is intended to participate in strong upward price expansions while filtering out many breakouts occurring in weak or declining trends.
Strategy Explanation
The strategy follows a simple sequence:
Identify a strong uptrend
A long setup requires:
Price above the 50-period SMA
50 SMA above the 150 SMA
150 SMA above the 200 SMA
200 SMA rising
200 SMA continuing to rise over the selected lookback period
50 SMA not declining
This establishes that the stock is already in a structurally bullish environment before considering an entry.
Identify a volatility contraction
The strategy looks for periods where recent price movement has become unusually tight.
It evaluates both:
Recent high-low range
Recent closing-price range
The high-low range is also compared with its historical percentile over the selected lookback period. This allows the strategy to identify relatively quiet consolidation periods rather than relying on a fixed volatility threshold alone.
Confirm volume
When the volume filter is enabled, breakout volume must exceed the moving-average volume baseline by the selected multiplier.
The default requirement is:
Volume > 20-period average volume × 1.2
This is intended to provide additional confirmation that the breakout is supported by meaningful participation.
Enter on a breakout
When the trend, contraction, and volume conditions are satisfied, the strategy places a stop-entry order above the recent high.
The default breakout lookback is 3 bars, allowing the strategy to attempt to enter as price moves through the recent consolidation high rather than simply buying while the stock remains inside the range.
Manage the position
Positions use tiered profit-taking:
25% closed at +10%
50% closed at +20%
Remaining position closed at +30%
Default stop loss at -8%
This allows the strategy to realize some profits during the initial move while maintaining exposure to larger momentum extensions.
Features
Trend Filter — 50/150/200 SMA bullish alignment
Long-Term Trend Confirmation — Requires the 200 SMA to be rising
Volatility Squeeze Detection — Identifies unusually tight recent ranges
Range Percentile Filter — Compares current volatility with historical volatility
Close-Range Filter — Detects tight price consolidation
Volume Confirmation — Optional volume expansion requirement
Stop-Entry Breakout — Enters only when price breaks the recent high
Tiered Profit Taking — Three configurable profit targets
Percentage-Based Stop Loss — Adjustable downside protection
Date Filter — Allows users to restrict backtests to a specific period
Configurable Parameters — Trend, volatility, volume, breakout, and risk settings can all be adjusted
Tips for Use
Use on liquid stocks
The strategy is generally better suited to liquid stocks and ETFs with sufficient trading volume. Extremely illiquid securities can produce unrealistic backtest results because of spreads and execution differences.
Start with daily charts
The strategy is particularly suited to identifying multi-day or multi-week momentum breakouts. Daily charts are a good starting point when evaluating the strategy.
Avoid optimizing every parameter
The many adjustable parameters make it possible to overfit the strategy to a particular stock or historical period. Test parameter changes across multiple securities and different market environments rather than optimizing exclusively for one chart.
Treat the volume filter as confirmation, not a guarantee
High volume can strengthen a breakout signal, but it does not guarantee that the breakout will succeed.
Test across different market conditions
Trend-following breakout systems typically perform differently during strong bull markets, corrections, sideways markets, and high-volatility periods. Evaluate results across multiple market regimes before relying on the strategy.
Pay attention to execution
The strategy uses stop-entry orders above recent highs. In live trading, gaps, slippage, spreads, and intrabar price movement can cause actual execution prices to differ from backtested results.
Important Note
This strategy is inspired by trend-template and volatility-contraction concepts, but it is not a complete implementation of a textbook VCP. It uses a simplified statistical contraction model rather than explicitly identifying multiple successive contractions, contraction depths, and their associated volume characteristics.
Backtest results are hypothetical and do not guarantee future performance. Always consider commissions, slippage, liquidity, position sizing, and market conditions when evaluating a strategy.
Recommended starting configuration: Daily timeframe, liquid stocks, default trend filter, volume confirmation enabled, and the default tiered risk-management settings.
策略

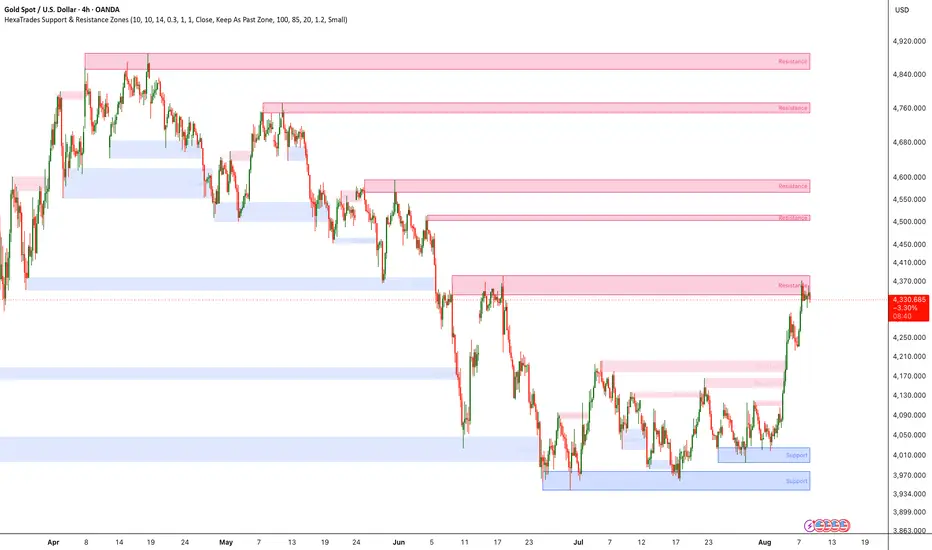
Consolidation Ranges & Breakout Map [MQLSoftware]Consolidation Ranges & Breakout Map reads the market's sideways regime as a measurable object. It detects compression with an authored Range Compression Index, fixes the consolidation box only after enough confirmed evidence, tracks how the box resolves — breakout, measured-move projection reached, false break, or expiry — and reports the measured base rates of those outcomes counted on the chart's own history.
This is a visual analytical tool for chart study. It does not execute trades and does not provide financial advice.
Key Features
Consolidation boxes fixed on confirmed evidence only: a candidate must hold the compression threshold for a minimum number of confirmed bars before it becomes a live range — borders never move backwards once fixed
Amber forming frame while compression is still building, so you see the candidate before it commits
Breakouts by confirmed CLOSE beyond the border plus an ATR buffer — wicks and gaps alone never trigger a breakout
Measured-move projections (1× and 1.618× the range height by default) drawn from the broken border — a geometric reference derived from the range's own size
Outcome tracking on confirmed bars: ✓ printed when the 1× projection is reached, ✕ false break when price closes back inside within the fakeout window, quiet expiry when the resolution window runs out
Range invalidation discipline: a box that "breathes" beyond its edge-update budget or outgrows the maximum width is annulled and excluded from the statistics, so pseudo-ranges never contaminate the base rates
Measured base rates in the panel: share of upside breakouts, share that reached the 1× projection, share of false breaks, median bars to 1×, median range length — each with its sample size
Higher-timeframe context band (rolling HTF high/low), optional volume-expansion quality gate, four panel modes, five confirmed-bar alerts plus one dynamic JSON alert
Core Concept — what is original here
TradingView has many box-drawing and Darvas-style tools; most fix a rectangle from a simple highest/lowest lookback and leave the interpretation to the reader. This script makes the detector itself measurable and then closes the loop by counting what actually happened. Three specific algorithmic elements:
1. The Range Compression Index (RCI). A 0–100 composite authored for this script: RCI = 100 · (0.40 · ineff + 0.35 · vc + 0.25 · cont), where ineff = 1 − min(ER, 1) is movement inefficiency (the inverse Kaufman efficiency ratio — net displacement over the evaluation window divided by the bar-to-bar path traveled), vc is volatility compression (short ATR against a 4× longer ATR window, rescaled to 0..1), and cont is containment — the share of closes inside the central 90% of the candidate box. Each component measures a different facet of "sideways": no net progress, contracting volatility, clustering closes. A candidate also has to pass a geometry gate — its width may not exceed a configurable multiple of ATR. The sensitivity presets set the RCI threshold (Low 70, Normal 62, High 55).
2. The consolidation → breakout state machine. SEEKING → FORMING → LIVE → BREAK UP / BREAK DOWN → RESOLVED / FALSE BREAK / EXPIRED, with every transition on confirmed bars only. The box is fixed only after the minimum number of confirmed compression bars. A fixed border may be widened by a wick within the edge tolerance a limited number of times — each update on a confirmed bar and counted; beyond the budget the box is invalidated and never enters the statistics. A breakout requires a confirmed close beyond the border plus the ATR buffer; a bar that pierces both borders resolves by its close; a close back inside within the fakeout window is classified as a false break (checked before the projection within the same bar, deliberately conservative). The resolution window defaults to three times the range's own duration, capped at 200 bars.
3. Measured base rates. The panel reports observed frequencies counted on this chart's loaded history: how often ranges broke upward, how often the breakout reached the 1× measured-move projection, how often the break turned out false, the median bars to 1× and the median range length — each with its sample size. Below a minimum sample the panel prints the sample gate instead of a percentage, so small-sample noise is never dressed up as a statistic. Observed frequencies, not assumptions, and no claims attached to them.
Anatomy of the Display
Live range box — steel border with a faint fill, header with the range's duration and height in ATR; midline optional
Amber dashed frame — a FORMING candidate: compression is building but the box is not yet committed
▲ / ▼ breakout markers on the confirmed breakout bar (Descriptive or Compact style)
Dashed projection lines from the broken border with 1× and 1.618× labels at the right edge
✓ 1× printed where the projection is reached, ✕ false break where price closed back inside
Translucent higher-timeframe band with the rolling HTF high/low and a timeframe tag
Panel (Off / Minimal / Normal / Large): state in plain words (SEEKING / COMPRESSING n/m / RANGE LIVE / BROKE UP / BROKE DOWN / FALSE BREAK), the live Range Compression Index with a five-block meter, range height and duration, position inside the range, and in Large mode the measured base-rate section
Notes on Repainting
All state transitions, breakout/outcome markers, statistics counters and alerts fire on confirmed bars only and never move once printed
Box borders are fixed on the confirming bar and never move backwards; the only permitted change is a forward widening within the edge tolerance, on a confirmed bar, a limited number of times
The live box's right edge, the FORMING candidate frame and the panel's live rows update intrabar — visual context, not signals
The higher-timeframe band uses one request.security call with lookahead off and reads the previous confirmed HTF value — no future data anywhere
Display inputs only gate drawing; they never change the state machine, the counters or the alerts
Typical Analysis Workflow
Watch the panel's Compression row: a rising RCI with an amber forming frame means a candidate is building
When RANGE LIVE prints, read the box header — a 40-bar range 1.2 ATR tall is a different regime than an 8-bar pause
Treat the breakout marker as a measured event, not an invitation: the base rates tell you how often breakouts on this chart reached the projection versus failed back into the box
Use the false-break share as regime context — some markets punish breakout chasing far more often than others, and the panel will say so with a sample size
Check the higher-timeframe band: a local range at the edge of the senior range is a different situation than one in the middle of it
Configuration
Range Detection — compression sensitivity preset (RCI threshold), evaluation window, minimum confirmed bars to fix a box, maximum width in ATR, containment threshold, edge tolerance and the edge-update budget
Breakout — ATR buffer for the confirmed close, fakeout window, both projection multiples, resolution window (auto = 3× range duration), optional volume-expansion gate with its multiple
Higher-Timeframe Context — band on/off, HTF (empty = auto: 4× chart timeframe capped at 1W), HTF range length
Statistics — base-rate section on/off, minimum sample to display a percentage
Visual — panel size and position, marker style (Descriptive / Compact), projections, midline, how many past ranges to keep, and the four identity colors (all inputs; dark-theme defaults)
Markets and Timeframes
Any symbol and timeframe. All thresholds are expressed in ATR and percentiles of the chart's own behavior, so the detector self-calibrates per instrument. On symbols without volume data the volume gate is ignored automatically and the panel says so. On slow timeframes (1D/1W) the sample gate will hide the percentages until enough ranges have resolved — that is the honesty rule, not a defect.
Alerts
Range confirmed · Range breakout up · Range breakout down · False break · 1× projection reached — all evaluated on confirmed bars from the same event flags that draw the markers, plus one dynamic alert() with a JSON payload (event, symbol, timeframe, box borders, break level, height in ATR). 指標

BIST30 to SP 500 ATR Momentum RiderBIST30 to S&P 500 — ATR Momentum Rider
BIST30 to S&P 500 — ATR Momentum Rider is a long-only daily strategy built to test a compact and auditable trend-following structure across index futures.
The name describes the research scope—from BIST30 to S&P 500 and other major index futures. It does not mean that the public parameters were optimized on BIST30. Parameter selection used Mini-DAX, E-mini S&P 500, E-mini Russell 2000, EURO STOXX 50, and Nikkei 225 Mini futures. Turkish index futures were kept outside parameter selection and used only as transferability stress tests.
Entry logic
The raw SET event occurs when HMA 8 > HMA 9 > HMA 20 becomes true for the first time. On that same daily close, the strategy calculates the three-day HMA20 slope in ATR units:
(HMA20 - HMA20 ) / (3 × ATR14)
The setup is accepted only when this value is at least -0.180 ATR per day. The threshold does not require a rising HMA20; it permits a mild decline and rejects setups where the slow trend is deteriorating more sharply. The filter is evaluated only on the first establishment of the HMA order. A rejected setup does not enter later inside the same uninterrupted regime.
An accepted setup creates a market order for the next available session open. The decision uses only values known at the daily close.
Exit logic
The strategy has one public exit stage:
K1-A: activation threshold. Maximum favorable excursion is divided by the ATR value known when the entry order is created. Default: 1.50 ATR.
K1-T: trail distance from the highest high observed during the campaign. Default: 5.75%.
K1-W: minimum waiting interval before a K1 close decision can act. Default: 4 sessions.
Once K1 is active, its absolute trail can only rise. An activation reached on the current bar becomes actionable from the next bar, so the activation bar cannot stop itself retroactively. A daily close at or below the active K1 line creates a market exit for the next available open. If a fresh accepted SET appears while a position is open, the campaign is refreshed at the next open.
Research process and held-out results
The K1 values were selected on January 2020–December 2023 data using equal-weight, percentage-normalized metrics across the five international contracts. Keeping the K1 engine fixed, the three-day slope threshold was then scanned from -0.400 to +0.050 ATR/day in 0.001 steps on the same development interval. The exact PF-priority plateau peak was -0.176; the operational value was rounded and locked at -0.180 to avoid publishing a fragile, over-precise threshold.
January 2024–July 2026 was not used to select the slope threshold. In this held-out interval:
Raw setups: 153
Accepted setups/trades: 102 (33.3% reduction)
Positive international instruments: 5 of 5
Median profit factor: 3.46 versus 1.94 without the slope filter
Median normalized net return: 39.3% versus 37.9% without the slope filter
Median return/max-drawdown ratio: 2.32 versus 2.16 without the slope filter
These figures use one adverse minimum tick per market fill and no commission, tax, funding, or roll cost. They are historical research results, not a forecast.
The held-out BIST stress test remained weak: the three Turkish contracts had a median profit factor of 0.77 with the slope filter. Therefore, this public version is better viewed as an international index-futures research strategy. It is not a replacement for a dedicated BIST30 live system.
Use the strategy on standard daily candles. Review each symbol's contract multiplier, session, continuous-contract construction, commissions, roll costs, and margin settings before interpreting Strategy Tester results. Changing the HMA, ATR, K1, or execution settings creates a different, unvalidated configuration.
This script is a research and educational tool, not investment advice. Past performance does not guarantee future results.
BIST30 to S&P 500 — ATR Momentum Rider
HMA 8/9/20 kuruluşunu, sabit ATR-normalize HMA20 eğim filtresini ve yalnız yukarı taşınan tek tepe trailini birleştiren açık kaynak, long yönlü günlük strateji.
BIST30 to S&P 500 — ATR Momentum Rider, farklı endeks vadelilerinde sade ve denetlenebilir bir trend takip yapısını sınamak amacıyla hazırlanmış, yalnız long çalışan günlük bir stratejidir.
İsim, araştırmanın BIST30'dan S&P 500'e ve diğer büyük endeks vadelilerine uzanan kapsamını anlatır. Açık kaynak parametrelerinin BIST30 üzerinde optimize edildiği anlamına gelmez. Parametre seçiminde Mini-DAX, E-mini S&P 500, E-mini Russell 2000, EURO STOXX 50 ve Nikkei 225 Mini vadeli kontratları kullanılmıştır. Türkiye endeks vadelileri parametre seçiminin dışında tutulmuş ve yalnız taşınabilirlik stres testi olarak değerlendirilmiştir.
Giriş mantığı
Ham SET olayı, HMA 8 > HMA 9 > HMA 20 sıralamasının ilk kez oluştuğu günlük kapanışta doğar. Strateji aynı kapanışta HMA20'nin üç günlük eğimini ATR cinsinden hesaplar:
(HMA20 - HMA20 ) / (3 × ATR14)
Kuruluş yalnız bu değer -0,180 ATR/gün veya daha yüksekse kabul edilir. Eşik HMA20'nin mutlaka yükselmesini istemez; hafif gerilemeye izin verir, yavaş trendin daha belirgin bozulduğu kuruluşları eler. Filtre yalnız HMA sıralamasının ilk kuruluşunda değerlendirilir. Reddedilen kuruluş, aynı kesintisiz rejimin sonraki günlerinde gecikmeli girişe dönüşmez.
Kabul edilen kuruluş, sonraki uygun seans açılışı için piyasa emri oluşturur. Karar yalnız günlük kapanışta bilinen değerlerle verilir.
Çıkış mantığı
Stratejide tek bir açık kaynak çıkış katmanı vardır:
K1-A: aktivasyon eşiği. Azami olumlu hareket, giriş emri oluşturulurken bilinen ATR değerine bölünür. Varsayılan: 1,50 ATR.
K1-T: kampanya boyunca görülen en yüksek fiyattan itibaren trail mesafesi. Varsayılan: %5,75.
K1-W: K1 kapanış kararının uygulanabilmesi için gereken asgari bekleme süresi. Varsayılan: 4 seans.
K1 aktif olduktan sonra mutlak trail seviyesi yalnız yukarı hareket eder. Bir barda ulaşılan aktivasyon eşiği sonraki bardan itibaren uygulanabilir; aktivasyon barı geriye dönük biçimde kendi kendisini durduramaz. Günlük kapanış aktif K1 çizgisinde veya altında gerçekleşirse sonraki uygun açılış için piyasa çıkışı oluşturulur. Pozisyon açıkken yeni ve kabul edilmiş bir SET doğarsa kampanya sonraki açılışta yenilenir.
Araştırma süreci ve ayrılmış dönem sonuçları
K1 değerleri Ocak 2020–Aralık 2023 döneminde beş yabancı kontrat üzerinde; endeksler eşit ağırlıklı ve fiyat ölçekleri yüzdeyle normalize edilerek seçildi. K1 motoru sabit tutulduktan sonra üç günlük eğim eşiği aynı geliştirme döneminde -0,400 ile +0,050 ATR/gün arasında 0,001 adımla tarandı. PF öncelikli platonun matematiksel tepe noktası -0,176 oldu; aşırı hassas bir değer yayımlamamak için operasyonel eşik -0,180 olarak yuvarlanıp sabitlendi.
Ocak 2024–Temmuz 2026 dönemi eğim eşiğinin seçiminde kullanılmadı. Bu ayrılmış dönemde:
Ham kuruluş: 153
Kabul edilen kuruluş/işlem: 102 (%33,3 azalış)
Pozitif yabancı endeks: 5/5
Medyan profit factor: eğim filtresi olmadan 1,94, filtreyle 3,46
Medyan normalize net getiri: filtresiz %37,9, filtreyle %39,3
Medyan getiri/azami düşüş oranı: filtresiz 2,16, filtreyle 2,32
Bu rakamlar her piyasa dolumunda bir minimum fiyat adımı ters slippage içerir; komisyon, vergi, fonlama ve vade geçiş maliyeti içermez. Tarihsel araştırma sonucudur, gelecek tahmini değildir.
BIST stres testi zayıf kalmıştır: eğim filtresiyle üç Türkiye kontratının medyan profit factor değeri 0,77 olmuştur. Bu nedenle açık kaynak sürümü yabancı endeks vadelileri için bir araştırma stratejisi olarak değerlendirmek daha doğrudur; özel BIST30 canlı motorunun yerine geçmez.
Stratejiyi standart günlük mumlarda kullanın. Strategy Tester sonucunu yorumlamadan önce sembolün kontrat çarpanını, seansını, sürekli-vade oluşturma yöntemini, komisyonunu, vade geçiş maliyetini ve teminat ayarlarını kontrol edin. HMA, ATR, K1 veya emir yürütme ayarlarını değiştirmek doğrulanmamış farklı bir model oluşturur.
Bu kod araştırma ve eğitim amaçlıdır; yatırım tavsiyesi değildir. Geçmiş performans gelecekteki sonuçları garanti etmez. 策略

Volatility Regime Trend Ribbon [Pineify]Volatility Regime Trend Ribbon
Overview
This overlay adapts smoothing as markets change. It ranks ATR, selects a regime, and adjusts trend speed and ribbon width.
Key Features
Three ATR percentile regimes.
Regime-specific trend lengths and band scales.
Optional colors, confirmed markers, and alerts.
How It Works
ATR is ranked over a rolling window. Low ranks select low volatility, high ranks select high volatility, and middle ranks select normal volatility. Warm-up uses the normal state.
The selected length drives a recursive EMA-style center. Ribbon edges equal the center plus or minus ATR times the base multiplier and regime scale. This is a price boundary, not a statistical confidence interval. Direction turns bullish after a confirmed close above the upper edge, bearish below the lower edge, and otherwise retains its prior state.
Trading Ideas and Insights
Colors separate quiet, ordinary, and elevated ranges. A band exit can frame a direction change; movement inside stays unresolved. Gaps or thin trading can add lag and false transitions. No output is an automatic trade.
How Multiple Indicators Work Together
ATR measures range, percentile rank adds context, adaptive smoothing changes speed, and the band supplies the direction threshold. They form one engine without external data.
Unique Aspects
The original design links volatility to smoothing speed and band scale, not just color. Retained direction inside the band adds hysteresis; alerts distinguish regime and direction changes.
How to Use
Apply it to a liquid market and let the percentile window warm up.
Tune lengths and band scales for the symbol and timeframe.
Read center color as direction and ribbon color as regime.
Use confirmed alerts with independent risk controls.
Customization
ATR Length controls range sensitivity; Percentile Lookback controls context. Thresholds define states, lengths set speed, and band inputs set transition distance. Display layers are optional. Current values can change intrabar; markers and alerts require a confirmed close.
Conclusion
This ribbon organizes volatility regime and ATR percentile context for 15-minute to daily charts. It uses past and present data, remains lagging and parameter-sensitive, and makes no performance claim.
指標

Atlas Candle Volume Engine Atlas Candle Volume Engine
Read the candle. Measure the participation. Understand the move.
The Atlas Candle Volume Engine is a multi-timeframe candle and volume analysis tool designed to answer one fundamental question:
Is price moving with meaningful participation — or is it moving on weak volume?
Instead of treating every bullish or bearish candle equally, Atlas breaks the candle down into its individual components and compares them across Chart, 1H, 15M and 5M.
The result is a compact market diagnostic table that lets you see direction, candle strength, rejection, volume participation, volatility and volume efficiency at a glance.
How to read the table
🟢 Direction
Shows whether the candle is currently BULL or BEAR.
Don't use Direction by itself.
A bearish candle on extremely low volume is very different from a bearish candle accompanied by a major volume expansion.
Think:
Direction tells you what price did.
The other rows help explain why it may have happened.
📊 Body %
Measures how much of the candle's range is real body.
Example:
80% Body
Price travelled decisively in one direction.
20% Body
Most of the candle's movement was wick.
Reading it:
High Body % + high volume = stronger directional candle
Low Body % + high volume = potential conflict/rejection
📍 Close %
Shows where the candle finished within its high-low range.
Close near 90–100%
Buyers controlled most of the candle.
Close near 0–10%
Sellers controlled most of the candle.
Close around 50%
Neither side clearly controlled the final outcome.
Example
A bullish candle with:
Body 85% Close 95% Volume 2.2×
is much more convincing than:
Body 25% Close 52% Volume 2.2×
The volume is identical, but the result of that volume is completely different.
Wick % — rejection
Upper Wick
A large upper wick means price traded higher but failed to hold those levels.
Lower Wick
A large lower wick means price traded lower but recovered.
Example — potential selling rejection
Bear/Bull candle Upper Wick 45% Volume 2.5×
This tells you there was substantial activity at higher prices, but price couldn't maintain the high.
Example — potential buying rejection
Lower Wick 50% Volume 2.5×
Price was pushed lower but recovered strongly.
Wicks become much more meaningful when accompanied by elevated volume.
🔥 Volume Ratio
This is one of the most important numbers.
It compares current volume with its normal volume.
Example
0.50×
Volume is roughly half normal.
1.00×
Normal participation.
1.50×
50% above normal.
2.00×
Twice normal volume.
3.00×
Extreme participation.
The key rule:
High volume does NOT automatically mean bullish.
It means:
Something significant is happening.
We then look at the candle to determine what price actually did with that participation.
📈 Volume Percentile
This answers a slightly different question:
How unusual is this volume compared with previous candles?
For example:
95% percentile
means current volume is unusually high compared with its historical distribution.
10% percentile
means volume is relatively quiet.
Example
Price suddenly falls with:
Volume Ratio: 2.4× Volume Percentile: 97%
That's a major participation event.
Now look at:
Body + Close + Wicks + Efficiency
to determine what that participation accomplished.
🚀 Volume Acceleration
This tells you whether participation is increasing or decreasing.
Example
0.8×
1.0×
1.3×
1.7×
2.1×
Volume is accelerating.
If price is simultaneously moving upward with strong candles, that can indicate expanding participation behind the move.
Conversely:
2.4×
2.0×
1.6×
1.2×
0.8×
Volume is fading.
If price continues moving but participation keeps disappearing, the move may be losing strength.
⚡ Range / ATR
This tells you how large the candle is compared with normal volatility.
Example
0.40
Small movement.
1.00
Normal movement.
2.00
The candle is approximately twice the normal ATR range.
A large range combined with high volume is much more significant than a tiny candle occurring on the same volume.
💥 Body / ATR
This focuses specifically on directional displacement.
A candle could have a large range because of huge wicks.
Body/ATR helps determine whether price actually travelled directionally.
Example A
Range/ATR = 2.0 Body/ATR = 0.3
Huge candle, but most of it was wick.
Example B
Range/ATR = 1.5 Body/ATR = 1.2
Most of the movement was genuine directional displacement.
That distinction is extremely important.
⚙️ Efficiency
Efficiency brings several of these ideas together.
It asks:
How effectively is the current volume producing price movement?
HIGH efficiency
Volume is producing substantial directional displacement.
MED efficiency
Some movement is occurring, but the signal is less decisive.
LOW efficiency
A lot of activity is producing relatively little directional movement.
Real-world examples
Example 1 — Strong bullish expansion
Direction BULL
Body % 85%
Close % 94%
Upper Wick 5%
Lower Wick 11%
Vol Ratio 2.3×
Vol Percentile 96%
Vol Accel UP
Range/ATR 1.7
Body/ATR 1.4
Efficiency HIGH
Reading:
Bullish direction + strong body + close near high + high volume + increasing participation + strong displacement.
This is a high-quality bullish expansion profile.
Example 2 — Weak bearish move
Direction BEAR
Body % 72%
Close % 67%
Vol Ratio 0.35×
Vol Percentile 8%
Vol Accel DOWN
Range/ATR 0.55
Body/ATR 0.40
Efficiency MED
Price is falling.
But participation is weak.
Reading:
Bearish price action, but little evidence of expanding participation behind the move.
This doesn't automatically mean bullish — it means the bearish move isn't strongly confirmed by volume.
Example 3 — High-volume rejection
Direction BULL
Body % 25%
Close % 58%
Upper Wick 62%
Vol Ratio 2.8×
Vol Percentile 98%
Vol Accel UP
Range/ATR 1.9
Body/ATR 0.35
Efficiency LOW
This is very interesting.
Huge volume.
Huge range.
But very little body.
And a massive upper wick.
Reading:
A lot of activity occurred, but price failed to maintain the move higher.
That is a very different market condition from a clean bullish expansion.
Example 4 — Quiet accumulation/absorption type behaviour
Direction BULL
Body % 30%
Close % 72%
Lower Wick 48%
Vol Ratio 2.2×
Vol Percentile 94%
Vol Accel UP
Range/ATR 1.4
Body/ATR 0.30
Efficiency MED
Price was pushed down, but recovered.
Volume is elevated.
The lower wick is large.
Reading:
Significant activity occurred at lower prices, but sellers failed to maintain control.
This is the sort of pattern where the relationship between volume + wick + close becomes much more informative than candle colour alone.
The golden rule of the table
Never read one row in isolation.
Instead, read it in layers:
1️⃣ Direction
Which way did price move?
↓
2️⃣ Body + Close
How decisively did it move?
↓
3️⃣ Wicks
Was there rejection?
↓
4️⃣ Volume Ratio + Percentile
Was there meaningful participation?
↓
5️⃣ Volume Acceleration
Is participation increasing or fading?
↓
6️⃣ Range/ATR + Body/ATR
How significant was the actual displacement?
↓
7️⃣ Efficiency
Did the volume actually accomplish much?
Multi-timeframe example
This is where the table becomes particularly powerful.
Imagine:
1H 15M 5M
Direction BULL BULL BEAR
Body % 82% 74% 65%
Vol Ratio 1.8× 2.1× 0.5×
Vol Accel UP UP DOWN
Efficiency HIGH HIGH MED
The 1H and 15M are showing strong bullish participation, while the 5M is currently pulling back on weak volume.
That tells a very different story from:
1H 15M 5M
Direction BEAR BEAR BEAR
Vol Ratio 2.1× 2.4× 2.7×
Vol Accel UP UP UP
Efficiency HIGH HIGH HIGH
Here, all three time frames are showing expanding bearish participation.
That's the real purpose of the table:
Don't just look at the colour of the candle. Look at what the market had to do to produce it.
Atlas Candle Volume Engine
Price tells you what happened. Volume tells you how much participation was involved. Candle structure tells you how that participation affected price. Efficiency tells you how much the market actually accomplished.
That combination is what makes the table useful as a standalone market-reading tool. 指標

Support & Resistance Zones [HexaTrades]
This indicator automatically finds the price levels where the market has turned around before the places where buyers stepped in (support) and where sellers took over (resistance) and draws them as clean rectangular zones on your chart.
Instead of a thin line, each level is drawn as a zone with real thickness, because support and resistance are never one exact price; they are areas where price reacts. The zones update live, extend forward as long as they are valid, and turn into light "ghost" boxes once price finally breaks through them, so you always keep the full picture of the market's history.
Bitcoin 4h: the indicator marking support and resistance zones
How it works
- Finds swing points. A swing high is a candle whose high is higher than the 10 candles on each side of it (the "Swing Length" setting). A swing low is the same idea upside down. These are the exact spots where the market turned.
- Builds a zone from the candle. The zone covers the candle's wick from the extreme tip to the candle body. That wick is where orders actually pushed price back, so it becomes the zone.
- Keeps zone size sensible. Very small wicks get padded to a minimum height, and no zone can grow taller than a maximum height (both measured in ATR, so they adapt automatically to each market's volatility).
- Merges duplicate levels. If a new swing forms at a level that already has a zone, the two are combined into one box instead of stacking clutter on your chart.
- Watches for breaks. When a candle closes beyond a zone, the zone is "broken." what happens next is up to you (see below).
What happens after a zone breaks?
The indicator provides three different zone-management options.
Keep As Past Zone: The broken zone stops extending and remains visible as a faded historical zone. This makes it easier to review how price behaved around previous levels.
Flip Support/Resistance: A broken resistance zone becomes support, while a broken support zone becomes resistance.
This is useful for studying the common market concept of role reversal, where old resistance may act as new support and old support may act as new resistance.
Delete Zone: The zone is completely removed after it breaks. This option is useful for traders who prefer a cleaner chart showing only active zones.
Optional volume filter:
Volume-Confirmed Zones Only can be enabled to filter out lower-volume swing points.
When enabled, the volume of the swing candle must be higher than: Average Volume × Volume Multiplier
For example, with a Volume Multiplier of 1.2, the swing candle’s volume must be greater than 120% of its average volume.
The volume filter is automatically ignored when volume data is unavailable. Volume quality can vary between markets, exchanges and brokers.
Indicator settings
- Swing Length: Controls how significant a swing must be. Lower values create more zones, while higher values create fewer but potentially more significant zones.
- Maximum Zones: Limits the number of active zones displayed. When the limit is exceeded, the oldest active zone is removed.
- ATR Length: Sets the calculation period used to measure volatility.
- Minimum Zone Height: Sets the minimum zone thickness as a multiple of ATR.
- Maximum Zone Height: Prevents zones from becoming excessively wide.
- Merge Overlapping Zones: Combines overlapping or nearby active zones.
- Merge Distance: Controls the ATR-based distance used when deciding whether zones should be merged.
- Maximum Past Zones: Limits how many broken historical zones remain on the chart.
- Past Zone Transparency: Controls how clearly broken zones are displayed.
Alerts
- Built-in alerts
- Zone Touched — price entered a support or resistance zone.
- Resistance Broken — a candle broke above a resistance zone.
- Support Broken — a candle broke a support zone below.
- Set them up from TradingView's alert dialog: Create Alert → Condition → S/R Zones.
How to use it in trading
🔶Bounce trades: when price falls into a support zone and prints a rejection candle, that's a long setup with a stop just below the zone.
A blue support zone represents an area where buyers previously entered the market.
When price returns to support:
- Wait for price to enter or test the zone.
- Look for evidence that buyers are responding.
- Consider an entry only after confirmation.
- Place the stop beyond the opposite side of the zone, with an appropriate buffer.
- Use the next resistance zone as a possible target.
Possible bullish confirmation includes:
- A candle rejecting the lower part of the zone.
- A long lower wick followed by a bullish close.
- A bullish engulfing candle.
- Price closing back above the support zone.
- Increasing volume during the reaction.
- A higher low forming near the zone.
A support touch by itself is not a long signal. Price can move directly through the zone, especially during a strong downtrend.
Example image below:
🔶Rejection from resistance
A pink resistance zone represents an area where sellers previously entered the market.
When price reaches resistance:
- Wait for price to test the zone.
- Look for signs of selling pressure.
- Consider an entry only after bearish confirmation.
- Place the stop beyond the upper edge of the zone, with a suitable buffer.
- Use the next support zone below as a possible target.
Possible bearish confirmation includes:
- A long upper wick inside the resistance zone.
- A bearish engulfing candle.
- Price entering the zone and closing back below it.
- A lower high forming near resistance.
- Increasing selling volume during the rejection.
A resistance touch alone is not a short signal. Strong bullish momentum can break through resistance without producing a meaningful reversal.
Example image:
🔶Trading a breakout
A breakout occurs when price moves beyond an active zone.
- A break above resistance may indicate increasing bullish strength.
- A break below support may indicate increasing bearish strength.
For more conservative confirmation, select Close under Break Confirmation. In this mode, a resistance zone breaks only after a candle closes above it, while a support zone breaks only after a candle closes below it.
The Wick option reacts as soon as price trades beyond the zone. It responds faster but is more sensitive to temporary spikes and false breakouts.
Before considering a breakout trade, traders may look for:
- A strong candle closing beyond the zone.
- A candle body that closes clearly outside the zone.
- Higher-than-average volume.
- Momentum in the breakout direction.
- Alignment with the broader market trend.
- A successful retest of the broken zone.
🔶Trading a role reversal
Support and resistance can sometimes exchange roles after a breakout.
-Broken resistance may later act as support.
- Broken support may later act as resistance.
Select Flip Support/Resistance under the When Broken setting to display this behaviour automatically.
For example, after price closes above a pink resistance zone, the indicator converts that area into a blue support zone. If price later returns to it, traders can watch for a bullish reaction.
Similarly, when price breaks below blue support, the indicator converts the zone into pink resistance. A later retest may provide an area to watch for bearish confirmation.
Role reversal is a commonly observed price-action concept, but it does not occur successfully after every breakout. Wait for confirmation instead of entering only because price has returned to a flipped zone.
🔶Using zones for targets and stops
Zones can also help organise trade management.
For a long setup:
- A stop may be placed below the support zone.
- The next resistance zone may be used as an initial target.
- A higher resistance zone may be considered as a secondary target if momentum remains strong.
For a short setup:
- A stop may be placed above the resistance zone.
- The next support zone may be used as an initial target.
- A lower support zone may be considered as a secondary target.
Avoid placing the stop exactly on the edge of a zone. Price may briefly move beyond the boundary before reacting. The appropriate buffer depends on the symbol, timeframe, volatility and the trader’s risk plan.
Always calculate the potential risk and reward before entering a trade. A visible zone does not automatically make a setup worth taking.
🔶 Using multiple timeframes
Higher-timeframe zones can provide broader market context, while lower timeframes can help refine entries.
A simple process is:
- Identify important support and resistance on a higher timeframe.
- Determine whether the broader structure is bullish, bearish or ranging.
- Move to the preferred trading timeframe.
- Wait for price to reach a relevant zone.
- Use candle structure, volume or momentum for confirmation.
Higher timeframes generally produce fewer but more widely watched zones. Lower timeframes produce more zones and may contain more market noise.
Support and Resistance Zones help traders identify and manage important price areas with less chart clutter. Its volatility-based sizing, zone merging, break confirmation, role reversal, and alerts make it suitable for different markets and timeframes. Use the zones as areas to watch—not automatic trade signals and always combine them with price confirmation, broader market structure and proper risk management.
We would love to hear your suggestions. If you have ideas for new features, indicators, analytics, or improvements, please share your feedback. Your input helps guide future updates and improve the indicator for all traders.
Wedge pattern detector indicator is for educational and analytical purposes only. It is not financial advice. Trading involves risk. Always use proper risk management and combine this indicator with your own analysis before taking any trade.
指標

BB Squeeze Histogram
BB Squeeze Histogram (BBSH) — User Manual
Companion indicator to Bollinger-Bands.Multi_Choice (BBMC). Plots the width of the Bollinger envelope as a MACD-style histogram, signed by which side of the basis MA price is on.
1. What It Shows
Two things are encoded into one histogram:
Above / below the neutral line — whether price is currently above or below the basis moving average. The neutral line is 0 in raw mode, 50 in normalized mode.
Bar length from the neutral line — how wide the Bollinger envelope currently is (the distance between the upper and lower band, at your chosen standard-deviation multiple). Long bars = wide bands = high volatility. Short bars hugging the neutral line = tight bands = low volatility / squeeze.
Put together, a bar answers two questions at once: which side of trend is price on, and how stretched or compressed is the market right now.
2. Reading the Colors
Bars use a 4-color scheme, same idea as a standard MACD histogram:
Color
Meaning
Bright teal
Above neutral, band width expanding vs. the prior bar
Pale teal
Above neutral, band width contracting vs. the prior bar
Bright red
Below neutral, band width expanding vs. the prior bar
Pale red/pink
Below neutral, band width contracting vs. the prior bar
Bright bars mean volatility is actively growing on that side of the trend. Pale bars mean the move is losing steam or the range is tightening — often the first sign a squeeze is building.
3. Extra Plots on the Panel
Neutral line — gray line at 0 (raw mode) or 50 (normalized mode). Crossings mark price crossing the basis MA.
Red line (Avg Positive Column) — the running average width of only the positive (above-neutral) bars, over the "Column average lookback" period. Shows what a "normal" bullish-side expansion looks like recently. Bars poking well above this line are expanding harder than usual.
Green line (Avg Negative Column) — same idea, mirrored for the negative (below-neutral) bars.
Yellow dots on the neutral line — squeeze markers. Appear when the current band width is the tightest reading over the "Squeeze lookback" period — i.e., the bands are as compressed as they've been in a while. These tend to precede expansion moves.
4. Inputs
Input
Default
What it does
Source
ohlc4
Price series used for the basis MA and standard deviation calc
Length
20
Lookback for both the basis MA and the standard deviation
Band SD (± this value)
3.0
The standard-deviation multiple defining the band edges (matches your BBMC R3/S3 by default)
ALMA offset
0.89
Only used if MA Type = ALMA
ALMA sigma
5
Only used if MA Type = ALMA
Normalize to 0-100 scale
off
See Section 5
Normalize rank lookback
200
Bars of width history the 0-100 rank is measured against (normalized mode only)
Squeeze lookback
100
Bars used to detect the "tightest width" for the yellow squeeze dots
Column average lookback
100
Bars used to compute the red/green average-column lines
MA Type
VWMA
Basis moving average type — SMA, EMA, RMA, WMA, VWMA, VWAP, HMA, SWMA, or ALMA
5. Normalize Toggle — Important
Off (default): the histogram plots raw dollar-width — literally (upper band − lower band). Values are in the same units as price, so a reading of "8,000" on BTC/USD means the envelope is $8,000 wide. The neutral line sits at 0.
On: the histogram is rescaled to a bounded 0–100 oscillator with 50 as the neutral level. The current band width is percentile-ranked against its own history over the "Normalize rank lookback" period (default 200 bars), producing a 0–100 rank. That rank is halved to a 0–50 magnitude and then measured out from 50 — upward when price is above the basis MA, downward when below.
Reading the normalized scale:
Reading
Meaning
Near 100
Price above the basis MA, band width at the widest end of its recent history
~75
Price above basis, width around the middle of its historical range
Near 50
Squeeze — width at the tightest end of its history, regardless of side
~25
Price below basis, width around the middle of its historical range
Near 0
Price below the basis MA, band width at the widest end of its recent history
Note that the distance from 50 is the volatility read and the side of 50 is the trend read — they are independent. A reading of 52 and a reading of 48 both describe a tightly squeezed market; they just differ on which side of the MA price closed.
Because the value is a percentile rank, it is self-scaling: readings are directly comparable across assets, timeframes, and price regimes without retuning. The trade-off is that it tells you where width sits relative to its own recent history, not its absolute size — a 95 reading in a quiet chop regime may be a smaller dollar-width than a 60 reading during a volatile stretch. Shortening the rank lookback makes the oscillator more reactive to recent regime; lengthening it gives a more stable long-run reference.
Match your basis MA type/length here to your BBMC settings if you want the neutral-line crossings on this panel to line up exactly with the white basis line's color flips on your main BBMC chart.
6. Suggested Ways to Use It
Trend confirmation: treat neutral-line position the same way you'd treat price vs. the BBMC basis line — histogram above neutral supports a long bias, below neutral supports a short bias.
Squeeze setups: watch for yellow dots (tight width) followed by a color shift from pale to bright — that transition often marks the start of a breakout move out of consolidation.
Exhaustion reads: when bars run well past the red or green average line, the current expansion is unusually large relative to its own recent history — often a point where trend continuation odds start to fade and mean-reversion becomes more likely.
Divergence: if price makes a new high/low but the histogram's peak height is smaller than the prior swing's, the expansion behind the move is weaker than last time — a classic momentum-divergence tell, same logic as reading MACD histogram divergence against price.
7. Notes / Limitations
This is a volatility/width indicator, not a standalone directional signal — it's meant to be read alongside price structure or your BBMC chart, not in isolation.
The squeeze marker and average-column lines both depend on their lookback inputs; shortening them makes the indicator more reactive to recent bars, lengthening them smooths it out but reacts slower to regime changes.
Normalize should generally stay consistent once you've picked it — the raw and normalized histograms are not on comparable scales, and the red/green average lines are computed from whichever mode is active. The squeeze dots are always derived from raw band width, so they mark the same bars in either mode. 指標

Kyokutan-Ashi◈ Description
The Kyokutan-Ashi is a unique indicator designed to visualize the exact price deviation (noise) that standard Heikin-Ashi (HA) calculations normally smooth out and hide. By completely stripping away the trend component, it isolates pure market volatility and overextension.
◈ The Math Behind It (Why this calculation & Expected Output)
The core logic subtracts the Heikin-Ashi values from standard Japanese candlestick values. The purpose of this calculation is to extract the pure "difference" (noise) between the actual price and the smoothed trend, and then reconstruct it based on a chosen anchor point.
【 Calculation Example 】
Current actual candle: open = 100, high = 105, low = 95, close = 102
Previous HA candle: haOpen = 98, haClose = 100
Settings: Anchor Point = "Open", Multiplier = 1.0
haClose = (100 + 105 + 95 + 102) / 4.0 = 100.5
haOpen = (98 + 100) / 2.0 = 99
Subtract HA from standard values to isolate the noise.
rawOpen = 100 - 99 = 1
rawClose = 102 - 100.5 = 1.5
Add the isolated noise to the baseline (Anchor = Open: 100).
antiOpen = 100 + 1 = 101
antiClose = 100 + 1.5 = 101.5
【 Actual Output 】
A small bullish candle from 101 to 101.5 is plotted on the chart. Although the actual price moved from 100 to 102, removing the trend component reveals that the "pure overextension" (deviation) is only 0.5.
◈ Key Features
Pure Deviation Visualization: Shows only how far the actual price is stretching away from the Heikin-Ashi smoothed price.
Anchor & Base Settings: Choose where to project the deviation (Open, Close, or HL2).
Deviation Multiplier: Scale the noise up or down to easily spot extreme market extensions.
Chart-Type Independent: Built with robust data handling. Even if you change your main chart view to Heikin-Ashi, Renko, or Kagi, Kyokutan-Ashi always forcefully retrieves standard raw price data in the background to guarantee accurate deviation calculations.
◈ Why Use It
Use it in combination with other charts or indicators to extract your own unique noise and trading edges. When Kyokutan-Ashi prints unusually large candles, it signals that the actual price is violently snapping away from the smoothed trend — often indicating exhaustion, potential mean-reversion, or hidden volatility.
◈ Author's Note
While Kyokutan-Ashi was developed independently to address the loss of actual price data in Heikin-Ashi, I later discovered "BERLIN Candles" by lejmer. He had already recognized this critical issue and beautifully engineered a hybrid solution long before I did. I want to express my deepest respect for his foresight and pioneering work in tackling this specific problem.
指標

TRADION Gaussian Trend EngineTRADION Gaussian Trend Engine
OVERVIEW
TRADION Gaussian Trend Engine is a multi-factor trend analysis framework designed to evaluate market direction, trend strength, momentum alignment and volatility within a unified model.
The indicator is built around an independently implemented multi-pole Gaussian cascade. Instead of using Gaussian direction alone as a trading signal, the engine evaluates several additional dimensions of market behavior before qualifying a directional transition.
The framework combines:
• Configurable multi-pole Gaussian smoothing
• ATR-normalized Gaussian slope
• Price displacement from the Gaussian baseline
• RSI momentum analysis
• Rate of Change (ROC)
• A composite 0–100 Trend Strength Score
• Volatility-adaptive trend ribbons
• Three-level BUY / SELL classification
• Confirmed-bar signal generation
• Dedicated TradingView alerts
The design objective is selective trend qualification rather than generating a signal on every minor directional fluctuation.
────────────────────────────
GAUSSIAN TREND ENGINE
────────────────────────────
The core of the indicator is a configurable multi-pole Gaussian cascade.
The user can control two primary parameters:
Gaussian Period:
Controls the smoothing horizon of the filter.
Gaussian Poles:
Controls the number of sequential Gaussian smoothing stages used by the engine, from 1 to 6.
Each additional pole applies another stage of Gaussian smoothing to the previous output.
This architecture provides a configurable balance between responsiveness and noise reduction.
The final output of the selected pole becomes the Gaussian trend baseline used by the rest of the engine.
────────────────────────────
TREND DIRECTION
────────────────────────────
Directional state is determined from the slope of the Gaussian baseline.
When the current Gaussian value is above its previous value, the engine identifies a bullish directional state.
When the current Gaussian value is below its previous value, the engine identifies a bearish directional state.
The Gaussian line changes dynamically:
Green = Bullish Gaussian direction
Red = Bearish Gaussian direction
An unchanged Gaussian value preserves the previous directional state.
────────────────────────────
VOLATILITY NORMALIZATION
────────────────────────────
Raw price movement has different significance across instruments and volatility regimes.
For this reason, ATR is used as a normalization reference within the engine.
Two important measurements are normalized relative to ATR:
• Gaussian slope magnitude
• Distance between price and the Gaussian baseline
This allows the strength model to evaluate movement relative to current market volatility rather than relying only on absolute price changes.
────────────────────────────
TREND STRENGTH SCORE
────────────────────────────
TRADION Gaussian Trend Engine calculates a composite Trend Strength Score ranging from 0 to 100.
The score combines four normalized components:
1. Gaussian Slope Strength — 40%
2. Price Distance from Gaussian — 20%
3. RSI Momentum Intensity — 25%
4. ROC Magnitude — 15%
Gaussian Slope Strength measures the magnitude of directional movement in the Gaussian baseline relative to ATR.
Price Distance measures the absolute displacement of price from the Gaussian baseline relative to ATR.
RSI Momentum Intensity measures the distance of RSI from its neutral 50 level.
ROC Magnitude measures the absolute velocity of price movement.
Each component is normalized before being incorporated into the final weighted score.
The result is a single 0–100 metric designed to describe the degree of agreement between trend movement, price expansion and momentum.
────────────────────────────
MOMENTUM CONFIRMATION
────────────────────────────
Momentum confirmation can be enabled or disabled by the user.
For bullish confirmation, the default model requires:
• RSI above 50 plus the selected Neutral Zone
• Positive ROC
For bearish confirmation, it requires:
• RSI below 50 minus the selected Neutral Zone
• Negative ROC
This layer prevents every Gaussian slope change from automatically qualifying as a BUY or SELL event.
The RSI Neutral Zone is configurable, allowing the user to control how much momentum separation is required around the RSI 50 equilibrium level.
────────────────────────────
DIRECTIONAL QUALIFICATION
────────────────────────────
A qualified bullish setup requires:
• Rising Gaussian direction
• Price above the Gaussian baseline
• Valid bullish momentum when momentum confirmation is enabled
• Trend Strength above the configured minimum threshold
A qualified bearish setup requires:
• Falling Gaussian direction
• Price below the Gaussian baseline
• Valid bearish momentum when momentum confirmation is enabled
• Trend Strength above the configured minimum threshold
This means that Gaussian direction, price structure, momentum and trend strength are evaluated together before a directional event is accepted.
────────────────────────────
THREE-LEVEL SIGNAL CLASSIFICATION
────────────────────────────
Qualified transitions are classified according to their Trend Strength Score.
Bullish classifications:
BUY
STRONG BUY
EXTREME BUY
Bearish classifications:
SELL
STRONG SELL
EXTREME SELL
The default thresholds are:
Minimum Signal Strength: 25
Strong Signal Threshold: 55
Extreme Signal Threshold: 75
These thresholds are fully configurable.
A standard signal represents a qualified directional transition below the Strong threshold.
A STRONG signal represents a transition whose Trend Strength reaches the Strong threshold.
An EXTREME signal represents a transition whose Trend Strength reaches the highest configured classification threshold.
These labels describe the strength of the conditions detected by the model. They are not predictions of future returns.
────────────────────────────
CONFIRMED-BAR SIGNAL ENGINE
────────────────────────────
Signal generation uses confirmed-bar logic.
A new directional signal is accepted only when the current chart bar is confirmed.
This prevents temporary intrabar conditions from being treated as completed signals before the candle closes.
The engine also maintains directional signal state.
Once a bullish signal has been generated, another bullish signal is not repeatedly produced while the signal state remains bullish.
A new bullish event becomes possible after the engine has transitioned through the opposite qualified state, and vice versa.
This creates cleaner transition-based signal behavior.
────────────────────────────
VOLATILITY-ADAPTIVE TREND RIBBON
────────────────────────────
The trend ribbon provides a visual representation of directional state and adaptive market conditions.
Its base width is calculated using ATR.
The final ribbon width also incorporates the current Trend Strength Score.
As calculated trend strength increases, the ribbon can expand according to the user-defined Trend Strength Width Effect.
During bullish states, the ribbon is positioned below the Gaussian baseline.
During bearish states, the ribbon is positioned above the Gaussian baseline.
The ribbon consists of multiple visual layers, creating a clear distinction between the Gaussian baseline and the outer volatility-adjusted trend zone.
This makes direction and changes in trend intensity easier to interpret directly from the chart.
────────────────────────────
VISUAL INTERPRETATION
────────────────────────────
GREEN GAUSSIAN / GREEN RIBBON
The Gaussian baseline is rising and the engine is operating in a bullish directional regime.
RED GAUSSIAN / RED RIBBON
The Gaussian baseline is falling and the engine is operating in a bearish directional regime.
BUY / SELL
A new directional setup has passed the minimum qualification requirements.
STRONG BUY / STRONG SELL
A qualified transition has reached the configured Strong Trend Strength threshold.
EXTREME BUY / EXTREME SELL
A qualified transition has reached the configured Extreme Trend Strength threshold.
────────────────────────────
USER CONTROLS
────────────────────────────
Gaussian Engine:
• Source
• Gaussian Period
• Gaussian Poles
Momentum Confirmation:
• Enable / Disable Momentum Confirmation
• RSI Period
• ROC Period
• RSI Neutral Zone
Trend Strength:
• ATR Period
• Gaussian Slope Sensitivity
• Price Distance Sensitivity
• Minimum Signal Strength
• Strong Signal Threshold
• Extreme Signal Threshold
Adaptive Trend Ribbon:
• Show / Hide Adaptive Trend Ribbon
• Ribbon ATR Width
• Trend Strength Width Effect
Visual Settings:
• Show Trading Signals
• Color Price Bars
• Show Gaussian Trend Line
────────────────────────────
ALERTS
────────────────────────────
Six dedicated TradingView alert conditions are included:
• TRADION BUY
• TRADION STRONG BUY
• TRADION EXTREME BUY
• TRADION SELL
• TRADION STRONG SELL
• TRADION EXTREME SELL
This allows each signal classification to be monitored independently.
────────────────────────────
PRACTICAL USE
────────────────────────────
TRADION Gaussian Trend Engine can be used as:
• A directional trend filter
• A trend-strength visualization tool
• A momentum-confirmed transition detector
• A volatility-adaptive trend framework
• A confirmation layer for discretionary analysis
• An alert-based trend monitoring system
Because sensitivity depends on the selected parameters, instrument and timeframe, users should evaluate settings according to their own methodology.
Higher sensitivity may detect directional changes earlier but can increase exposure to market noise.
Greater smoothing and higher qualification thresholds can reduce signal frequency but may identify transitions later.
────────────────────────────
DESIGN PHILOSOPHY
────────────────────────────
The central idea behind TRADION Gaussian Trend Engine is that trend direction alone provides incomplete information.
A rising filter does not necessarily represent a strong trend.
For this reason, the engine evaluates four questions:
1. What direction is the Gaussian structure moving?
2. How significant is that movement relative to volatility?
3. Is price positioned consistently with that direction?
4. Does momentum support the directional structure?
The Trend Strength model then measures the degree of alignment between these components.
This creates a unified framework for analyzing direction, momentum, volatility and trend intensity rather than treating each component as an isolated indicator.
────────────────────────────
IMPORTANT NOTES
────────────────────────────
TRADION Gaussian Trend Engine is an analytical indicator, not a strategy and not a prediction system.
BUY, STRONG BUY, EXTREME BUY, SELL, STRONG SELL and EXTREME SELL labels represent mathematical classifications produced by the indicator's current conditions.
They do not guarantee future price direction, profitability or trade outcomes.
Signals are confirmed at bar close, but confirmed-bar processing does not eliminate normal market risk or signal lag.
Users should independently evaluate the indicator and apply appropriate risk management.
For research and educational purposes. 指標

Adaptive Volume Profile Matrix ProAdaptive Volume Profile Matrix Pro
Adaptive Volume Profile Matrix Pro is a full volume profile / market profile engine built from scratch (row-by-row volume distribution, POC, and value area, all computed manually) with several original layers added on top: multi-session profile history, a volatility-adaptive value area, a rotational balance score, a POC momentum trail across sessions, an acceptance heatmap, single-print/liquidity-magnet highlighting, and cross-session POC confluence zones. It's designed for traders who use volume profile as a structural framework and want session-to-session context rather than a single static profile.
How it works
Session Profile Construction — each new period (Session, Week, or Month) resets a fresh profile. Every bar's volume is distributed across price rows in proportion to how much of the bar's range overlaps each row, split into buy/sell volume based on whether the bar closed up or down, and each row's touch count is tracked.
POC & Value Area — the row with the most volume is the Point of Control (POC). The value area expands outward from the POC, row by row toward whichever side has more volume, until it contains the target percentage of total session volume.
Adaptive Value Area % — instead of a fixed value area percentage (traditionally 70%), the target percentage is scaled by a volatility regime measure (ATR relative to the session's range), widening or narrowing the value area based on how volatile the current session is versus its own range.
Rotational Factor — measures how much price revisited the same rows versus visiting new ones. A high score suggests balanced, range-bound rotation; a low score suggests trending, directional movement — shown as a percentage and labeled "Balanced," "Trending," or "Mixed."
Multi-Session Profile History — completed sessions are archived (high/low, POC, VAH/VAL, and full row-level volume) so a configurable number of previous profiles can be drawn alongside the current one, either as full row profiles or as POC/VAH/VAL lines only.
Profile Momentum Trail — connects each session's POC to the next with a dotted line, so you can visually track how the "fair value" price has drifted session over session.
Acceptance Heatmap — colors each row by combining its volume share, touch count, and a sensitivity input into an acceptance score, so rows with sustained, repeated participation stand out from rows that were merely passed through.
Single Prints / Liquidity Magnets — rows with only one touch and low relative volume are flagged separately, marking areas price moved through quickly with little acceptance — often referenced as potential liquidity magnets or areas price may revisit.
Cross-Profile POC Confluence Zones — all historical POCs (plus the current session's) are sorted and clustered; when two or more POCs fall within a configurable tolerance of each other, that price band is highlighted as a high-confluence support/resistance zone, on the idea that a price level acting as fair value across multiple sessions carries added significance.
Reading the indicator
Horizontal profile boxes on the right of the current session show the volume distribution by price row; box color reflects buy/sell delta and, if the heatmap is enabled, acceptance intensity.
Solid yellow line — current session POC. Dashed aqua lines — current VAH/VAL.
Faded profile boxes and dotted POC/VAH/VAL lines to the left — previous sessions' profiles, shown at reduced opacity.
Fuchsia dotted line — the POC momentum trail connecting POCs across sessions.
Orange shaded bands — confluence zones where multiple sessions' POCs cluster near the same price.
Orange-highlighted rows (if enabled) — single-print/low-acceptance rows within the current session.
Info label (top of current session) — shows current POC, VAH, VAL, the adaptive value area %, the rotational factor and its balanced/trending/mixed read, and how many previous profiles are displayed.
Suggested use
This is a structural context tool, best used to:
Identify current fair value (POC) and the range the market has accepted (value area) for the active session, week, or month
Track how fair value is drifting over time via the momentum trail, rather than only looking at one profile in isolation
Spot high-confluence price zones where multiple sessions' POCs have clustered, as candidate support/resistance levels
Gauge whether current conditions look rotational/balanced or trending via the rotational factor, to help decide between range and breakout approaches
Use single-print zones as areas of low acceptance that price moved through quickly and may revisit
As with any profile tool, it works best as structural context alongside your own trade triggers and risk management — it identifies where volume has concentrated and how that's evolving, not when to enter or exit.
Inputs
Profile Settings — anchor period (Session/Week/Month), number of price rows, base value area %, adaptive value area toggle
Novel: Rotational Factor — toggle for showing it in the info label
Novel: Profile Momentum — toggle for the POC momentum trail
Novel: Acceptance Heatmap — toggle and sensitivity for heatmap coloring
Previous Profiles — toggle, number of profiles shown, extra transparency, max width in bars, POC/VA-lines-only mode
Novel: Confluence Zones — toggle and tolerance (as % of session range) for clustering POCs
Visuals — POC/VAH/VAL colors, bullish/bearish volume colors, single-print highlighting, current profile max width in bars
Alerts
Two alert conditions are built in:
High Rotational Balance — rotational factor above 70, suggesting range-bound conditions
Low Rotational Balance (Trend) — rotational factor below 20, suggesting trending conditions 指標

Absorption Detector Pro Absorption Detector Pro
Absorption Detector Pro finds high-quality "absorption" bars — spots where aggressive volume hits the market but price fails to move proportionally, and instead reverses and closes strongly against the initial push. This is the classic effort-vs-result signature used in order-flow and volume-spread-analysis (VSA) trading: big effort (volume), little result (range), and a rejection close. The script layers PVSRA candle context, liquidity-sweep detection, trend filtering, a self-adjusting percentile ranking, and an optional intrabar buy/sell delta check on top of that core idea to cut down on noise and surface only the strongest candidates.
How it works
Absorption Score — for every bar, volume relative to its average (volume ratio) is divided by range relative to its average (range ratio). A high score means unusually large volume produced an unusually small candle — a sign of absorption.
Percentile Ranking — rather than using a single fixed cutoff, the score is ranked against the last N bars (percentile rank window, default 100) and only scores in the top X% (default 90th percentile) qualify. This lets the indicator self-adjust across symbols and timeframes instead of relying on one static threshold.
PVSRA Candle Context — each candle is classified as climax volume, above-average volume, or normal, based on volume and volume×range vs. their recent averages. Candles are optionally painted with these PVSRA colors for quick visual context, and climax volume can be required for a signal.
Liquidity Sweep — the script can require that the signal bar poked beyond the recent swing high/low before reversing (a stop-hunt/sweep pattern), which is a common precursor to genuine absorption.
Trend Filter — signals can be required to occur against the prevailing trend (price vs. a moving average), since absorption is most meaningful as a reversal/exhaustion signal rather than mid-trend noise.
Order Flow Delta (optional) — using request.security_lower_tf, the script can pull intrabar buy/sell volume from a lower timeframe (default 1-minute) and require that the net delta actually confirms the proposed direction (e.g., net selling on a bullish absorption bar that still closes strong).
Cooldown — a minimum bar count between signals prevents clustered, repetitive triggers during choppy conditions.
A bullish or bearish absorption signal only fires when all enabled gates pass together: elevated volume, a score above both the floor and the percentile threshold, correct close position in the bar's range, (optionally) climax volume, a liquidity sweep, trend alignment, and delta confirmation.
Reading the indicator
Triangle markers below/above bars mark bullish/bearish absorption signals.
Labels (optional) show the absorption score multiple and its percentile rank at the moment of signal.
Background highlight (optional) shades the signal bar.
Candle colors (optional, PVSRA) show climax volume, above-average volume, and normal volume at a glance, independent of signals.
Diagnostics table (top-right, optional) shows live volume ratio, range ratio, absorption score, percentile rank vs. the required threshold, climax status, sweep status, trend context, and bars since the last signal — useful for understanding why a bar did or didn't qualify.
Suggested use
This is a reversal/exhaustion tool, best used where volume and order flow context matter — e.g., around key support/resistance, session highs/lows, or after an extended directional move:
Use the diagnostics table while tuning inputs for a given symbol/timeframe, since default thresholds are a starting point, not a universal setting.
Start with default settings (climax volume + sweep required, trend filter on) for fewer, higher-conviction signals; relax individual gates (in the Signal Quality group) to see more candidates.
Combine with your own structure analysis (support/resistance, higher-timeframe trend) and risk management — this indicator identifies where volume and price disagree, not a complete trade plan.
The optional delta confirmation adds real intrabar buy/sell context but requests lower-timeframe data, so it will be slower to calculate and is best kept off unless you specifically want that extra filter.
Inputs
Core Absorption — averaging lookback, minimum volume ratio floor, minimum absorption score floor, close-in-range threshold
Signal Quality — percentile ranking window, minimum score percentile, require climax volume, require liquidity sweep (+ lookback), require trend context (+ MA length), cooldown bars between signals
PVSRA Candles — lookback, climax/above-average volume multipliers, candle coloring toggle and colors
Order Flow Confirmation (optional) — toggle and lower timeframe for intrabar delta
Visuals — labels, background highlight, diagnostics table, marker colors
Alerts
Two alert conditions are built in:
Bullish Absorption — swept lows, climax volume, compressed range, strong close
Bearish Absorption — swept highs, climax volume, compressed range, strong close 指標

Volume Ignition OscillatorVolume Ignition Oscillator (VIO)
Volume Ignition Oscillator flags potential exhaustion points after a sharp price move by combining three conditions: a recent large price swing, price sitting at a range extreme, and volume running hot relative to its recent average. When all three line up, the oscillator "ignites" — hence the name.
How it works
Big Move Detection — the script measures the price change over a lookback window (default 5 bars) against a multiple of ATR (default 2x, 14-period ATR). A move that clears this threshold opens a "watch window" of N bars (default 8) during which the indicator is active — up-moves open a top watch, down-moves open a bottom watch.
Range Position — price's position within the recent high/low range (default 20 bars) is calculated as a 0–1 value. The oscillator only engages when price is in the top zone (default ≥75%) during a top watch, or the bottom zone (default ≤25%) during a bottom watch.
Volume Surge — current volume is compared to its moving average (default 20-period SMA). The excess volume above that average scales the signal — the more volume expands beyond normal, the stronger the reading.
These three factors combine into a raw oscillator value, which is then EMA-smoothed. A slower EMA of the oscillator acts as a signal line.
Reading the indicator
Columns above zero (shaded toward red) = potential topping pressure: a big up-move, price near the highs, and volume ignition.
Columns below zero (shaded toward teal/green) = potential bottoming pressure: a big down-move, price near the lows, and volume ignition.
Column brightness/gradient scales with the strength of the current reading relative to the last 100 bars.
Background shading shows when a watch window is active and fades out as the window expires.
Triangle markers print when the oscillator crosses the signal threshold (default ±0.15): a down-triangle at the top signals possible short/exhaustion, an up-triangle at the bottom signals possible long/exhaustion.
Info panel (top-right, optional) shows the live oscillator value, volume ratio, range position %, and current watch zone.
Suggested use
VIO is designed as a mean-reversion / exhaustion tool, not a trend-following signal. It's best used to:
Spot potential climax moves after an extended impulsive swing on rising volume
Time partial profit-taking or tightened stops on existing trend positions
Screen for reversal candidates that can then be confirmed with price action, support/resistance, or another momentum tool
It is not intended as a standalone entry system — combine it with your own risk management and confirmation criteria. Like any exhaustion/reversal tool, it can trigger repeatedly during strong sustained trends, so treat signals as alerts to watch price action rather than automatic trade triggers.
Inputs
Big Move Detection — lookback bars, ATR length, move threshold (x ATR), post-move watch window length
Volume — volume moving average length
Range Position — range lookback, top/bottom zone thresholds
Signal — oscillator smoothing length, signal trigger level
Appearance — top/bottom colors, toggle for the info panel
Alerts
Two alert conditions are built in:
VIO Short Signal — fires on a top exhaustion cross
VIO Long Signal — fires on a bottom exhaustion cross 指標

MAs BB Lines_wt [WynTrader]MAs BB Lines --- Published : 2026-08-08
This indicator draws on the classical moving-average-and-Bollinger-Bands framework commonly taught by many specialist authors, to combine an 18-day Bollinger Band setting with a set of key moving averages (21, 50, 100, 200) to read trend direction, volatility, and potential support/resistance zones together. This script builds on that same general approach with a fully customizable, five-MA overlay and an added forward-projection layer.
Features:
📊 5 Independent Moving Averages
Each MA has its own length and type (SMA, EMA, RMA, VWMA, HMA), fully customizable to fit any trading style.
- MA1 (default: 8 EMA) — plotted as stepline for fast reaction visibility
- MA2 (default: 21 SMA), - MA3 (default: 50 SMA), - MA4 (default: 100 SMA) and - MA5 (default: 200 SMA)
📈 Bollinger Bands
Middle line 18-period, 2.0 deviation bands (basis, upper, lower) to frame volatility and price extremes around the trend structure.
🔮 Forward Projection Lines
Dashed projection lines extend from end of lines into future bars, based on each MA's recent slope (lookback-configurable). This gives traders a visual read on where each average is heading if current momentum persists.
- Lookback period: 3–10 bars (controls slope sensitivity)
- Forward projection length: 5–30 bars
- Projections can be toggled on/off
How to use it:
Watch for convergence or crossing of the moving averages and their projected paths — these often mark potential inflection points. Use the Bollinger Bands to gauge whether price is stretched relative to trend. Combine short-term (MA1) and long-term (MA5) MA slopes to confirm trend direction and strength.
Notes:
- Overlay indicator, works on any timeframe and instrument
- All moving average types and lengths are fully adjustable in settings
- Projection lines are visual guides based on recent slope, not predictive signals — always confirm with price action and other analysis
- Conceptual framework inspired by moving-average/Bollinger-Band methods commonly taught by several specialist authors and used by many professionals to identify support and resistance pivots. 指標

策略

Cloud Pro | Ichimoku Confluence Overview
An Ichimoku Kinko Hyo strategy built around one core idea: not all Tenkan/Kijun crosses are equally trustworthy. Every cross is automatically classified as Strong, Neutral, or Weak based on where it happens relative to the cloud, and you choose exactly which tiers are allowed to trigger trades — independently for long entries, long exits, short entries, and short exits. Layered on top: a higher-timeframe trend filter, ATR- or fixed-%-based risk management, and risk-based position sizing.
Features
Signal-strength tiers — TK crosses classified Strong / Neutral / Weak by their position relative to the cloud, with separate tier selectors for long entry, long exit, short entry, and short exit
Trading mode selector — run Long-only, Short-only, or Both from one script
Higher-timeframe trend filter — requires the HTF Tenkan/Kijun relationship to agree with the trade direction before entry
Flexible stop/target modes — choose ATR-based or fixed-percentage stops and targets, or disable stops entirely
Risk-based position sizing — size each trade off a target % of equity at risk given the current stop distance, rather than a flat allocation, with a max-position-size safety cap
Optional cloud-thickness size scaling — modestly scale position size based on how thick the cloud is relative to ATR, as a rough confidence proxy
Kumo twist markers — flags upcoming cloud color changes in the displaced cloud before price reaches them
Live signal dashboard — price-vs-cloud, cloud color, TK state, HTF trend, current position, and next trade size, all in one table
Clean visual defaults — cloud and dashboard on by default; Tenkan, Kijun, and Chikou lines are off by default and toggle back on individually
Brief Strategy Explanation
Ichimoku combines trend, momentum, and support/resistance into one system. This script uses the Tenkan/Kijun cross as its trigger and grades that cross's reliability by its position relative to the cloud at the time it fires — a cross above a bullish cloud is a stronger signal than one happening inside or below it. You decide, via the tier selectors, how selective to be. A higher-timeframe filter and configurable stop/target then manage trade quality and risk from there.
Tips for Use
Start on the Daily timeframe — the default 9/26/52 periods are built around it
Use liquid, trend-prone instruments — Ichimoku is trend-following at its core and tends to underperform on range-bound names
Strong Only entry tiers will produce very few signals in backtests — start with Strong + Neutral and tighten from there once you've seen trade frequency
The Chikou Span and its offset are plotted but not wired into entry/exit logic in this version — treat it as a manual visual confirmation tool if you want to eyeball it before taking a signal
Stops and targets in ATR mode are recalculated each bar rather than fixed at entry — be aware of this when reading backtest results, since it means the effective risk on a trade can drift with volatility after entry
If Use Cloud Scaling is on, it applies to both sizing modes — check the "Next Size" dashboard value before assuming Risk-Based mode is holding your risk % exactly
Backtest across a trending period and a sideways period separately — this version has no regime filter, so performance in choppy markets may look worse without one
策略

ATR & Bar Range Stop Dashboard
# Title
**ATR & Bar Range Stop Dashboard**
## About this script
**ATR & Bar Range Stop Dashboard** is a volatility-based trade-planning tool designed to provide a quick estimate of reasonable stop-loss distance based on the current market's recent price movement.
Rather than using an arbitrary fixed stop distance, the indicator measures recent volatility using either:
* **Average True Range (ATR)**, or
* **Average Bar Range (High − Low)**
and calculates hypothetical long and short stop prices around the current market price or an optional manually entered reference price.
The purpose of the indicator is not to generate entries or trading signals. It is intended to provide a **volatility reference for stop placement and trade planning**.
A structural stop should still be based on the price level at which the trade thesis becomes invalid. This tool can then be used to evaluate whether that structural stop is unusually tight or wide relative to recent market volatility.
---
## How it works
The script calculates two measures of recent price movement:
**Average Bar Range**
This is the simple average of each candle's:
`High - Low`
over the selected lookback period.
The default lookback is **20 completed bars**.
**Average True Range**
ATR measures True Range over the selected ATR lookback period.
The default is:
`ATR(14)`
The script uses **completed bars for the volatility calculations** so the baseline is not continually distorted by the currently developing candle.
The user can select either **ATR** or **Bar Range** as the basis for the calculated Average Stop.
The basic stop distance is:
`Average Stop = Selected Volatility Measure × Stop Multiplier`
The default multiplier is **1.0x**.
---
## Stop calculations
The dashboard calculates hypothetical stops on both sides of the reference price.
**Long Stop**
`Reference Price - Average Stop - Buffer`
**Short Stop**
`Reference Price + Average Stop + Buffer`
Final stop prices are rounded to the symbol's valid minimum tick increment.
The calculated stops are intended as **volatility-based reference levels**, not automatic recommendations to place an order at those exact prices.
---
## Adaptive buffer
An additional buffer places the calculated stop slightly outside the raw volatility boundary.
### Futures
In Auto mode, the futures buffer is:
`max(2 ticks, 10% of Average Stop)`
with an adjustable maximum buffer percentage.
The default maximum is **25% of Average Stop**.
This provides a small minimum buffer in lower-volatility conditions while allowing the buffer to expand as volatility increases.
### Stocks and ETFs
The default Auto buffer is:
`10% of Average Stop`
subject to the same adjustable maximum buffer percentage.
### Manual buffer
Users can disable Auto mode and specify the buffer directly in **number of ticks**.
---
## Timeframe behavior
By default, all volatility calculations use the **current chart timeframe**.
For example:
* 2-minute chart → 2-minute volatility
* 5-minute chart → 5-minute volatility
* 15-minute chart → 15-minute volatility
* Daily chart → daily volatility
A **Manual Timeframe Override** is also available when the trader wants the dashboard to reference volatility from a different timeframe.
For example, a trader executing on a 2-minute chart may choose to calculate the stop using 5-minute volatility.
---
## Reference price
By default, the script calculates the hypothetical stop levels from the **current market price**.
An optional **Manual Entry Price** can be enabled.
This is useful after entering a trade or when planning an entry at a specific price because the stop calculations remain anchored to that reference price rather than moving continuously with the market.
The dashboard still displays the live Current Price separately.
---
## Dashboard modes
### Minimal
Designed for active trading and displays only:
* Current Price
* Average Stop and its basis
* Long Stop
* Short Stop
The **Long Stop is displayed in green** and the **Short Stop in red** for quick identification.
### Full
Displays additional volatility information:
* Average Bar Range
* ATR
* Current Bar Range
* Current Bar / Average Bar ratio
* Current Price
* Average Stop and calculation basis
* Buffer
* Long Stop
* Short Stop
---
## Display options
The dashboard can be customized using:
**Table Size**
* Tiny
* Small
* Normal
* Large
* Huge
**Horizontal Placement**
* Left
* Center
* Right
**Vertical Placement**
* Top
* Middle
* Bottom
These controls provide all nine standard TradingView table-placement combinations.
---
## Suggested interpretation
The indicator is most useful as a **context tool rather than a mechanical stop system**.
For example, if a proposed structural stop is only 0.3 ATR away from the entry while normal bars are already considerably larger than that distance, the stop may be vulnerable to ordinary market noise.
Conversely, a structural stop several ATRs away may indicate that the trade requires unusually large risk relative to current volatility.
The indicator does not determine whether the underlying trade setup is valid.
A practical workflow is:
1. Identify the trade setup.
2. Determine the price level that structurally invalidates the setup.
3. Compare that distance with the dashboard's volatility-based Average Stop.
4. Determine whether the structural stop allows acceptable risk.
5. Adjust position size rather than artificially tightening a structurally necessary stop.
---
## Default settings
**Volatility**
* Average Bar Range Length: `20`
* ATR Length: `14`
**Stop**
* Stop Basis: `ATR`
* Stop Multiplier: `1.0x`
**Buffer**
* Mode: `Auto`
* Auto Buffer: `10%`
* Futures Minimum Buffer: `2 ticks`
* Maximum Auto Buffer: `25%`
**Timeframe**
* Current chart timeframe
**Display**
* Minimal
* Small
* Top Right
All parameters are configurable.
---
## Important notes
This indicator:
* Does **not** generate buy or sell signals.
* Does **not** determine market direction.
* Does **not** automatically identify structural invalidation.
* Does **not** determine position size.
* Does **not** guarantee that a calculated stop will avoid being triggered.
* Is intended as a volatility and trade-planning tool.
ATR and average bar range describe **recent historical volatility**. Future volatility can change rapidly, particularly around economic releases, earnings, market opens, news events, or periods of reduced liquidity.
Traders should use the calculated levels together with market structure, risk management, and their own trading methodology.
---
# Release notes — Version 1.0
**Initial release**
* Added ATR-based stop-distance calculation.
* Added Average Bar Range alternative to ATR.
* Added configurable stop multiplier.
* Uses completed bars for baseline volatility calculations.
* Added automatic chart-timeframe detection.
* Added optional manual timeframe override.
* Added live Current Price display.
* Added optional Manual Entry Price for fixed stop calculations.
* Added automatic futures and equity buffer logic.
* Futures Auto Buffer defaults to the greater of 2 ticks or 10% of Average Stop.
* Stocks and ETFs default to a 10% Average Stop buffer.
* Added adjustable maximum Auto Buffer.
* Added manual tick-based buffer override.
* Added Long and Short stop price calculations rounded to valid minimum tick increments.
* Added Minimal and Full dashboard modes.
* Average Stop clearly identifies whether ATR or Bar Range is being used.
* Added configurable table size.
* Added Left / Center / Right and Top / Middle / Bottom table positioning.
* Added green Long Stop and red Short Stop highlighting.
指標

Sniper Open - Complete SignalSniper Open — NY Open FVG + Liquidity + Momentum
This indicator detects a specific 3-part confluence at the New York market open (9:30-9:45 ET):
Fair Value Gap (FVG) — a 3-candle imbalance in price
Liquidity Zone alignment — the gap must sit near a validated equal-high/equal-low level (2+ touches within 24 hours)
Momentum confirmation — the confirming candle must close in the signal's direction
Order block alignment — a recent order block in the same direction must exist
All four conditions must align, during the 9:30-9:45 ET window specifically, for a confirmed signal to fire.
Backtested results (3 years of NQ data, train/test validated):
~66-71% win rate on filled trades
~13-16 point average expectancy per filled trade
Signals fire roughly once every 2 trading days
How to use it:
The small faded circles are "watching" markers — an unconfirmed setup possibly forming. Informational only, not a trade signal.
The solid triangle is the confirmed signal. When it appears, place a limit order at the entry price shown (not a market order).
If your limit order isn't filled within 15 minutes, cancel it. This happens on roughly 44% of signals — it's expected, not a malfunction. The strategy's edge comes from letting price return to the level, not chasing it.
Stop and target levels are drawn automatically alongside each signal.
Important disclaimers:
This is backtested historical data, not a live trading track record. Past performance does not guarantee future results.
This is not financial advice. Trade at your own risk and do your own due diligence.
Built and tested specifically for NQ futures at the NY open — performance on other instruments or timeframes is not validated.
No mechanical filter can eliminate all uncertainty — momentum can reverse, targets aren't always reached, and drawdowns happen even in genuinely validated strategies. 指標