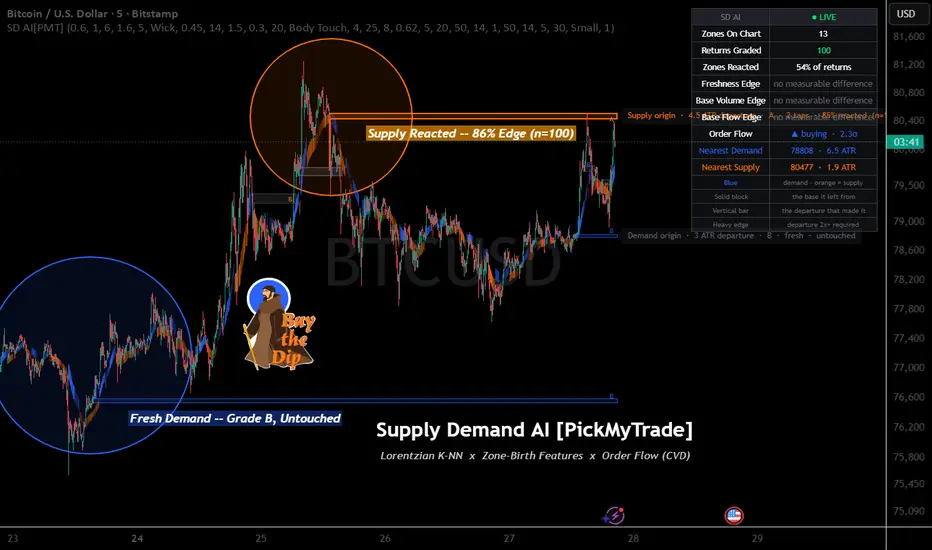
Supply Demand AI [PickMyTrade]Supply Demand AI asks the question every supply/demand tool skips: when price returns to a zone, does this arrival look like the ones that reversed — or like the ones that ate straight through?
Every supply/demand indicator draws the zone. None of them score the arrival. This one does. Each time price re-enters a zone, nine properties of the return are frozen before the outcome is known — approach speed, prior tap count, zone age, departure strength, base tightness, base volume, trend pressure, relative volume and zone width — and the arrival is voted on by a Lorentzian nearest-neighbour search over every similar return this chart has already resolved. The result is stated in the past tense: of the arrivals that looked like this, X% produced the configured reaction move before the zone failed.
The script also scores two doctrines stated everywhere in supply/demand teaching and measured almost nowhere: whether fresh zones genuinely outperform tapped ones on this chart, and whether heavy-volume bases genuinely outperform quiet ones. The info table reports what actually happened, not what the doctrine says should have.
――――――――――――――――――――――――――――――――――――――
🔷 WHAT IT MEASURES
🔸 Zone formation — base-and-departure, not pivot clustering A zone is born from a run of compressed candles (the base) followed by an impulsive leg away of a configurable ATR multiple within a fixed window — the Rally-Base-Drop / Drop-Base-Rally shape, detected as a sequence rather than asserted from a single bar. A pivot cluster has no departure to measure; a base-and-departure zone has three properties frozen at birth that a pivot never carries: how hard the market left, how tight the base was, and which side was trading volume while it sat there.
🔸 Zone geometry The origin block (solid segment) marks the actual base candles. The projection (lighter band) carries those prices forward to where they can be tested. The departure measure (vertical bar on the departure candle) shows the full distance the move reached — readable straight off the price scale. Freshness is written as text ("fresh" / "2 taps"), not encoded in a line style that has to be decoded.
🔸 Outcome — reaction magnitude, not hold-or-break A return that drives the configured ATR multiple back away from the zone edge before closing decisively through it = REACTED. A return that closes beyond the far edge by the break buffer = FAILED. A return that does neither inside the timeout window = STALLED and discarded from training — price sitting inside a zone is not evidence either way.
🔸 Two doctrine read-outs The info table reports the freshness edge (did untouched zones react more often than tapped ones on this chart?) and the base-volume edge (did heavy-volume bases outperform quiet ones?). Either can come back negative, and the table says so when it does.
――――――――――――――――――――――――――――――――――――――
🔷 THE LORENTZIAN NEAREST-NEIGHBOUR CLASSIFIER
🔸 Why Lorentzian, not Naive Bayes A Naive Bayes model was the obvious alternative and is the wrong tool here: it assumes the features are conditionally independent given the class. Departure strength, base tightness and zone width all describe the same underlying impulse from three angles — multiplying their densities counts one piece of evidence three times. A nearest-neighbour vote makes no independence assumption at all. It asks a narrower, more honest question: of the returns already resolved on this chart, what happened to the ones that arrived most like this one?
🔸 Distance metric Distance is Lorentzian — log(1 + |a − b|) — applied per axis and summed. Against a library of this size, plain Euclidean distance lets one outlier axis dominate; the log compresses extremes, so a return that is typical on eight features and unusual on the ninth still finds its true neighbours.
🔸 Shared library — supply and demand in one pool Every feature is written relative to the direction of the test, so a fast approach into demand and a fast approach into supply are the same event described the same way. Sharing one library across both directions doubles the effective sample count without mixing unlike distributions.
🔸 Shrinkage The neighbour vote is shrunk toward the library's own base rate. Without it, k unanimous neighbours read as a certainty the sample size cannot support. The shrinkage weight is expressed in neighbour-equivalents so it is independent of k.
🔸 Honest caveat — stated here, not buried in a tooltip The classifier learns as history replays, so loading a different amount of chart history changes how many returns have trained it and therefore the percentage shown on a zone. The zones themselves, their boundaries and which bars they appear on are unaffected. This is inherent to on-chart learning.
――――――――――――――――――――――――――――――――――――――
🔷 SIGNALS AND DISPLAY
🔸 Zone appearance Full-strength blue (demand) or orange (supply) border at or above the conviction threshold. Muted at the opposite end. Neutral while price is inside — the zone is neither reacting nor failing yet. Grey once consumed. A zone born from twice the required departure draws with a heavier border — the one property worth reading before any text.
🔸 Zone label Nearest live demand, nearest live supply, and any zone with a return open right now receive a worded label: zone type · departure in ATR · evidence grade (A–D) · tap count · classifier read. Every other zone speaks through colour alone, which caps visible labels at roughly three regardless of timeframe or zoom.
🔸 Evidence grade (A–D) Measures accumulated evidence only — departure strength (35%), base tightness (25%), resolved return count (20%), age (20%). Deliberately excludes the classifier's probability so the grade and the percentage remain two different statements: the grade says how much stands behind the zone; the percentage says how similar arrivals resolved.
🔸 Return history ticks A coloured tick inside the zone at every bar where one of its own returns resolved — blue for a reaction, orange for a failure. Renders each zone's individual track record in place so the percentage can be read against the evidence behind it.
🔸 Order flow band A band above the trend EMA while cumulative volume delta is rising, below it while delta is falling. Opacity scales with how strong that pressure is against its own recent range — a faint band means the tape is undecided; a solid band means one side is leaning on it. Context, not a signal: it says which side is pressing when price arrives at a zone.
🔸 Info table Zones on chart · returns graded · overall reaction rate · freshness edge · base-volume edge · base-flow edge · live order flow direction and z-score · nearest demand and supply with ATR distance. Reads LEARNING until the warmup sample count is met.
🔸 Alerts Four alertcondition() calls: price entered a zone · return reacted · return failed · any resolved return. Worded as observations. Recommended alert setting: Once Per Bar Close.
――――――――――――――――――――――――――――――――――――――
🔷 INPUTS
🔸 Zone Detection Base Candle Max Range (ATR ×) — a candle counts as base while its range is below this multiple. Lower = cleaner zones, fewer of them. Default 0.60. Min / Max Base Candles — fewest and most candles that form a valid base. Default 1 / 6. Departure Strength (ATR ×) — how far price must travel from the base before the base qualifies as a zone. The single most important setting. Default 1.60. Departure Window (bars) — bars allowed for the departure to reach its target. Default 5. Zone Boundaries — Wick or Body extent for the base. Wick is the conservative read. Default Wick. Minimum Zone Height (ATR ×) — floor on zone thickness, expanded symmetrically about the base midpoint. Default 0.45. ATR Period — volatility yardstick for all distances. Default 14.
🔸 Return Resolution Reaction Target (ATR ×) — how far back away from the zone counts as a REACTION. Default 1.50. Break Buffer (ATR ×) — how far beyond the far edge price must CLOSE to count as a failure. Default 0.30. Return Timeout (bars) — bars a return stays open before being discarded as STALLED. Default 20. Zone Consumed On — Wick Touch / Body Touch / 50% Fill / Full Fill. Governs retirement only; returns always measure from the first wick. Default Body Touch. Max Returns Per Zone — a zone revisited this many times behaves like a range boundary. Default 4.
🔸 Probability Engine Warmup Samples — resolved returns required before the classifier replaces the running reaction rate. Default 25. Neighbours Compared — k in the nearest-neighbour vote. Smaller = more local; larger drifts toward the library rate. Default 8. Conviction Threshold — probability at or above which a zone draws at full conviction. Default 0.62. Approach Window — bars used to measure how fast price entered the zone. Default 5. Volume Baseline — averaging window for relative volume. Default 20. Trend EMA Period — reference for the trend-pressure feature. Default 50.
🔸 Order Flow Order Flow Band — show / hide. Default on. Flow Momentum Period — lookback for the rate of change of CVD. Default 14. Flow Band Width (ATR ×) — height of the band from the EMA to its outer edge. Default 1.00. Flow Normalisation Window — z-score window so the band reads the same across instruments. Default 50.
🔸 Visual Demand / Supply / In-zone / Consumed Colours · Show Zones · Zone Labels · Return History Ticks · Keep Consumed Zones · Max Live Zones (cap on live slots; consumed zones are free) · Zones Per Side (nearest N zones above and below price) · Show Zones Within ATR × (safety ceiling) · Label Every Zone · Label Size · Zone Border Width · Zone Evidence Grade.
🔸 Display Zen Mode — hides labels and info table; zones and ticks remain. Show Info Table.
――――――――――――――――――――――――――――――――――――――
🔷 REQUIREMENTS AND LIMITATIONS
🔸 The classifier reads what this chart has seen — not a pre-trained model and not a fixed statistical table. On a chart with thin history or a symbol the market has recently repriced, the library may be small and the read thin. The sample count travels with every zone label and the table header so this is never hidden. 🔸 Loading a different amount of chart history changes how many returns have trained the classifier, which changes the percentage shown on a zone. The zones themselves are unaffected — this is inherent to on-chart instance-based learning. 🔸 Zone geometry is fixed at birth and never re-centred. No request.security() call is made anywhere. Test state advances only on barstate.isconfirmed. No future data is referenced. 🔸 The departure is measured over bars that have already closed. A zone appears on the bar its departure qualifies and never moves afterwards. 🔸 Base volume and base flow are estimated from the close-position formula — a synthetic proxy, not true bid/ask data. The classifier adapts to the noise, but the quality of the read improves on instruments with genuine intrabar price travel. 🔸 The evidence grade (A–D) and the classifier percentage are two different statements by design. Do not read either alone. 🔸 Past resolved returns are hypothetical observations — no commission, no slippage — and are not a record of trading results. This script does not issue trade instructions and nothing in it is financial advice.
――――――――――――――――――――――――――――――――――――――
Built natively in Pine Script® v6. Lorentzian k-nearest-neighbour classifier trained on-chart from resolved supply/demand returns — no external libraries, no lookahead, no repainting. Zone formation uses a base-and-departure state machine; outcome is reaction magnitude, not hold-or-break. Attribution: the Rally-Base-Drop / Drop-Base-Rally construction is long-established public technical analysis, implemented independently here. The evidence grade and drawing layer are shared with the author's own Support Resistance AI — stated here plainly rather than left for a reader to find.
Open source — Mozilla Public License 2.0. 指標

Volatility Position Risk Planner [Pineify]Volatility Position Risk Planner
Overview
This indicator converts a trade idea into a stress-sized quantity. Its corridor separates target, nominal risk, and reserve; a ledger identifies the binding constraint.
Problem Definition
A basic position size calculator divides account risk by entry-to-stop distance. It ignores fills beyond a stop during gaps, slippage, and per-unit cash costs. A tight stop can also produce notional exposure disproportionate to the account. The result may satisfy nominal loss math while violating another capital limit. This script instead asks what quantity fits both a stated stress-loss budget and an exposure ceiling under the units supplied by the user.
Design Rationale
Technical invalidation and execution uncertainty are separate. The stop says where the setup fails; ATR gap allowance and tick slippage extend a stress boundary. Cash cost remains in currency units. This replaces inflating one ATR multiplier, which would mix stop logic and reserve.
Risk and notional capacity are calculated independently. The smaller candidate is rounded down, leaving some budget unused but avoiding either limit. The target uses stress price distance for a consistent visual scale; it is not a forecast.
Key Features
ATR, structure, or wider-of-both stop logic.
Separate gap, slippage, and cash-cost reserves.
Risk and exposure candidates with a binding constraint.
Step rounding plus utilization and headroom diagnostics.
How It Works
Current close rolls with price; Manual price fixes entry. ATR comes from chart OHLC. Stop distance is ATR times its factor, directional distance to structure, or the wider valid distance. The stop is tick-normalized.
The reserve adds ATR times Gap reserve and slippage ticks, producing a stress edge. Nominal unit risk is stop distance times point value plus cash cost; stress unit risk uses the full distance to that edge. Account size times risk percent, divided by stress unit risk, gives the risk candidate.
Entry times point value estimates unit notional. Account size times Maximum notional exposure, divided by unit notional, gives the exposure candidate. The smaller quantity is rounded down by step. Nominal risk, stress risk, reserve cash, both utilizations, and unused budget are then reconciled. Warm-up, wrongly sided stops, invalid units or prices, and sub-step quantities are rejected.
How Multiple Indicators Work Together
This is a causal chain, not a signal stack. ATR scales stop and gap allowance; structure supplies price invalidation. Point value converts distance into cash risk. Risk budget limits stress loss; exposure limits concentration. Removing ATR ignores current range, removing structure loses chart context, and removing either capital constraint leaves one dimension unchecked. Corridor and ledger expose each link.
Trading Ideas and Insights
Compare the same setup under different volatility, reserve, and exposure assumptions. RISK means stress-loss capacity is tighter; EXPOSURE means concentration controls size; BOTH means candidates are close within half a quantity step. A large amber zone relative to red shows that execution assumptions materially reduce size. Headroom is cash left after rounding, not permission to exceed the constraint.
Unique Aspects
The structural contribution is a two-stage constraint lattice. Technical invalidation and execution overrun first become auditable loss layers. The stress-loss candidate then competes with an independent exposure candidate before step rounding. The ledger reconciles final quantity to both budgets and names the binding one, showing how much risk belongs to the stop, how much to reserve, and when exposure overrides them.
How to Use
Choose direction and a rolling or manual entry.
Select ATR, structure, or combined stop logic; verify stop direction.
Enter reserve, cost, account, point value, step, and exposure data from broker specifications.
Proceed only at PLAN READY; note quantity and binding constraint.
Read amber as a stress boundary, not another order or a guaranteed fill limit.
Customization
ATR length and multiple control the volatility stop. Gap reserve adds a scaled allowance; slippage ticks add a fixed allowance. Cash cost must share the account-currency and quantity convention. Exposure above 100% should be deliberate leverage, not assumed margin. Visual switches hide corridor, candidates, labels, or ledger without altering calculations or alerts. Projection bars change drawing length only.
Assumptions and Limitations
This calculator omits liquidity, partial fills, spreads, rejection, margin tiers, liquidation, currency conversion, financing, tax, and minimum notional. A gap can exceed reserve, so stress risk is a scenario, not maximum loss. Point value, cost, step, currency, and exposure need compatible units; metadata may differ from a broker contract.
Current close, ATR, corridor, and quantity can change intrabar. Manual entry is fixed, but ATR values still move. Confirmed-bar alerts can miss a reversed intrabar touch, and gaps can cross boundaries before processing. Drawings show only the latest plan. The script estimates no probability, return, win rate, or stop quality. Nonstandard charts and illiquid markets can make ATR a poor execution proxy.
Conclusion
This planner separates risk, reserve, and exposure. Reliability still depends on verified units, stop logic, and realistic stress assumptions.
指標

Volatility-Scaled Range Level with Term Structure FilterWHAT IT DOES
This indicator plots a single volatility-scaled price level and evaluates three independent market-condition filters against it. The level sits one Average True Range below the prior period's close, so it widens automatically when realized volatility expands and tightens when volatility contracts. A summary table reports the level, its distance from current price as a percentage, and the state of each filter.
It is a reference and condition-monitoring tool. It does not generate buy or sell orders, does not connect to a broker, and takes no position on whether any particular trade should be placed.
HOW IT WORKS
The level is computed on a higher timeframe than the chart:
level = close of higher timeframe − ATR(14) of higher timeframe
ATR here is Wilder's RMA of True Range, which is what ta.atr() returns. Both components are pulled with request.security(..., lookahead = barmerge.lookahead_off) and referenced at index , so the value is drawn from the last completed higher timeframe bar and does not repaint. Setting the timeframe input to W produces a weekly-anchored level; D produces a daily-anchored one.
The level is then floored to a user-defined increment (default 5). This is optional rounding for users who want the level snapped to a round number rather than an arbitrary decimal.
Three filters are evaluated independently:
Term structure. The ratio of a short-dated volatility index to a longer-dated one (default CBOE:VIX over CBOE:VIX3M). A ratio below the threshold indicates contango, the normal state. A ratio above it indicates backwardation, which historically coincides with volatility clustering and trending decline. Both symbols are user inputs and can be swapped for other instruments.
Absolute volatility floor. A minimum level on the short-dated volatility index. Below this, the distance implied by ATR is small in absolute terms.
Optional trend filter. Price above its 21-period EMA.
The table reads GATES PASS only when all enabled filters are satisfied. An alert() call fires on the first bar of each new higher-timeframe period, with the level, the distance, and the filter states embedded in the message text.
HOW TO USE IT
Add to a daily chart. Set the ATR timeframe input to match the horizon you care about: W for a weekly-anchored level, D for a daily one. Confirm your data plan resolves both volatility symbols; substitute alternatives in the Symbols group if not.
The panel position is adjustable through the "Panel offset right of centre (%)" input, from 0 for centred through 45 for the right edge.
For notifications: right-click the chart, Add alert, select this indicator as the condition, choose "Any alert() function call", and set the frequency to Once Per Bar so it fires at the start of a new period rather than at its close.
The "Anchor on forming period" input switches the level to use the in-progress higher-timeframe bar rather than the last completed one. This produces a value that updates continuously through the period. It is intended as a preview of where the next period's level is forming, not as a signal, and it will change intrabar.
ORIGINALITY
Prior-close-minus-ATR levels are a well-established concept and several published indicators plot them, most notably Saty Mahajan's ATR Levels, which plots a full Fibonacci ladder of them across six timeframe modes. This script is not a republication of that work and does not reuse its code. It differs in scope and purpose:
It plots one level rather than a ladder, to keep the chart readable when the level is the only thing being monitored.
It adds volatility term structure and absolute volatility as explicit gating conditions, which existing ATR level indicators do not evaluate.
It rounds the level to a user-defined increment.
It emits a dynamic alert message containing the computed values, so the notification is self-contained and requires no chart lookup.
The arithmetic that produces the level is standard and deliberately matches the conventional definition so that values are comparable with other implementations.
LIMITATIONS AND SHORTCOMINGS
The level is descriptive, not predictive. It describes a distance in volatility units. Price reaching or not reaching it carries no guarantee of any kind.
The term structure filter depends on external symbols. If your data plan does not provide them, the filter cannot be evaluated and the table will not populate correctly. Verify both symbols resolve before relying on it.
Volatility index data is daily. The filter therefore updates on a slower cadence than the chart and can be stale relative to fast intraday moves.
The absolute volatility floor is a coarse proxy. It says nothing about the actual pricing of any instrument.
On index CFD feeds, the underlying value can differ slightly from the cash index. Where the level is near a rounding boundary, the rounded output may differ between feeds.
The forming-period preview mode updates continuously and is not a fixed reference.
No backtest or performance statistics are presented, because this is an indicator and not a strategy. Nothing here has been tested as a system.
CREDITS
The prior-close-minus-ATR level concept is widely used. Saty Mahajan's open-source ATR Levels indicator is the best-known implementation on TradingView and is worth reviewing for a fuller treatment of the concept across multiple timeframe modes and Fibonacci ratios.
DISCLAIMER
This script is provided for educational and analytical purposes. It is not financial, investment, or trading advice, and it is not a recommendation to buy or sell anything. Volatility-based levels describe historical range behaviour and carry no predictive guarantee. Any use of this tool is at your own risk.# TradingView publication description 指標

Custom Key LevelsCustom Key Levels
Simple tool for plotting your own price levels — support/resistance, liquidity zones, order blocks, whatever you're tracking. Set up to 10 levels, name them yourself, get alerted when price hits them. No auto-detection, no fancy calculations — just your levels, on your chart, the way you want them to look.
What it does
10 level slots, each with its own on/off switch, name, price, and color
Pick short tags near the current price or full lines across the whole chart
Solid/dashed/dotted, adjust width and label size
Turn labels off if you just want clean lines with no text
Crossing alerts built in — get pinged when price crosses a level, and the alert message tells you which one
指標

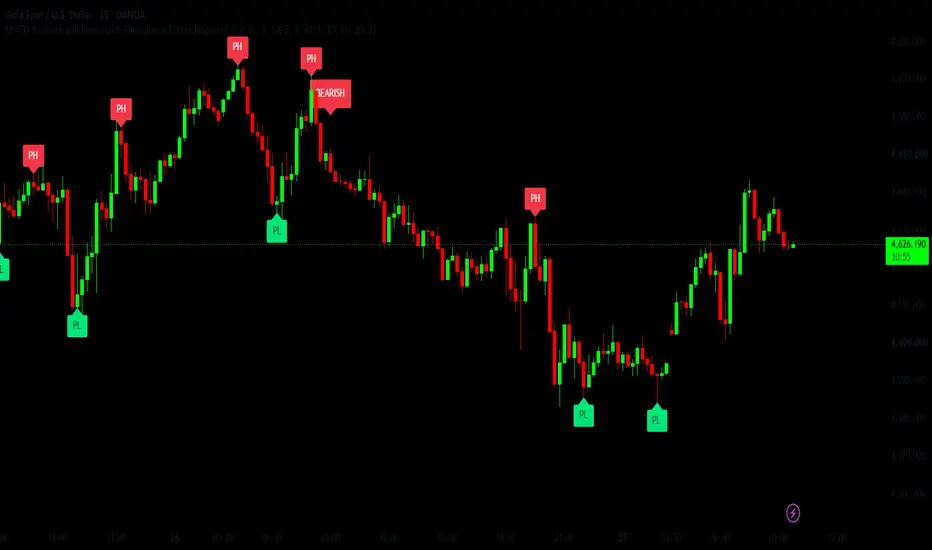
MACD Pullback Validation with Divergence Filters [algotim]MACD Pullback Validation with Divergence Filters is a momentum confirmation indicator designed to identify continuation opportunities after temporary pullbacks rather than generating signals from every MACD crossover.
Instead of relying on a single event, the script evaluates multiple stages of market behavior. It begins by detecting pullbacks within an existing momentum cycle, waits for momentum recovery, confirms that price and the MACD histogram are no longer weakening, and optionally verifies that the setup occurs near significant price locations using pivot-derived support/resistance levels or Bollinger Band extremes.
The objective is to reduce low-quality MACD signals by requiring several independent conditions to align before a bullish or bearish signal is displayed.
Problem Statement
Traditional MACD crossover signals frequently occur during ranging markets or immediately after short-lived momentum fluctuations. Likewise, divergence signals alone often appear too early and do not necessarily indicate that momentum has already shifted back in the anticipated direction.
This indicator addresses that limitation by requiring multiple confirmation stages rather than treating each condition as an independent trading signal.
Instead of responding to isolated events, it evaluates whether a pullback has occurred, whether momentum is rebuilding, whether a recent divergence supports the move, and whether price is located in an area where reversals may be more meaningful.
Methodology
The analytical framework consists of several sequential validation layers.
First, MACD crossover events occurring above or below the zero line are monitored to identify temporary pullbacks within an existing momentum cycle. These crossover events establish the recent pullback state.
Next, the script monitors the MACD histogram. Bullish momentum requires the histogram to remain above zero while increasing relative to the previous bar. Bearish momentum requires the histogram to remain below zero while decreasing.
The indicator then waits for the MACD line itself to cross the zero line, treating this as evidence that momentum has shifted back in the direction of the prevailing move.
Histogram divergence is calculated using confirmed pivot highs and pivot lows. Regular bullish divergence requires price to form a lower low while the histogram forms a higher low. Regular bearish divergence requires price to form a higher high while the histogram forms a lower high. Hidden divergence calculations are also available for users who wish to visualize continuation-type divergence.
Finally, optional contextual filters may be enabled.
The Support/Resistance filter checks whether the current price is interacting with recently confirmed pivot-based levels.
The Bollinger Band filter requires bullish setups to occur after closing below the lower band and bearish setups after closing above the upper band, helping identify momentum reversals from statistically extended price conditions.
Signals are generated only after every enabled validation layer has been satisfied.
Signal Workflow
Bullish workflow
1. Detect a recent bearish MACD crossover occurring above the zero line to identify a pullback.
2. Confirm a regular bullish MACD histogram divergence using pivot comparisons.
3. Require the MACD histogram to begin strengthening.
4. Wait for the MACD line to cross back above the zero line.
5. Optionally require interaction with recent pivot-based support.
6. Optionally require price to close below the lower Bollinger Band.
7. Display a bullish signal.
Bearish workflow
1. Detect a recent bullish MACD crossover occurring below the zero line.
2. Confirm a regular bearish MACD histogram divergence.
3. Require bearish histogram acceleration.
4. Wait for the MACD line to cross below the zero line.
5. Optionally require interaction with recent pivot-based resistance.
6. Optionally require price to close above the upper Bollinger Band.
7. Display a bearish signal.
Why This Indicator Is Different
Many MACD indicators generate signals immediately after crossovers, while divergence indicators typically evaluate price and momentum independently.
This script integrates these concepts into a sequential validation framework where each condition serves a different analytical purpose.
The pullback logic identifies temporary counter-trend momentum.
The histogram evaluates whether momentum is rebuilding.
The zero-line crossover confirms broader momentum alignment.
Divergence provides evidence that momentum and price are no longer moving in agreement.
Optional pivot interaction and Bollinger Band filters add market-location confirmation before a signal is produced.
Rather than displaying every crossover or every divergence, the indicator waits until multiple independent conditions align before producing a trading signal.
Inputs
The script includes configurable parameters for:
* MACD fast, slow, and signal periods
* Pullback lookback window
* Divergence pivot lengths
* Divergence range settings
* Optional hidden divergence display
* Optional Support/Resistance validation
* Pivot sensitivity
* Optional Bollinger Band confirmation
* Bollinger Band length and standard deviation
Alerts
Built-in alert conditions are available for:
* Bullish Signal
* Bearish Signal
* Regular Bullish Divergence
* Hidden Bullish Divergence
* Regular Bearish Divergence
* Hidden Bearish Divergence
Practical Usage
The indicator is intended for traders who prefer waiting for momentum confirmation after temporary pullbacks instead of reacting to every MACD crossover.
Optional Support/Resistance and Bollinger Band filters can be enabled to make signal selection more restrictive when additional price-location confirmation is desired.
Limitations
MACD histogram divergence relies on confirmed pivot highs and lows, so divergence signals are only confirmed after the required pivot bars have formed.
Support and resistance levels are derived from pivot calculations and represent algorithmically identified swing points rather than manually drawn market structure.
Like any momentum-based indicator, performance may vary across different market conditions and should be evaluated alongside a broader trading plan and appropriate risk management.
Notes
This indicator is intended as an analytical decision-support tool. It combines momentum analysis, pullback recognition, divergence detection, and optional contextual filters into a structured confirmation process rather than relying on any individual condition as a standalone trading signal. 指標

Dynamic Range Tool [vault]Dynamic Range Tool is a complete session range framework. Instead of stacking five separate tools every morning you get one: the session range with its quarters and projections, average range targets from the daily, weekly and monthly timeframes, daily and weekly opens, center mass of the previous daily and weekly candle, and automatic order blocks. One script, one chart, alerts on every level.
THE SESSION RANGE
The engine is a time window defined in EST. The default is 19:00 to 02:45, which is the asian session plus the london open lead in. The script tracks the highest high and lowest low inside that window and builds three lines from it: range high, range low, range mid. Those lines are then extended to whatever hour you set in "Extend To Hour", 19:00 the next evening by default, so the levels sit in front of you for the entire trading day.
On top of that you get the range quarters at 25% and 75%, drawn dashed in the theme accent color. Those are the levels price tends to react to on the way back into the middle.
Two vertical markers show the range gate and the moment the window closes, so you never lose track of where the measurement ends.
RANGE PROJECTIONS
Turn on "Show Range Projection" and you get the range mirrored above and below the midpoint at 1x, 1.5x, 2x and 2.5x. Classic range expansion logic. If the asian session printed 40 points you already know where 1x and 2x sit before london even starts. Upper levels use the theme top color, lower levels the bottom color.
ADR / AWR / AMR TARGETS
This is the part that does the heavy lifting. The script computes an average candle range (14 periods by default) separately on the daily, weekly, monthly and a custom intraday timeframe (60 or 240 minutes), then projects:
- Daily projected high = day low + ADR
- Daily projected low = day high - ADR
- The same for the week and the month, with progressively thicker lines
- The same for your custom timeframe
- Top hash and bottom hash, the range midpoint plus and minus half an ADR
- A second pair at the midpoint plus and minus a full ADR
Every level is labelled on the right and fires its own alert. Once the day has already delivered its average range the projected high and low cross over each other, and the script deletes both lines and their labels automatically so you are not left staring at levels that no longer mean anything.
Underneath, semi transparent zones are shaded between the range midpoint and the ADR projection. They show how much room is left before the average day is fully used up.
OPENS AND CENTER MASS
- Daily open and weekly open, colored dynamically: bottom color when price trades above the open, top color when below. One glance tells you which side of the open you are on.
- Center mass daily and weekly, the midpoint of the previous daily and weekly candle body. Thick neutral line, one of the better mean reversion magnets on intraday charts.
ORDER BLOCKS
A separate module. The script measures momentum as the percentage change of open against the open four bars back. When that change crosses the sensitivity threshold (25 by default, meaning 0.25%) it walks back 4 to 15 bars, finds the last candle opposite to the impulse, and turns it into a block. Mitigation is your choice of wick or close. Blocks are removed automatically once mitigated, and price entering an active block triggers an alert.
A minimum spacing of 5 bars between signals keeps the chart clean in chop.
STATS PANEL
Top right corner: last session range, ADR, AWR and the custom range value. Displayed in pips or in ticks depending on the toggle.
THEMES
The build ships with a full theme engine:
- Vault Red (default) - red upside, blue downside, white structure
- Vault Classic - the original orange and blue palette
- Ice - cold blues
- Neon - magenta and green
- Gold - gold and purple
- Mono - white and greys for dark charts
- Custom - unlocks every manual color picker
Switching a theme repaints the range lines, targets, zones, labels, order blocks and panel text in one move. The range center line is white now instead of black, so it is finally visible on a dark chart.
ALERTS
Weekly, monthly, daily and custom projected high and low, top hash, bottom hash, price inside bullish block, price inside bearish block. All fire once per bar.
HOW TO USE IT
1. Intraday chart. Minute based timeframes are read directly from the chart resolution.
2. Set the session window in EST for your market. For index futures leave it at 19:00 to 02:45.
3. Start the day with three questions: which side of the range am i on, which side of the daily open am i on, how much of the average range is still unused.
4. Treat the upper and lower ADR targets as places to take risk off, not places to enter.
5. The range mid and the center mass lines are return levels, not continuation levels.
TECHNICAL NOTES
Higher timeframe data (daily, weekly, monthly, custom) is requested with lookahead enabled. That keeps the levels anchored on historical bars, but it also means this script is not suitable for bar by bar backtesting or for driving an automated strategy. It is a context drawing tool, not a simulation.
All drawing is anchored to bar time rather than bar index, so levels stay locked to the clock.
The "ADR Days" input is a leftover from the original and does not affect any calculation. The averaging length lives in "ADR period".
Nothing here is financial advice. The tool draws context, the decisions are yours.
Based on Dynamic Range Tool V1 by Black Box Trading. 指標

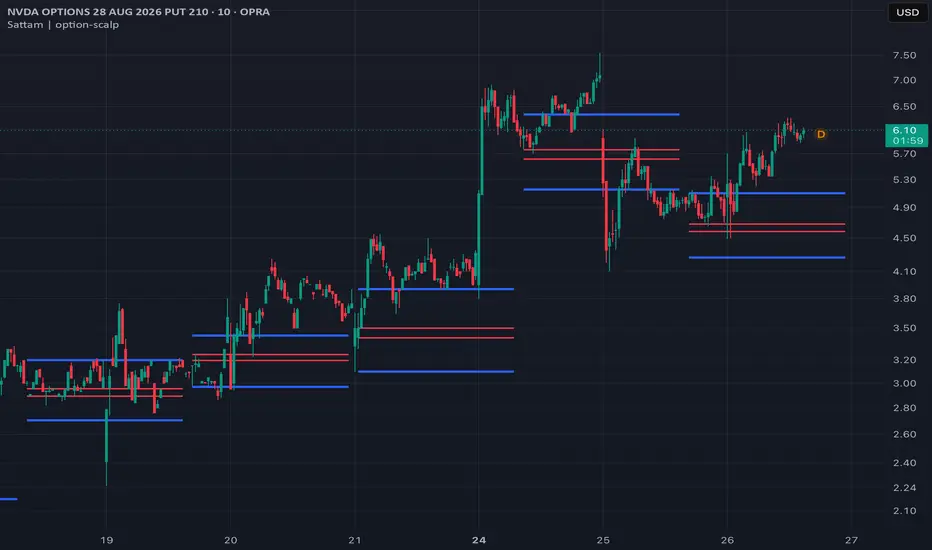
Sattam | option-scalpVolatility Projection Zones
Every 52 bars the indicator takes a reading of the market and projects where
price could travel next, based on how volatile the market actually is right now.
WORKS ON EVERY MARKET — AND HOLDS UP ON OPTIONS
There is not a single fixed value anywhere in this script: no pip counts, no
point targets, no price assumptions. Every distance it draws is derived from the
instrument's own volatility, so it behaves the same way on futures, forex,
indices, crypto, stocks — and on options contracts, which is where most
ATR-based tools quietly fall apart.
Options are a hostile case: premiums move in cents, a contract can lose half its
value in three bars, sessions are full of gaps, and plenty of bars print with no
trade at all. A pure ATR projection lags badly through moves like that and draws
targets far too tight. This script handles it by taking the LARGER of two
measures — the ATR projection, or the range of the anchor window itself. On
liquid futures the ATR is always the larger one and the floor never shows; on an
option, when a window holds a collapse, the window wins and the projection stays
honest.
HOW IT WORKS
At each cycle the script looks at the last 3 bars and finds the extreme that
price has moved furthest away from — if price is sitting near the top of that
little range, the low becomes the anchor, and vice versa. From that anchor it
projects a distance equal to 3 x ATR(14), or the range of those 3 bars when that
is wider.
Four lines are drawn per cycle:
- Two thick lines — the anchor and the full projection target
- Two thin lines — the 50% and 61.8% marks in between
Each set extends 49 bars, stopping just before the next cycle begins, and the
last 8 sets stay on the chart.
HOW TO READ IT
The direction of the projection is the cycle's bias. A set projecting upward
means the anchor sits below price as support, with the levels above as upside
reference. The two thin lines are the natural partial targets; the far thick
line is the full measured move.
Because the projection scales with volatility, the levels widen in fast
conditions and tighten in quiet ones automatically.
SETTINGS
Cycle length - bars between projections (default 52)
Anchor window - bars used to pick the anchor (default 3)
ATR length/mult - the projection distance (default 14 / 3.0)
Inner ratios - the two intermediate levels (0.5 / 0.618)
Cycle anchor - where the cycle starts counting: Session, Week, or a
manual phase
Display - colors, widths, line length, sets kept
NOTES
This is a levels framework, not a signal system. It draws on every cycle
regardless of trend or range conditions, and it has no entry filter of its own —
combine it with your own read of structure and context.
Not financial advice. Test on your own instruments and timeframes before relying
on it.
خطوط الهدف حسب حركة السوق
المؤشر كل ٥٢ شمعة يوقف ويقيس لك السوق، وبعدين يمد أربعة خطوط تقول لك
وين ممكن يوصل السعر. والمسافة مو رقم كتبته أنا، هي من حركة السوق نفسه
في ذيك اللحظة — سوق هايج يعطيك خطوط بعيدة، وسوق هادي يعطيك خطوط قريبة.
يشتغل على كل الأسواق — وأقوى شي على الاوبشن
ما فيه في المؤشر ولا رقم ثابت. لا نقاط ولا بيبس ولا أهداف محفوظة. كل
مسافة يرسمها يطلعها من حركة الأداة اللي أنت فيها. عشان كذا نفس الشغل
يمشي على الذهب والفوركس والمؤشرات والعملات الرقمية والأسهم، ويمشي على
عقود الاوبشن كمان — وهذي بالذات وين أغلب المؤشرات تخرب وأنت ما تدري.
ليش الاوبشن صعب؟ لأن سعر العقد يتحرك بالسنتات، وممكن العقد يطيح نص
قيمته في ثلاث شموع بس، والجلسات فيها فجوات كثيرة، وشموع تعدي بدون ولا
صفقة. مقياس ATR لحاله يتأخر على حركة زي كذا، فيرسم لك أهداف قريبة ما
تسوى شي.
الحل اللي فيه: يقارن بين شيئين وياخذ الأكبر — إما مسافة ATR، وإما مدى
الشموع الثلاث اللي طلعت منها نقطة البداية. في الأسواق العادية ATR يطلع
أكبر دايماً وما تحس بهالشي أصلاً؛ وفي الاوبشن لما تصير طيحة قوية، مدى
الشموع يطلع أكبر وياخذه المؤشر — فتطلع الخطوط واقعية مو مضحكة.
كيف يشتغل بالضبط
كل دورة يشوف آخر ٣ شموع، ويشوف السعر حالياً قريب من فوق ولا من تحت:
- السعر قريب من فوق؟ ياخذ القاع نقطة بداية ويمد الخطوط طالعة
- السعر قريب من تحت؟ ياخذ القمة نقطة بداية ويمد الخطوط نازلة
يعني دايماً يبدأ من الطرف الأبعد عن السعر.
ومن نقطة البداية هذي يقيس المسافة (٣ أضعاف ATR أو مدى الشموع الثلاث،
أيهم أكبر) ويرسم:
- خطين سميكين: واحد عند نقطة البداية، وواحد عند الهدف الكامل
- خطين رفيعين بينهم: عند ٥٠٪ و ٦١.٨٪ من المسافة
كل مجموعة خطوط تمشي ٤٩ شمعة وتوقف قبل ما تبدأ المجموعة الجديدة، ويبقى
لك على الشارت آخر ٨ مجموعات.
كيف تقراه
- الخطوط طالعة فوق؟ الدورة ميولها صعود، ونقطة البداية تحت تصير دعم
- الخطوط نازلة تحت؟ الدورة ميولها هبوط، ونقطة البداية فوق تصير مقاومة
- الخطين الرفيعين: أهداف أولى وثانية، مكان طبيعي تجني فيه جزء
- الخط السميك البعيد: الهدف الكامل للحركة
الإعدادات
Cycle length - كل كم شمعة يرسم مجموعة جديدة (الافتراضي ٥٢)
Anchor window - كم شمعة ياخذ منها نقطة البداية (٣)
ATR length/mult - مقياس المسافة (١٤ و ٣ أضعاف)
Inner ratios - الخطين الرفيعين (٠.٥ و ٠.٦١٨)
Cycle anchor - من وين تبدأ الدورة: مع الجلسة، مع الأسبوع، أو يدوي
Display - ألوان وسماكات وطول الخطوط وعدد المجموعات
كلام لازم يتقال
المؤشر يعطيك مستويات، مو إشارات دخول وخروج. يرسم كل دورة سواء السوق
ترند أو عرضي، وما فيه فلتر يقول لك ادخل الحين. استخدمه مع قراءتك أنت
للسوق.
وهذا مو توصية شراء ولا بيع. جربه على أدواتك وفريماتك قبل لا تعتمد عليه بصفقاتك. 指標

Adaptive Rolling Z-Score Channel█ ABOUT
Most channel indicators draw their upper and lower lines a static distance from a moving average and leave them there. Bollinger Bands are the familiar example: the bands sit a fixed number of standard deviations from the average, and that number stays the same whether the market is crawling or running.
The Rolling Z-Score Channel decides that distance from the market's own recent behavior instead. It tracks how far price has actually been straying from its average over recent history, then places the bands where the more extreme of those moves have been landing. When conditions get choppier, the bands widen on their own. When things settle, they draw back in.
The practical effect is a channel where reaching the outer band means roughly the same thing across different market conditions and different instruments: price has stretched unusually far compared to how it has been moving lately. It plots directly on the price chart, so the levels can be read against candles, structure, and your other tools without switching panes.
█ HOW IT WORKS
The indicator measures how far price sits from its rolling mean, expressed in standard deviations — a z-score.
In Adaptive mode, the band levels come from the recent distribution of that z-score making it adjust to changes in market conditions more quickly. The indicator looks at where price has actually been reaching over multiple shorter lookbacks and places the upper and lower bands of those ranges. The two sides of the rolling mean are calculated independently, so the channel can be asymmetric when price has been extending further in one direction than the other. A minimum width floor prevents the bands from collapsing onto the mean during quiet periods.
Fixed Z-Score mode is also available if you prefer conventional static bands at a multiplier you set yourself.
The z-score and the band levels can each be smoothed, with a choice of filters. Smoothing reduces bar-to-bar jitter in the levels at the cost of some responsiveness.
█ READING THE INDICATOR
• Basis line — the rolling mean, and the reference point the channel is built around. Optional gradient coloring shifts with the current deviation.
• Outer bands — the adaptive extremes. Price reaching a band means deviation is large relative to its own recent range.
• Inner bands — an intermediate reference, plotted at a user-set fraction of the outer distance.
• Fills and glow — the shaded zones separate the upper and lower halves of the channel. When price closes outside a band, the area between price and that band fills to mark the excursion.
• Re-entry markers — triangles printed when price closes back inside the channel after having closed outside it.
Alerts are included for band breaks, re-entries, and basis crosses.
█ SUGGESTED USE
The channel is a context tool. It describes where price sits within its recent statistical range, which is useful for entries, gauging extended and possible reversal ranges, and setting reference levels.
A few things worth understanding before using it:
The channel widens quickly when a range breaks out into a trend, since both the deviation measure and the percentile levels expand at the same time. This is intended behavior for a distribution-following band, but it means the tool is least informative during the transition from range to trend.
Defaults are set for intraday futures charts. The rolling window and percentile settings are the main levers if you are adapting it to a different instrument or timeframe. Thoroughly test out various settings for your specific chart. 指標

Global Macro RegimeThe Global Macro Regime is a top-down macro nowcasting and portfolio allocation tool that provides a consolidated view of the market-implied macro regime. It independently evaluates 30 key global markets across equities, fixed income, commodities, and currencies to determine the prevailing macro regime, which informs the model’s portfolio preferences and regime-specific exposures. It also features built-in alerts and an integrated backtester that enable investors to monitor regime changes and evaluate asset performance across different macro environments.
At its core, the model aggregates 30 independent cross-asset market signals to identify shifts in the market’s growth and inflation outlook. Rather than relying on backward-looking economic data, the model derives these signals in real time from evolving trends across global markets. By focusing on growth and inflation, the model captures two of the primary macroeconomic forces driving asset prices. The four possible combinations of growth and inflation define four distinct macro regimes, each of which tends to favor different portfolio preferences and exposures:
Goldilocks (Growth ↑, Inflation ↓): Improving growth with low/declining inflation.
Reflation (Growth ↑, Inflation ↑): Improving growth with high/rising inflation.
Inflation (Growth ↓, Inflation ↑): Deteriorating growth with high/rising inflation.
Deflation (Growth ↓, Inflation ↓): Deteriorating growth with low/declining inflation.
Goldilocks and Reflation represent Risk-On regimes, while Inflation and Deflation represent Risk-Off regimes. Each of the 30 selected markets is evaluated independently as either a growth or inflation signal. Markets signaling improving growth contribute to both Goldilocks and Reflation, while markets signaling deteriorating growth contribute to both Inflation and Deflation. Markets signaling high/rising inflation contribute to both Reflation and Inflation, while markets signaling low/declining inflation contribute to both Goldilocks and Deflation. The selected markets are grouped into equities (10), fixed income (10), commodities (6), and currencies (4):
Equities = S&P 500 Index (SPX), Russell 2000 Index (RUT), STOXX Europe 600 Index (SXXP), Nikkei 225 Index (NI225), Hang Seng Index (HSI), MSCI Emerging Markets Index Futures (MME), High Beta / Low Volatility Ratio (SPHB/SPLV), Cyclicals / Defensives Ratio (XLY/XLP), S&P 500 Volatility Index (VIX), and 3M Implied Correlation Index (COR3M).
Fixed Income = US 2Y Treasury Yield, US 10Y Treasury Yield, German 10Y Bund Yield, UK 10Y Gilt Yield, Japan 10Y JGB Yield, US 10Y Breakeven Inflation Rate, US CCC Distressed Index Option-Adjusted Spread, US High Yield Index Option-Adjusted Spread, US Investment Grade Corporate Index Option-Adjusted Spread, and US Bond Volatility Index (MOVE).
Commodities = Brent Crude Oil Futures (BRN), Agricultural Commodities (DBA), Industrial Metals (DBB), Copper Futures (HG), Silver / Gold Ratio (SI/GC), and CME Bitcoin Futures.
Currencies = US Dollar Index (DXY), Australian Dollar / US Dollar (AUDUSD), British Pound / US Dollar (GBPUSD), and Euro / US Dollar (EURUSD).
Each market signal is derived independently using either a volatility-adjusted moving-average crossover, a volatility-based adaptive trailing stop, or a combination of both. The signals are then aggregated and normalized into percentage scores representing each regime’s share of total signals, with optional smoothing over the specified signal length to reduce noise. The regime receiving the greatest confirmation across global markets is identified as the dominant macro regime and translated into portfolio preferences displayed in the regime preference table:
Goldilocks Preferences = Risk-On > Risk-Off, High Beta > Low Beta, Cyclicals > Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates > Long Rates, Spreads > Treasuries, High Yield > Low Yield, Beta FX > US Dollar, Metals > Energy, and Bitcoin > Gold.
Reflation Preferences = Risk-On > Risk-Off, High Beta > Low Beta, Cyclicals > Defensives, International > US Equities, SMID Caps > Large Caps, Short Rates > Long Rates, Spreads > Treasuries, High Yield > Low Yield, Beta FX > US Dollar, Metals > Energy, and Bitcoin > Gold.
Inflation Preferences = Risk-On < Risk-Off, High Beta < Low Beta, Cyclicals < Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates > Long Rates, Spreads < Treasuries, High Yield < Low Yield, Beta FX < US Dollar, Metals < Energy, and Bitcoin < Gold.
Deflation Preferences = Risk-On < Risk-Off, High Beta < Low Beta, Cyclicals < Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates < Long Rates, Spreads < Treasuries, High Yield < Low Yield, Beta FX < US Dollar, Metals > Energy, and Bitcoin < Gold.
The model further translates these portfolio preferences into specific exposures across equities, fixed income, commodities, and currencies. The selected exposures have been systematically backtested across the four macro regimes, dating back as far as January 1996, to identify those exhibiting the strongest risk-adjusted performance and most consistent directionally aligned trending behavior within each asset class. The resulting exposure lists provide a more granular view of the model’s broader portfolio preferences based on historically observed relationships:
Goldilocks Exposures = Equity sectors include Communication Services (XLC), Technology (XLK), Financials (XLF), Industrials (XLI), Consumer Discretionary (XLY), Materials (XLB), and Real Estate (VNQ). Equity factors include S&P 500 (SPY), Nasdaq 100 (QQQ), High Beta (SPHB), Momentum (MTUM), Quality (QUAL), Growth (IWF), and Value (IWD). Fixed income includes High Yield Bonds (HYG), Investment Grade Bonds (LQD), and Convertible Bonds (CWB). Commodities include Bitcoin (BTC), Industrial Metals (DBB), Metal Producers (PICK), Gold (GLD), Gold Miners (GDX), Silver (SLV), Silver Miners (SIL), Copper (CPER), Copper Miners (COPX), Uranium (SRUUF), and Uranium Miners (URNM). Currencies include Australian Dollar (FXA), British Pound (FXB), and Euro (FXE).
Reflation Exposures = Equity sectors include Energy (XLE), Communication Services (XLC), Technology (XLK), Financials (XLF), Industrials (XLI), Consumer Discretionary (XLY), Materials (XLB), and Real Estate (VNQ). Equity factors include Global Equities (ACWI), International Equities (ACWX), S&P 500 (SPY), Nasdaq 100 (QQQ), Emerging Markets (EEM), High Beta (SPHB), Mid Caps (IWR), Small Caps (IWM), Momentum (MTUM), Quality (QUAL), Growth (IWF), Value (IWD), Equal Weight (RSP), Global Infrastructure (IGF), and International Real Estate (IFGL). Fixed income includes High Yield Bonds (HYG), Convertible Bonds (CWB), Private Credit (BIZD), and Emerging Market Bonds (EMB). Commodities include Bitcoin (BTC), Commodities (DBC), Industrial Metals (DBB), Metal Producers (PICK), Crude Oil (USO), Agriculture (DBA), Agriculture Producers (VEGI), Gold (GLD), Gold Miners (GDX), Silver (SLV), Silver Miners (SIL), Copper (CPER), Copper Miners (COPX), Uranium (SRUUF), and Uranium Miners (URNM). Currencies include Australian Dollar (FXA), Canadian Dollar (FXC), British Pound (FXB), and Euro (FXE).
Inflation Exposures = Equity sectors include Energy (XLE), Consumer Staples (XLP), Utilities (XLU), and Health Care (XLV). Equity factors include Low Volatility (SPLV). Fixed income includes 1-3 Month Treasury Bills (BIL). Commodities include Commodities (DBC), Crude Oil (USO), Agriculture (DBA), and Gold (GLD). Currencies include US Dollar (UUP).
Deflation Exposures = Equity sectors include Consumer Staples (XLP), Utilities (XLU), and Health Care (XLV). Equity factors include Low Volatility (SPLV) and High Dividend (SPHD). Fixed income includes 1-3 Year Treasuries (SHY), 7-10 Year Treasuries (IEF), 20+ Year Treasuries (TLT), US Aggregate Bonds (AGG), Mortgage-Backed Securities (MBB), and International Aggregate Bonds (BNDX). Commodities include Gold (GLD). Currencies include US Dollar (UUP) and Japanese Yen (FXY).
The model includes a built-in alert system that notifies investors in real time when the dominant macro regime changes and provides the corresponding exposures for the new regime. It also features an integrated backtesting engine that can be enabled in the menu to evaluate asset performance across the macro regimes. Users can assign an asset to each regime, with the backtest automatically rotating into the corresponding asset whenever that regime becomes dominant. If one or more assets are assigned, any unassigned regimes are treated as cash. If no assets are assigned, the chart ticker is assigned to Goldilocks and Reflation, while Inflation and Deflation are treated as cash. The backtest reports the following performance metrics:
CAGR = Compounded Annual Growth Rate.
Excess = CAGR in excess of buy-and-hold.
Sharpe = CAGR per unit of standard deviation.
Sortino = CAGR per unit of downside deviation.
Calmar = CAGR relative to maximum drawdown.
Max DD = Largest peak-to-trough decline in value.
Alpha (α) = Excess annualized risk-adjusted returns.
Win Rate = Ratio of profitable trades to total trades.
Profit Factor = Total gross profit per unit of losses.
Expectancy = Average expected return per trade.
Turnover = Average annualized change in exposure.
The indicator is designed with flexibility in mind, allowing users to select the backtest period, signal methodology, preferred trend type, volatility type, and the individual markets included in the regime calculation. Supported moving-average types include the Exponential Moving Average (EMA), Simple Moving Average (SMA), Wilder’s Moving Average (RMA), and Weighted Moving Average (WMA). Supported volatility types include the Average True Range (ATR), Standard Deviation (SD), and Mean Absolute Deviation (MAD). The table follows an intuitive color-coded logic that allows for quick performance comparison against buy-and-hold (B&H):
CAGR = Green indicates above 0%, while red indicates below 0%.
Excess = Green indicates above 0%, while red indicates below 0%.
Sharpe = Green indicates better than B&H, while red indicates worse.
Sortino = Green indicates better than B&H, while red indicates worse.
Calmar = Green indicates better than B&H, while red indicates worse.
Max DD = Green indicates better than B&H, while red indicates worse.
Alpha (α) = Green indicates above 0%, while red indicates below 0%.
Win Rate = Green indicates above 50%, while red indicates below 50%.
Profit Factor = Green indicates above 2, while red indicates below 1.
Expectancy = Green indicates above 0%, while red indicates below 0%.
In summary, the Global Macro Regime is a comprehensive market-based macro framework designed to identify the prevailing macro regime. By combining 30 independent cross-asset market signals, the model translates the dominant macro regime into portfolio preferences and regime-specific exposures based on historical relationships that may not persist under future market conditions as market dynamics and asset-specific characteristics evolve over time. Historical coverage also varies across the 30 selected markets, with regime signals prior to 2006 based on progressively fewer markets and therefore requiring more cautious interpretation. 指標

Keltner Rings [Quantum Algo]Keltner Rings
═══════════════════════════════════════════════
🔶 OVERVIEW
Keltner Rings is a complete reading system built on Keltner Channels — volatility bands placed around an exponential moving average, with width set by the Average True Range. Three nested rings form a gradient volatility field around price, a regime classifier determines what kind of market you are actually in, and the dashboard translates it into plain instructions: when riding the upper band is strength, and when the very same touch is fade material.
That distinction is the heart of this tool. The most common way traders lose money with any channel indicator is applying range logic in a trend — shorting an upper-band touch while price is band-walking higher. Keltner Rings classifies the regime first, interprets every touch accordingly, generates three distinct signal families, and scores each family's historical performance on your exact symbol and timeframe.
═══════════════════════════════════════════════
🔶 WHAT ARE KELTNER CHANNELS?
Keltner Channels are volatility-based bands around a moving average. The concept originates with Chester W. Keltner (1960); the modern formulation — an exponential moving average with bands offset by multiples of the Average True Range — was popularized by Linda Bradford Raschke. Because the Average True Range expands and contracts with real movement, the channel breathes with the market: wide in storms, tight in calm.
This tool extends the classic single channel into three rings — inner, middle and outer — creating a graded map of how far price has traveled from its average in volatility-adjusted terms.
═══════════════════════════════════════════════
🔶 WHAT IS A BAND WALK?
In a genuine trend, price does not oscillate politely around its average — it presses against the channel and rides it, closing beyond the inner ring bar after bar. This is the band walk, and it is the single most misread behavior in channel trading: it looks overbought, and it is actually strength. Keltner Rings detects the walk explicitly (a configurable count of consecutive closes beyond the inner ring), paints the walking bars in full trend color, and marks the walk's beginning as a continuation signal rather than a fade.
═══════════════════════════════════════════════
🔶 WHY IS THIS ORIGINAL?
1. Regime-aware interpretation. The classifier combines average slope, band-walk state, squeeze condition and the channel's own width percentile into four regimes — Trend Up, Trend Down, Range, Squeeze — and the dashboard's "How To Read It" row states, live, how touches should be interpreted right now. The tool teaches its own correct usage.
2. Three signal families, separated on purpose. W marks the start of a band walk with the trend (continuation). R marks a middle-ring rejection in a range regime only (reversion, exactly where reversion belongs). S marks a squeeze release through the inner ring (expansion). One tool, three behaviors, never confused with each other.
3. Per-family statistics on your chart. Every family's ten-bar outcomes are tracked in first-in-first-out samples, shrunk toward neutral at small sizes, with Wilson lower bounds. Each signal's tooltip quotes its own family record on the current symbol at the moment it prints — and the dashboard shows all three records side by side.
4. The width cone. Channel width is ranked as a percentile inside its own recent history, so "tight" and "wide" are defined by this symbol's behavior, never by fixed numbers.
5. The squeeze, credited and integrated. Bollinger Bands closing inside the Keltner ring — the compression concept popularized by John F. Carter — is detected with duration tracking, gold coil markers on the average, and directional release signals.
═══════════════════════════════════════════════
🔶 HOW IT WORKS
— The exponential average and Average True Range build three rings at configurable widths; five gradient fills render the volatility field between them.
— Average slope, walk counters, squeeze state and width percentile feed the regime classifier every bar.
— Signals: W fires when the walk count is reached with the trend; R fires on middle-ring rejections in range regimes; S fires when a mature squeeze releases through the inner ring.
— Each family's outcomes feed its own statistics; the dashboard and tooltips report them with sample counts.
All signals are evaluated on confirmed bars and do not repaint. All drawings are capped for performance.
═══════════════════════════════════════════════
🔶 HOW TO USE IT
— Read the regime row first, then the guidance row — they tell you which of the three signal families is currently in its natural habitat.
— In trends: treat inner-ring pullbacks as entries in the trend direction, and let the painted band walk carry the position; the walk ending is your first warning.
— In ranges: middle-ring touches with rejection candles target the average — the R family's record shows how this symbol has respected that logic.
— In squeezes: the coil duration and width percentile tell you how compressed the spring is; the S release gives the direction, and the family record tells you how trustworthy releases have been here.
— Works on all markets and timeframes; every threshold is volatility-adjusted or percentile-based, so nothing needs retuning per symbol.
═══════════════════════════════════════════════
🔶 SETTINGS
— Keltner Channels: exponential average length, Average True Range length, three ring widths.
— Regime & Signals: trend slope threshold, band-walk bar count, width history window, cooldown, squeeze ring width.
— Statistics: sample cap, minimum samples, shrinkage strength, Wilson z-score.
— Visuals and dashboard: full color control, band-walk painting toggle, position and text size.
═══════════════════════════════════════════════
🔶 ALERTS
— Squeeze Started — compression began.
— Squeeze Release Up / Down — compression resolved through the inner ring.
— Band Walk Started — consecutive closes locked beyond the inner ring with the trend.
— Reversion Signal — middle-ring rejection in a range regime.
═══════════════════════════════════════════════
🔶 FAQ
Q: How is this different from standard Keltner Channels?
A: The standard indicator draws one channel and leaves interpretation to you — including the fatal ambiguity of what an upper-band touch means. This tool adds the regime classifier, the three-ring field, the band-walk engine, explicit signal families for continuation, reversion and expansion, and per-family statistics, so every touch arrives with its context and its track record.
Q: Does it repaint?
A: No. All signals are evaluated on confirmed closes; a printed signal never changes.
Q: Keltner Channels or Bollinger Bands?
A: They answer different questions. Bollinger Bands use standard deviation and react sharply to close-to-close variance; Keltner Channels use the Average True Range and breathe more smoothly with the full bar range. This tool uses both — the channel as the structure, and the Bollinger relationship as the squeeze detector.
Q: What do the family percentages mean?
A: The share of past signals in that family after which price had moved favorably ten bars later, on the current symbol and timeframe, shrunk toward fifty percent at small samples. They describe history — they are not predictions.
Q: Which settings matter most?
A: Band Walk Bars (higher = stricter walks, fewer W signals) and the ring widths — the defaults of one, two and three Average True Ranges follow common practice and suit most markets.
═══════════════════════════════════════════════
🔶 CREDITS
The original channel concept is by Chester W. Keltner (1960); the modern exponential-average and Average True Range formulation was popularized by Linda Bradford Raschke. The Average True Range is by J. Welles Wilder Jr. (1978). Bollinger Bands are by John Bollinger, and the band-compression squeeze concept was popularized by John F. Carter. The Wilson score interval is by Edwin B. Wilson (1927). The regime classifier, three-ring field, band-walk engine, signal families, per-symbol statistics and all code in this script are original work — no third-party or open-source script code was reused.
═══════════════════════════════════════════════
🔶 LIMITATIONS
— Regime classification is descriptive, not predictive: regimes are identified as they form, and transitions are only visible once underway.
— Reversion logic is disabled by design outside range regimes; traders who want to fade trends will not find those signals here.
— Statistics describe the current chart's history only; past frequencies never guarantee future outcomes.
═══════════════════════════════════════════════
🔶 DISCLAIMER
This indicator is a research and charting tool provided for educational purposes. It is not financial advice, and nothing it displays is a recommendation to buy or sell any asset. Trading involves substantial risk of loss. Always do your own analysis and manage risk responsibly. 指標

Volatility Regime Range Map [AFD]Two stretches of the same chart can look alike and be nothing alike — one the quietest tape in months, the other the widest swings all year.
Volatility Regime Range Map tells them apart on sight: it sorts every bar into one of four volatility regimes — QUIET, NORMAL, ELEVATED, EXTREME — and draws each unbroken stretch as a colored box on price. The calm and the turbulent history of your chart read at a glance instead of bar by bar.
What it does
At a glance it names which of four volatility regimes the current stretch belongs to, and how it compares with the chart's own recent history.
Regime episodes as boxes. Each unbroken stretch of one regime is a box spanning the bars it covered and the price range it reached. The current box glows and extends while the regime holds; recent finished episodes stay as faint boxes behind it — a map of which stretches were quiet and which were turbulent.
A regime ranked over calendar time. Each bar's volatility is ranked as a percentile against a rolling calendar window (default 6 months), so a regime means the same span of history on a 5-minute chart or a daily one — whether the tape is calmer, wider, or about the same as this symbol usually runs.
Higher-timeframe frames. The same engine on one or two higher timeframes, drawn as outline frames — HTF 1 dashed, HTF 2 dotted (default 1 month and 1 week) — each labelled with its timeframe and regime, so the broader context is on the same screen without switching charts.
Optional dashboard. Off by default. When on, it shows the current regime, the episode's age and price range, where those rank among finished episodes, and the sample behind the ranking.
A standing note in the Data Window — "Volatility-regime episodes · describes chart history · not a forecast" — that is always on.
Every one of those is a measurement of chart history. It reports what volatility has been; it does not tell you what price will do next or how long a regime will last.
How it works
Parkinson
Garman-Klass
Estimator. Parkinson (default), Close-to-close, Garman-Klass, or ATR — the one you pick measures every regime on the chart.
Percentile to tier, with hysteresis. The reading maps to a tier at the 25th, 75th and 85th percentiles, through a small hysteresis band so the regime does not flip on one borderline bar. QUIET below 25, NORMAL 25–75, ELEVATED 75–85, EXTREME 85 and above.
An optional second route into EXTREME. Flags EXTREME when the short window reaches a set multiple of the long one — also while the window is still gathering enough history to rank.
Confirmed bars only, no redraw. Regimes update on confirmed bars. A new box opens at the bar where the regime changes; once a box or a frame is drawn, later bars do not move it or recolour it.
The higher-timeframe frames use request.security to read each timeframe's most recently confirmed regime.
How to use it
Add it to any chart and timeframe. The defaults are the intended reading: Parkinson, Fast (5/30), a 6-month lookback, frames on (1M dashed + 1W dotted), dashboard off. Remove and re-add once so it draws in front of the candles.
Read the boxes first — the colour names the regime you are in, and the height is the price range that stretch covered.
Use the dashed and dotted frames to see the weekly and monthly regime on the chart you are trading.
Turn on the dashboard for the current episode's age and range in numbers, and where they rank.
Change the comparison lookback to widen or narrow the window a regime is judged against.
What it deliberately does not do
Every number is measured from this chart's own price history — nothing is implied, expected, or projected forward.
No alerts, no signals, no entries or exits.
No statement about what price will do next, or how long a regime will last.
Counts and percentiles stay descriptions of this chart's history — never converted into odds.
The regime names are labels for measured tiers, not ratings, scores, or predictions.
Why it is original
Most volatility tools hand you a line (ATR, standard deviation) or a band. This one segments the history into regime episodes and draws each as a box you can take in at a glance, ranks the regime over a rolling calendar window so it means the same across timeframes, and can stack one or two higher timeframes as nested frames on the chart. The classifier is the engine from the author's Volatility Regime Classifier, re-expressed here as an on-price map ranked over calendar time.
Open source under the Mozilla Public License 2.0. Native Pine v6; the optional higher-timeframe frames read the regime on higher timeframes via request.security, and nothing uses external data. 指標

Volume Tide [JOAT]Reads participation like an ocean tide — from drained to institutional surge — and carves volume-weighted zones during the bursts.
◆ WHAT IT IS
Volume Tide reframes volume as a tide : it measures how strongly current participation is running against its own long-term baseline and classifies the market into four intuitive states. It is a pure market-context tool — it maps where real activity is entering the market and builds structure from it. It does not print buy/sell signals.
This is 100% original code, written from scratch. It is not a repackaged volume oscillator.
◆ HOW IT WORKS
1. The tide ratio. A short-term volume average is divided by a long-term baseline. This ratio — incoming wave versus sea level — tells you whether participation is expanding or draining, independent of the raw volume scale of the symbol.
2. Four tide states. The ratio is banded into:
• EBB — participation drained out
• RISING — filling back up
• FLOOD — active participation
• SURGE — institutional-scale bursts
All four are painted as a seamless aquatic gradient in the lower pane.
3. Tide pools. When a SURGE begins, the tool carves a tide pool onto the price chart across the traded range. As price continues to trade inside that pool, it accumulates volume by price overlap and computes:
• a volume-weighted anchor line (a natural magnet level), and
• a live buy/sell pressure split with a total-volume readout.
◆ WHAT YOU SEE
• A gradient tide histogram with Ebb / Flood / Surge threshold guides
• Tide pools on the price chart during surges, each with a volume-weighted anchor and live buy/sell delta stats
• A resizable dashboard showing the tide state and direction (coming in / going out), the tide ratio with a wave meter, fast-versus-baseline volume, live pool count, the newest pool's volume and delta, and surge history
◆ HOW TO USE IT
• Use the tide state as a conviction filter : breakouts and trends that develop during FLOOD or SURGE have real participation behind them, while moves during EBB are thin and prone to reversal.
• The volume-weighted anchor inside a tide pool often acts as support/resistance when price returns to it.
• The buy/sell delta inside a pool shows which side did the heavy lifting during the surge.
• Works on all symbols and timeframes that provide volume.
◆ NOTES & LIMITATIONS
Volume Tide requires a genuine volume feed — on symbols without one the tide ratio is not meaningful. It describes participation conditions and structure; it is not financial advice and does not predict direction on its own. Use it alongside a directional method and your own risk management.
— made with passion by officialjackofalltrade
指標

ICT Everything v2ICT Everything v2 is an open-source intraday charting toolkit for ICT-style time, liquidity, and displacement analysis.
The script combines related tools in one chart workflow. Sessions identify relevant trading windows, opening prices and prior-period levels provide liquidity context, gaps mark displacement areas, and SMT compares confirmed swings with a correlated market.
What it shows
London, New York, London Close, afternoon, Asia, and custom sessions
Midnight, New York, equities, afternoon, weekly, and monthly opening prices
CBDR, FLOUT, and Asia ranges with configurable standard-deviation extensions
Fair Value Gaps with consequent encroachment and fill handling
New Week and New Day Opening Gaps with optional midpoint lines
Previous week and previous month highs and lows
Confirmed-pivot SMT divergence against a comparison symbol
Day separators, day labels, session boxes, and selected confirmed-bar alerts
Why these tools are combined
The components share the same session and timezone context. This avoids building a chart from several unrelated scripts that may use different boundary definitions.
Sessions establish when activity occurs. Opening prices and prior-period levels mark reference liquidity. FVG, NWOG, and NDOG objects show displacement and reopening gaps. SMT adds relative-strength context by comparing the chart symbol with a correlated instrument over the same swing window.
This is a charting toolkit, not an entry system or strategy.
How to use it
The default configuration is intended for intraday charts. The script hides its drawings above a configurable ceiling, which defaults to 31 minutes.
The default timezone is New York and follows daylight-saving time automatically. Fixed UTC offsets are also available.
Most added modules are disabled by default. Enable only the features needed for the current analysis. Weekly and monthly opens, prior-period levels, FVGs, opening gaps, SMT, and session boxes can be enabled independently.
For SMT, select a positively correlated comparison symbol with similar trading hours. For example, NQ and ES generally provide cleaner comparisons than instruments with unrelated sessions.
Alerts use confirmed bars. TradingView alerts store the script version and settings that existed when the alert was created, so alerts should be recreated after a script update.
Boundary behavior
Continuous futures use locally captured evening-session boundaries for weekly and monthly opens. Crypto uses the standard UTC calendar boundaries: Monday 00:00 UTC for the week and the first day at 00:00 UTC for the month.
Broker sessions can differ, so users should verify opening levels against the instrument and feed they trade.
Meaningful changes in v2
The retained session and range foundation from the original script is credited below. V2 materially changes and extends that foundation with:
Pine Script v6 support
DST-aware New York session handling and additional timezone options
Reworked weekly and monthly boundaries for futures and crypto
Mechanical FVG, NWOG, and NDOG modules with bounded object retention
Previous week and month high/low tracking
Confirmed-pivot SMT using a same-window comparison method
Session-box and high-low rendering modes
Independent deviation counts for CBDR, FLOUT, and Asia
Confirmed-bar alerts for range breaks, gaps, and prior-period sweeps
Drawing cleanup and redraw changes that prevent stale objects and reduce unnecessary recalculation work
Open-source origin and credit
Based on ICT Everything by coldbrewrosh, formerly itsroshlol:
Contains code from ArdOfCrypto's ICT Index Futures Vertical Lines:
The original publication credited Shanxia as inspiration and thanked I_Am_ICT. Those acknowledgements are preserved.
This is an independently maintained derivative work. The credited authors do not endorse this publication. The source is published openly under the Mozilla Public License 2.0.
Limitations
This script does not predict market direction or promise trading performance. SMT depends on the selected comparison instrument and its available trading hours. Fixed-offset session choices do not adjust for daylight-saving time. Users remain responsible for confirming that the configured sessions match their market and data feed.
This publication is not affiliated with or endorsed by Inner Circle Trader, TradingView, or the credited authors. 指標

NRTR Adaptive Trailing Reverse [MarkitTick]💡 An adaptive trailing-stop and reversal system built around the Nick Rypock Trailing Reverse (NRTR) algorithm, extended with a configurable smoothing engine, ADX confluence filtering, automatic risk-based trade level projection, and a live position-sizing dashboard. Rather than applying NRTR to raw closing price, this tool lets the trailing calculation run on top of one of eight selectable smoothing methods, giving traders control over how reactive or how filtered the underlying trend estimate is before the trailing stop is derived from it.
✨ Originality and Utility
The classic NRTR trailing stop is normally computed directly from price. This script decouples the "source" the trailing calculation reacts to from raw price by routing it through a selectable adaptive filter stage first — SMA, EMA, RMA, Double WMA, Triple VWMA, HMA, a custom LLAMA slope-projection filter, or a Kalman filter. This means the trailing envelope itself can be smoothed, decoupled from tick-level noise, or shaped to lag less than a conventional moving average, without changing the core NRTR ratchet-and-flip mechanic.
Beyond the trailing engine, the script closes the loop between "signal" and "trade management," which most trailing-stop tools leave to the user. Once a trend flip is confirmed, it automatically derives a stop-loss from the NRTR level itself and projects three risk-multiple take-profit targets, tracks whether each has been hit, calculates a suggested position size from a risk percentage or fixed-dollar risk model, and optionally suppresses new signals for a cooldown period after a stop-out. An ADX confluence filter can additionally require a minimum trend strength reading before a flip is treated as valid. The combination is justified because each component consumes the output of the one before it: the adaptive filter conditions the source, the NRTR logic converts that source into a trailing stop and flip signal, the ADX filter validates the flip's context, and the risk/sizing engine turns the validated flip into an actionable, fully quantified trade plan — a single coherent pipeline rather than an arbitrary bundling of unrelated indicators.
🔬 Methodology and Concepts
• The Adaptive Source Filter
Before any trailing-stop math happens, closing price is optionally passed through one of these transformations, selected from the "Adapt Filter" input:
SMA / EMA / RMA — standard moving averages, included as familiar baselines.
Double WMA — a Weighted Moving Average applied twice in succession (a WMA of a WMA), which produces a lower-lag response than a single WMA of the same length.
Triple VWMA — a Volume Weighted Moving Average cascaded three times, folding volume-weighting into a lower-lag smoothing chain.
HMA — the Hull Moving Average, using weighted-moving-average differencing to reduce lag relative to standard smoothing.
LLAMA — a proprietary two-part filter that combines a simple moving average of the source with a linear slope term measured over the same lookback (the rate of change between the current source value and the value from `length` bars ago, divided by `length`). The slope is scaled by half the filter length and added to the SMA, producing a trend-projected estimate that leans ahead of a plain average in the direction of the recent slope.
Kalman Filter — a lightweight recursive estimator that updates a running estimate of the "true" price using a prediction/correction cycle. It maintains an internal error estimate and a gain term derived from the ratio of process noise (set by the inverse of the filter length) to measurement noise, blending each new price observation into the estimate proportionally to that gain.
None — the trailing logic operates directly on closing price.
When "None" is selected, the tool behaves as a standard price-based NRTR. Any other selection substitutes that smoothed series as the "source" for every downstream calculation.
• NRTR Trailing Calculation
The script offers two modes for sizing the trailing offset, chosen via "NRTR Mode":
Percent — the offset is a fixed percentage of the (lagged) adaptive source value.
ATR — the offset is a multiple of the Average True Range over a configurable lookback, scaling the trailing distance to current volatility rather than a fixed percentage.
In an uptrend, the script tracks the highest adaptive-source value reached since the last flip (the "extreme") and subtracts the offset from it to produce a trailing level that can only rise or stay flat — never fall — while the trend persists. In a downtrend, the mirror logic tracks the lowest extreme and adds the offset, producing a level that can only fall or stay flat. A trend flip occurs the moment the prior bar's adaptive source closes beyond the trailing level: closing below it in an uptrend flips the state to a downtrend (and vice versa), at which point the extreme and trailing level reset and begin tracking in the new direction. Because the ratchet only ever tightens toward price, this produces the classic NRTR "stair-step" trailing behavior rather than a smooth curve.
• Confirmation and Non-Repainting Behavior
The trend-state comparison that triggers a flip always references the previous bar's confirmed adaptive-source value, and every alert condition is additionally gated behind `barstate.isconfirmed`. This means a signal only fires once its triggering bar has fully closed — the trailing level and trend state do not repaint once a bar is confirmed, and alerts cannot fire prematurely intrabar.
• ADX Confluence Filter
When enabled, a flip is only accepted as a valid trading signal if the prior bar's ADX reading (calculated over the same configurable length for both DI and ADX smoothing) is at or above the threshold input. This is intended to suppress flips that occur while the market lacks directional strength, where trailing-stop whipsaws are most common.
• Cooldown Guard
When enabled, a stop-loss hit on one side of the market starts a bar-count cooldown during which a new signal in that same direction is suppressed, intended to reduce immediate re-entry into a level that has just failed.
• Trade Level Projection and Position Sizing
On a valid signal, the entry is taken at the current close, the stop-loss is set to the NRTR trailing level at that moment, and the initial risk distance (entry-to-stop) is multiplied by three independently configurable multiples to project TP1, TP2, and TP3. Each target and the stop are tracked bar-by-bar for whether price has traded through them, updating their on-chart labels accordingly. A suggested position size is calculated from either a percentage of a user-defined account size or a fixed dollar risk amount, divided by the entry-to-stop distance in price, giving a size that risks a consistent dollar or percentage amount regardless of current volatility.
🎨 Visual Guide
NRTR Line — a grey step-line plotting the current trailing-stop level.
Heatmap Candles — the chart's candles are recolored using the Bull/Bear color inputs (teal/red by default) to reflect the current trend state directly on price, rather than requiring a separate indicator pane.
Cooldown Background — a shaded background tint appears while a directional cooldown is active after a stop-out, using the Cooldown BG color.
Trade Level Lines and Labels (on signal) — a solid red Stop Loss line, a dashed blue Entry line, and three dashed green Take Profit lines (TP1 lightest, TP3 most opaque) extend from the signal bar. Each carries a right-aligned label showing its exact price; once a target or stop is touched, its label updates in place to show the hit and the resulting percentage gain or loss from entry.
Risk/Reward Shading — a light red fill shades the zone between Entry and Stop Loss (the risk side), and a light green fill shades the zone between Entry and TP3 (the full reward side), giving an immediate visual sense of the trade's risk-to-reward geometry.
Dashboard Table — a corner-anchored panel (position configurable) summarizing, in real time: current trend direction, Lock status, the live NRTR level, active entry/stop/TP1 prices, the current ADX reading (colored by pass/fail against the threshold), the active adaptive filter, cooldown status and remaining bars, the calculated risk amount, the suggested position size, and a filled bar-graph showing how close price currently sits to the trailing stop as a percentage of the total offset distance.
📖 How to Use
A flip from red to teal candles (and the NRTR line stepping below price) signals a potential long entry; the mirror flip signals a potential short.
Use the auto-drawn Entry, Stop Loss, and Take Profit lines as a starting risk/reward framework — the SL is anchored to the trailing level at the moment of the flip, not an arbitrary distance.
Enable the ADX Filter if you want flips confirmed only during periods of measurable trend strength, which reduces (but does not eliminate) signals generated in choppy, low-ADX conditions.
Enable Cooldown Guard if you want to avoid immediate re-entry into a direction that was just stopped out — useful in ranging conditions prone to repeated whipsaws.
Enable Lock Signal to freeze the currently displayed trade levels in place (rather than having them update to the latest signal), useful for reviewing a specific historical setup without it being overwritten by newer signals.
Watch the "Dist Trail" bar in the dashboard as a quick visual read of how far price currently sits from the trailing stop relative to the configured offset — a nearly full bar means price is close to triggering a flip.
The built-in alert payloads are formatted as JSON and include action, ticker, timeframe, direction, entry, stop, and target fields, making them usable directly as webhook bodies for external automation without additional parsing.
⚙️ Inputs and Settings
NRTR Mode — switches the trailing offset calculation between a fixed Percent of price and a volatility-adaptive ATR multiple.
NRTR % / ATR Len / ATR Mult — control the magnitude of the trailing offset in each respective mode; larger values produce a looser trail with fewer, later flips, smaller values produce a tighter trail with more frequent flips.
Use ADX Filter / ADX Len / ADX Thresh — toggle and configure the trend-strength confluence filter described above.
Adapt Filter / Adapt Len — select the smoothing method applied to price before the NRTR calculation, and its lookback length.
Cooldown Guard / Cooldown Bars — toggle and configure the post-stop-out re-entry suppression window.
Lock Signal — freezes the currently plotted trade levels rather than letting them advance to the newest signal.
Position Sizing / Sizing Mode / Risk % Trade / Fixed Risk $ / Account $ — configure whether suggested size is derived from a percentage of account equity or a fixed dollar risk figure, and the inputs feeding that calculation.
TP1/TP2/TP3 Mult — the risk multiples applied to the entry-to-stop distance to project each take-profit level.
Heatmap Candles / NRTR Line / Trade Levels — independently toggle each visual layer on or off.
Dash Pos / Show Dash — position and visibility of the dashboard table.
Alert Action fields (Long/Short/Close Long/Close Short) — customize the "action" string embedded in each webhook JSON payload, useful for matching the field names expected by a specific external automation system.
Color inputs — independently customize every plotted and dashboard color.
🔍 Deconstruction of the Underlying Scientific and Academic Framework
The NRTR mechanic itself belongs to a family of stop-and-reverse trailing systems related conceptually to Wilder's Parabolic SAR and to chandelier-style trailing stops: all three share the property that the trailing level is a one-directional ratchet — it can only move in the direction that tightens toward price — which is what mechanically prevents the trailing stop from ever "giving back" more than the configured offset once a trend is underway. Where NRTR differs is in decoupling the ratchet from a fixed acceleration curve (as in Parabolic SAR) and instead deriving it directly from a percentage or volatility-scaled offset off a tracked local extreme, which is closer in spirit to a Donchian- or Chandelier-style trailing construction.
The ATR-based offset mode draws on Welles Wilder's concept of using recent true-range volatility, rather than a fixed percentage, to size a trailing distance — the rationale being that a constant percentage offset is too tight in high-volatility regimes (generating premature stop-outs) and too loose in low-volatility regimes (giving back excess profit), while an ATR-scaled offset expands and contracts with the instrument's own recent behavior.
The Double WMA and Triple VWMA filters are cascaded-smoothing constructions in the same family as Hull's differencing approach: repeatedly passing a series through a weighted average and recombining the outputs is a general technique for pushing a smoothing filter's group delay down without simply shortening its lookback (which would otherwise increase noise sensitivity). The Kalman filter option applies a simplified, single-state version of the classic recursive Bayesian estimator from control theory, where each new observation is blended into a running estimate according to a gain term balancing assumed process noise against assumed measurement noise — conceptually the same estimation framework used in tracking and signal-processing applications outside of finance. The custom LLAMA filter combines a central-tendency estimate (a simple moving average) with a first-order trend term (a discrete slope measured over the same window), an approach related in principle to linear trend-projection and regression-based smoothing techniques that attempt to reduce lag by explicitly modeling the direction a series is moving rather than only its recent average level.
The ADX component derives from Wilder's Directional Movement System, in which ADX quantifies the strength (not direction) of a trend by smoothing the divergence between positive and negative directional movement — using it as a confluence filter reflects the broader technical-analysis principle that trend-following and trailing-stop methods perform better in the specific market regime (trending, directional) they are designed for, and using a strength filter is one common approach to distinguishing that regime from a ranging one.
⚠️ Disclaimer
All provided scripts and indicators are strictly for educational exploration and must not be interpreted as financial advice or a recommendation to execute trades. We expressly disclaim all liability for any financial losses or damages that may result, directly or indirectly, from the reliance on or application of these tools. Market participation carries inherent risk where past performance never guarantees future returns, leaving all investment decisions and due diligence solely at your own discretion. 指標

指標

Dynamic Opening Drive Scoreboard v4.4.2Dynamic Opening Drive Scoreboard v4.4.2
Short Description
Intraday long opening-drive dashboard using 9 EMA, VWAP, RVOL, trigger/entry logic, hybrid stop references, freshness tracking, and trade-state guidance.
Full Description
Dynamic Opening Drive Scoreboard is an intraday momentum dashboard built for traders focused on long opening-drive setups.
It is designed to help you quickly determine whether a stock is:
setting up for a long
approaching a trigger
confirming a breakout
still fresh after entry
becoming extended
showing weakness
Unlike a static trade tracker, this indicator uses a scan-first, freshness-aware framework so the board stays focused on what is relevant right now.
How the setup works
This version is built around a long opening-drive continuation setup.
Basic long criteria
price above the 9 EMA
price above VWAP
minimum setup RVOL met
When those conditions are met, the setup candle close is recorded.
Trigger
trigger is set above the setup candle close
trigger = setup close + trigger buffer
Entry confirmation
price breaks the trigger
minimum entry RVOL is met
optional increasing-volume confirmation is satisfied, if enabled
Stops The board shows two stop references:
Structure Stop = below the Low of Day
ATR Stop = a practical volatility-based reference
The structure stop represents where the setup would be invalidated. The ATR stop provides a tighter practical risk reference for planning and trade management.
How to read the board
Price / LOD
Shows current price and the Low of Day, which acts as the key structural reference for invalidation.
9 EMA
Shows whether price is above or below the 9 EMA, plus the % distance from it.
VWAP
Shows whether price is above or below VWAP, plus the % distance from it.
Setup / T-E
Shows the current setup close together with either:
Trig = breakout trigger level
Ent = confirmed entry price
Stops / Risks
Shows:
structure stop and its dollar risk
ATR stop and its dollar risk
This helps compare the true structural invalidation level with a tighter active-risk reference.
Risk Q
Rates current risk as:
Tight
Good
Acceptable
Wide
Vol Conf
Shows whether current bar volume is increasing when the volume confirmation filter is enabled.
Bar / Avg Vol
Shows current bar volume compared with average volume.
RVOL / Req
Shows:
current relative volume
minimum RVOL required for setup and entry
Range / %
Shows:
current bar range
current bar range as a percentage
whether expansion is normal, wide, or very wide
Freshness
Shows:
bars since setup
bars since entry
This helps prevent chasing stale setups or old breakouts.
State
Summarizes the current chart context in one line, including:
mode
state
suggested action
current
𝑅
R multiple when in a trade
How to use the % distance from the 9 EMA and VWAP
The % distance from the 9 EMA and VWAP is especially useful after entry because it helps measure how stretched the move is becoming relative to its intraday support structure.
A practical way to use it:
smaller positive distances often suggest the move is still relatively orderly
expanding positive distances can show momentum building
large positive distances from both the 9 EMA and VWAP can indicate increasing extension and a need for tighter management
In practice:
if price remains above both the 9 EMA and VWAP while the move expands in a controlled way, the trend may still be healthy
if price gets far above both reference levels, the trade may be entering a more extended or emotional phase
if price starts losing one or both of those levels after being highly extended, that can be an early sign of weakening momentum
These readings are also used internally to help classify conditions such as Extended and Possible Capitulation.
Trade-state framework
Once a trade is confirmed, the board can classify it into states such as:
Fresh Entry — breakout has just triggered
Base Hit — the trade has reached the defined base-hit
𝑅
R threshold
Runner Active — the move is still holding together after base hit
Possible Capitulation — price is very extended and may be entering a climax phase
Stalling / Weakness — structure or continuation quality is deteriorating
This allows the board to shift from finding the setup to helping manage the trade.
Optional overlay levels
The script can also plot key reference levels directly on the chart:
Trigger
Entry
Structure Stop
ATR Stop
Base-Hit Level
These overlays are intended to improve visual decision-making without changing the setup logic.
Best suited for
intraday momentum traders
opening-drive breakout traders
EMA + VWAP traders
volume-confirmation workflows
scanner follow-up
replay study and execution review
Notes
long-side version only
designed for intraday use
uses bar-based proxies such as volume, RVOL, and range
does not use Level 2, bid/ask, or spread data
intended as a decision-support tool, not financial advice
Enjoy!
Wayne 指標

指標

DISTANCE % PH-PL MTF Dashboard This is a very comprehensive Pine Script indicator for TradingView that creates a multi-timeframe (MTF) dashboard showing price distance from period highs (PH) and lows (PL), along with retracement levels and trade suggestions.
Here's a detailed breakdown of what this indicator does and how to use it:
Core Functionality
1. Multi-Timeframe Dashboard
Displays data for up to 10 customizable timeframes (1min, 3min, 5min, 15min, 60min, 120min, 240min, Daily, Weekly, Monthly)
Shows the percentage distance from Period High and Period Low for each timeframe
Visual color coding (green for bullish, red for bearish, gray for neutral)
Customizable location (8 positions), size, colors, and transparency
2. Key Metrics Displayed
% PL (Distance from Period Low): How far current price is above the period low
% PH (Distance from Period High): How far current price is below the period high
Retracement Ratio: Position within the PH-PL range (0 = at PL, 1 = at PH)
Trade Suggestions: Generated based on PL%, PH%, and retracement values
3. Dynamic Length Settings
Each timeframe can have its own lookback period (length)
Toggle between dynamic (per timeframe) or common length
Default lengths: 200 bars for most timeframes, 104 for Weekly, 60 for Monthly
4. Alert System
PL% Extreme alerts (near period lows - oversold)
PH% Extreme alerts (near period highs - overbought)
New Period High/Low alerts
Retracement level alerts (customizable levels)
MTF Confluence alerts (when 3+ timeframes show same extreme)
Breakout alerts (price moves away from extreme levels)
Visual Elements
Dashboard Table
text
| Symbol | 1 | 3 | 5 | 15 | 60 | 120 | 240 | D | W | M |
| % PL | 2.5%| 1.8%| 3.2%| 0.5%| 4.1%| 6.2%| 8.1%| 2.3%| 5.7%| 9.4%|
| % PH | 5.2%| 6.8%| 4.3%| 7.1%| 3.9%| 2.5%| 1.8%| 6.5%| 4.2%| 1.9%|
| Retr | 0.32| 0.21| 0.43| 0.07| 0.51| 0.71| 0.82| 0.26| 0.58| 0.83|
| Signal | BUY | BUY | WATCH|BUY | NEUT|SELL |SELL |BUY | SELL |SELL |
Chart Plots
Distance from PH (red line)
Distance from PL (green line)
Retracement (white line, displayed as 0-100%)
Horizontal reference lines at 25%, 50%, 75%, 0%
Trade Suggestion Logic
Condition Signal
PL > 70% AND Ret < 0.33 STRONG BUY
PL > 70% BUY
Ret < 0.25 BUY ZONE
PH > 70% AND Ret > 0.66 STRONG SELL
PH > 70% SELL
Ret > 0.75 SELL ZONE
Ret 0.45-0.55 NEUTRAL
Ret > 0.55 WATCH TOP
Ret < 0.45 WATCH BOTTOM
Key Input Settings
Timeframes
Customize each of the 10 timeframes using standard TradingView format (1, 3, 5, 15, 60, 120, 240, D, W, M)
Length Settings
Toggle dynamic length per timeframe
Set individual lengths for each timeframe
Default common length: 200 bars
Dashboard Display
Location: 8 positions
Size: Tiny, Small, Normal, Large
Customizable colors for bullish/bearish/neutral cells
Show/hide PH and PL prices
Show/hide retracement and trade suggestions
Alert Settings
Adjustable thresholds for PL% and PH% alerts (default: 50%)
Toggle specific alert types on/off
Customizable retracement levels (comma-separated)
MTF confluence threshold (default: 30%)
Usage Tips
For Swing Trading: Focus on higher timeframes (D, W, M) for trend identification
For Day Trading: Use lower timeframes (1-15min) for entry/exit signals
For Overbought/Oversold: Watch PL% > 70% (oversold) and PH% > 70% (overbought)
For Trend Reversals: Look for retracement moving from extremes (>0.66 or <0.33) back towards 0.5
FOR EDUCATIONAL PURPOSES ONLY\BOT A FINANCIAL ADVICE 指標

指標

Coil Breaker | RSI Range CompressionMost RSI strategies fire off static 30/70 thresholds. Coil Breaker does something different: it treats RSI itself as a volatility asset and watches for its own trading range to contract to a multi-month low — a "coil" — before trading the breakout when it releases.
How it works:
Measures RSI's high-minus-low range over the last N bars and ranks it against its own history using a percentile score
When that range compresses into the bottom percentile (default 20%), RSI is flagged as "coiled" — oscillating tightly around 50, momentum dormant
A dynamic Bollinger-style channel is plotted directly around RSI so you can visually watch the coil tighten before it fires
Once a squeeze has been active recently, a breakout above/below the established coil band (not the still-forming one) triggers an entry
Direction is set by an EMA slope filter — the coil tells you something's coming, the EMA tells you which way
Optional ADX filter keeps you out of truly dead, directionless chop
ATR-based stop, fixed R-multiple target, and equity-percent risk sizing so every trade risks a constant dollar amount
Important — read before trading:
This is a breakout/momentum system, not a mean-reversion one, and it behaves accordingly: expect a low win rate (often 30–40%) alongside a high average win/loss ratio. Most coil breakouts fail or chop — you're paying for early entry with more false signals. The edge comes from asymmetric payoff (2R+ winners vs. 1R losers), not from being right often. Judge this strategy on profit factor and expectancy, not win rate. If a 60%+ win rate is what you're looking for, this isn't that system.
Tips:
Backtest coilLen, pctLen, and the percentile threshold across your specific instrument/timeframe — coil dynamics vary a lot between assets
Watch the equity curve shape, not just the total return — make sure gains aren't carried by one or two outlier trades
Works best on instruments/timeframes with genuine volatility cycles (expansion/contraction), not ultra-choppy or illiquid markets
Pair with higher-timeframe context if you want to filter out counter-trend coil breaks
策略

Daily BB (Historical Plotting with RTH/ETH/24H)Daily BB (RTH/ETH/24H) projects Daily Bollinger Bands onto intraday charts using Regular Trading Hours (RTH) daily data as the underlying daily reference.
The script plots a projected Daily Bollinger Band basis together with projected upper and lower bands. By default, the basis uses a 20-day calculation and the bands use ±2 standard deviations. The length, standard-deviation multiplier, and band fill can be adjusted in the indicator settings.
Unlike a standard Bollinger Band calculated from the chart’s intraday bars, this indicator maintains a Daily calculation. Completed RTH daily closes provide the historical portion of the Daily window, while the current intraday price is used as the projected close for the unfinished Daily period. This allows the Daily basis and bands to update throughout the trading day rather than remaining fixed until the Daily candle closes.
The indicator is designed for use on intraday charts with TradingView’s RTH, ETH, or 24H session settings. Daily history is sourced from the symbol’s regular trading session, so overnight and extended-hours prices can update the projected Daily values without becoming separate completed Daily observations.
Daily rollover is based on the New York calendar date. On normal 24H weekdays, the projected Daily window advances at 00:00 ET. After a weekend, TradingView has no intervening Saturday bars and does not resume data until Sunday evening. Sunday 20:00 ET is therefore the first available Sunday candle, so the projection can reseed there using Friday’s completed RTH close. This does not create a Sunday RTH Daily candle. At Monday 00:00 ET, there may be no additional visible seed change because Sunday did not produce a completed RTH Daily candle.
At the first RTH bar, the script synchronizes the projection with the confirmed RTH Daily history. Higher-timeframe data requests are structured so unfinished Daily values are not inserted into earlier historical bars.
How to use it: The projected bands show where the Daily Bollinger Band would be if the current intraday price were the Daily close. They can therefore be used to view the developing Daily BB structure before the session has finished. The values remain projections until the applicable RTH Daily candle is complete.
This script uses the same RTH-based projected Daily framework as my Daily SMA indicator, but performs a distinct Bollinger Band calculation. In addition to the projected Daily mean, it calculates projected Daily variance and standard-deviation bands to produce the upper and lower envelope. This provides functionality beyond a moving-average variation and is intended for traders who want developing Daily Bollinger Band context visible directly on an intraday RTH, ETH, or 24H chart. 指標

Best ORB Strategy Detector + Entry FinderBest ORB Detector + Entry Finder
An Opening Range Breakout (ORB) indicator focused on one thing: find the opening range, catch the break, and manage the trade with clear entry, stop, and targets.
Most ORB tools only draw two lines and leave the rest to you. This one goes further — session selection, a single clean ORB stage, breakout/retest logic, optional filters, and full trade management on the chart.
The idea is simple: the first minutes of a session often define support and resistance for the day. When price breaks that range with conviction, moves can travel. When it breaks without conviction, they fail. This script helps you see both.
Built by the Xcelerate Trade team.
What makes it different
One ORB at a time
Instead of stacking four ranges on the chart, you pick one stage: ORB 5M, 15M, 30M, or 60M. Cleaner chart, clearer plan.
Session-aware
Choose Asia, London, or New York. The opening range is built from that session’s start — not a generic “market open” that may not match how you trade.
Entry the way you actually trade
Breakout — enter after the range breaks
Retest + Rejection — wait for price to come back to the ORB level, reject, then enter
Both — allow either path
This matches how many discretionary ORB traders work: the break is the alert, the retest is often the entry.
Trade management built in
When a setup triggers, you get entry, classic ORB stop (beyond the opposite side of the range, with optional buffer), and take-profit levels from 1R to 6R. Lines extend forward until stop or the last enabled target is hit.
Optional quality filters
Volume and FVG filters are available and off by default, so you start with raw price action and tighten only when you need fewer, cleaner signals.
Core features
1. ORB stages (pick one)
ORB 5M — fastest, more noise
ORB 15M — balanced, most common day-trading window
ORB 30M — slower, more confirmed
ORB 60M — slowest, strongest filter
During the window, the script tracks high and low. When the window completes, those levels become your ORB high and low.
2. Breakout detection
Labels appear when price closes outside the range (body close or wick, depending on your setting). Signals are confirmed on close — no repainting.
3. Retest and cycle tracking
After a breakout, if price returns to the ORB level, you can get a retest label. Useful if you missed the first move, or if you wait for retest entries by design.
Signal mode: First Only (cleaner) or Track Cycles (breakout → retest → re-break).
4. Failed / weak breaks
Settings like breakout buffer, min bars outside, and min distance for retest help filter tiny wiggles and half-hearted breaks.
5. TP / SL lines
Entry
Stop (classic ORB stop + buffer %)
TP1 (1R) through TP6 (6R)
Enable only the targets you use. When the last enabled TP or the stop is hit, lines freeze.
6. Info panel
Bottom-left dashboard with active ORB, range size, volatility, volume status (when the filter is on), ORB status, and the live setup (entry / stop / TPs / R:R). Panel size and theme are adjustable.
Volume filter
Many ORB fakeouts happen on thin volume. When Enable Volume Filter is on, a breakout needs volume confirmation.
Modes:
Increasing — breakout bar volume higher than the previous bar (Academy-style “volume in expansion”)
Above Average — volume at least X times the volume MA
Both — stricter: rising and above average
Use this on stocks and futures where volume is meaningful. On some CFDs, volume can be weak or synthetic — if signals disappear, turn the filter off or loosen the mode.
FVG filter (Fair Value Gap)
FVGs are short inefficiencies left by strong momentum candles. When Enable FVG Filter is on, breakouts are preferred when they interact with a nearby gap. You can also Show FVG Boxes without forcing the filter, just for context.
Why it helps: breaks through an FVG often carry more follow-through than breaks into empty air.
FVG Proximity controls how close the gap must be to count.
Start without FVG. Add it when you want fewer, higher-conviction setups.
How to use it
Simple start
Chart: 5m or 15m on a liquid symbol
Select Session (e.g. New York)
Select ORB (e.g. ORB 15M)
Leave filters off at first
Watch breakout / retest labels and the dashboard for entry, stop, and targets
Tighter setup
Entry Mode = Retest + Rejection
Volume Filter = Increasing or Both
FVG Filter on if you want institutional-style confirmation
Enable the TPs you actually take (many traders use TP1 + TP2, and leave TP3–TP6 for runners)
Suggested take-profit approach
Conservative: full exit at TP1
Balanced: partial at TP1, rest at TP2
Aggressive: trail toward TP3–TP6 on strong trend days
After TP1, many traders move stop to breakeven.
Tips
ORB works best on liquid instruments during the real session
The first hour matters most — that is when the range forms and the first breaks appear
Not every day is an ORB day; skip chop
Filters reduce noise but also reduce frequency — adjust to your style
Always use a stop; the R-multiple targets only make sense if risk is defined
Limitations
Intraday tool — not meant for daily/weekly charts
Needs a clear session definition
Can still false-break in ranges; filters help but do not remove risk
Volume quality depends on the symbol/feed
Indicator = decision aid, not a fully automated strategy
FAQ (short)
Why no signals? Check timeframe (intraday), session hours, breakout detection on, and whether filters are blocking you.
Best ORB stage? ORB 15M is a good default. 5M is faster/noisier; 30M/60M are slower/cleaner.
Should I enable all filters? No. Start clean, then add Volume first, then FVG if you still want fewer trades.
First Only vs Track Cycles? First Only = one main idea per direction. Track Cycles = more opportunities, busier chart.
Disclaimer
For education and research only. Not financial advice. Trading involves risk of loss. Paper trade first. Manage risk. Decisions are yours. 指標

指標