
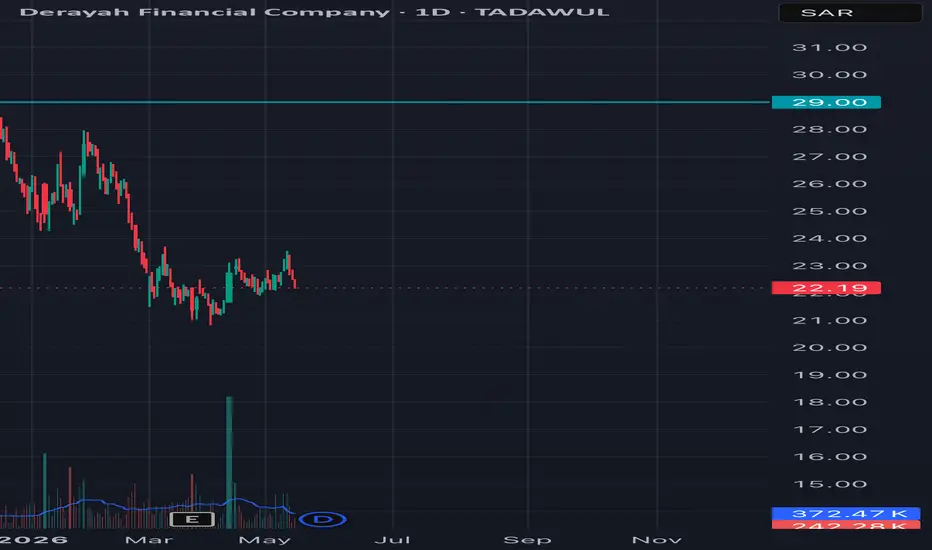
Drayah Financial 💫
Drayah Financial is gradually transforming into a broader digital financial platform with strong fintech expansion potential.
For those who still see it as “just a brokerage company,” the story today is becoming much bigger than that. 👍🏻
## Q1 2026 Results
- Operating income: SAR 228M (+9%)
- Core net profit: SAR 127M (-3%)
- Assets under custody: SAR 35B (+5%)
- Total accounts: 637K (+3%)
- Revenue growth accelerated to 43.3% vs. 37.2% previously
The company still relies heavily on:
- Trading activity
- Retail speculation
- Market commissions
However, management is clearly expanding into:
- Asset management
- Subscription-based products
- Investment solutions
This explains the strong revenue acceleration to 43.3%. 👍🏻
## Segment Breakdown
- Brokerage revenue: SAR 133M
- Special commissions income surged +54% to SAR 65M
- Asset management revenue declined -17%
Operating expenses increased by +29% mainly due to:
- Technology investments
- Marketing expansion
- D360 Bank spending 🫣
Yes, higher expenses are currently pressuring net profit margins, but these can also be viewed as future growth investments.
## D360 Bank 🤬
This project could completely transform the company long term, but success depends on:
- Serious execution
- Strong management
- Long-term strategic vision
If management succeeds, Drayah could eventually evolve into something similar to Interactive Brokers or Robinhood — but with a Saudi fintech ecosystem.
## Valuation
- Closing price: SAR 22.60
- Shares outstanding: 242.67M
- Free float: 31.54% 👍🏻
- Market cap: SAR 5.48B
### Expected Annual Profit
Quarterly profit:
SAR 127M × 4 = SAR 508M
### Forward EPS
508M / 242.67M = SAR 2.09
### Forward P/E
22.60 / 2.09 = 10.8x
## Dividend Analysis
The company announced a quarterly dividend of SAR 0.33.
Annualized dividend:
0.33 × 4 = SAR 1.32
### Dividend Yield
1.32 / 22.60 = 5.75%
### Payout Ratio
80.7M / 127M = 63.5%
## Fair Value Estimate
In my opinion, the stock still looks undervalued.
The current P/E of 10.8x does not fully reflect:
- Growth potential
- Fintech expansion
- Strong dividend profile
I believe the company deserves a valuation closer to 14–16x earnings.
Using forward EPS of SAR 2.09:
- 14x P/E → SAR 29.3
- 16x P/E → SAR 33.4
### Fair Value Range:
SAR 29–33 within a one-year horizon 😉
If D360 Bank succeeds, the stock could trade well above SAR 33+.
## Technical View
Technically, I believe the breakout starts above the SAR 23 leve

Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.