
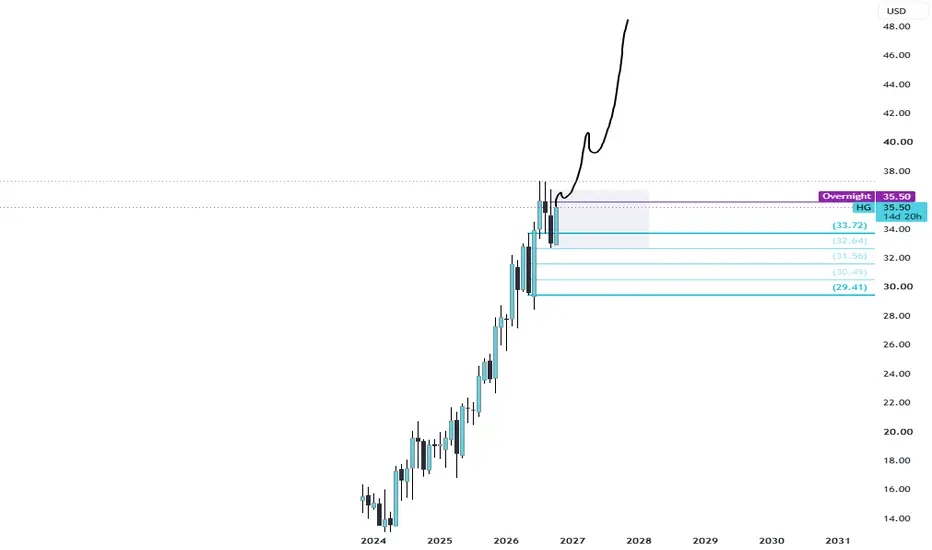
**LONG  HG around $35 — Four-Pillar Positional Thesis**
**1. Profitable underwriting**
Hamilton’s Q2 combined ratio was 95%—still profitable despite elevated catastrophe losses. Disciplined underwriting supports the thesis.
**2. Growing franchise**
Gross premiums written increased 16.7% year over year. Continued growth creates earnings potential if pricing and risk selection hold.
**3. Returns can support the valuation**
At $35, HG trades around 1.21× June book value of $28.91. Q2 annualized ROE was 20.6%; sustaining strong returns could justify that premium.
**4. Multiple paths to shareholder value**
Profitable underwriting, investment income and buybacks can compound value per share. The positional opportunity rests on continued execution rather than multiple expansion alone.
**Invalidation:** persistent underwriting deterioration, adverse reserve development or falling book value. Investment returns are volatile; one strong quarter should not be annualized.
*Fundamental thesis at a proposed $35 entry—not a confirmed technical breakout.*
[Source: Hamilton Q2 2026 results](investors.hamiltongroup.com/news/news-details/2026/Hamilton-Reports-2026-Second-Quarter-Results/default.aspx)
HG around $35 — Four-Pillar Positional Thesis****1. Profitable underwriting**
Hamilton’s Q2 combined ratio was 95%—still profitable despite elevated catastrophe losses. Disciplined underwriting supports the thesis.
**2. Growing franchise**
Gross premiums written increased 16.7% year over year. Continued growth creates earnings potential if pricing and risk selection hold.
**3. Returns can support the valuation**
At $35, HG trades around 1.21× June book value of $28.91. Q2 annualized ROE was 20.6%; sustaining strong returns could justify that premium.
**4. Multiple paths to shareholder value**
Profitable underwriting, investment income and buybacks can compound value per share. The positional opportunity rests on continued execution rather than multiple expansion alone.
**Invalidation:** persistent underwriting deterioration, adverse reserve development or falling book value. Investment returns are volatile; one strong quarter should not be annualized.
*Fundamental thesis at a proposed $35 entry—not a confirmed technical breakout.*
[Source: Hamilton Q2 2026 results](investors.hamiltongroup.com/news/news-details/2026/Hamilton-Reports-2026-Second-Quarter-Results/default.aspx)

Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.