
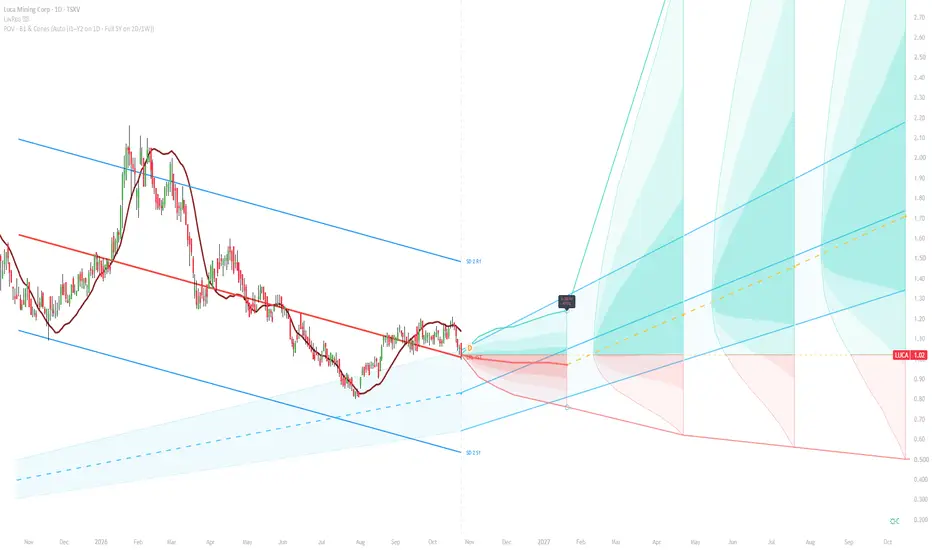
1. Assumed Metal Price Deck by Scenario (1Y / 3Y / 5Y)
Scenario Prior → Post Weight Gold (USD/oz) 1Y / 3Y / 5Y Silver (USD/oz) 1Y / 3Y / 5Y Copper (USD/lb) 1Y / 3Y / 5Y Zinc (USD/mt) [USD/lb] 1Y / 3Y / 5Y 1Y Implied Share Price (CAD)
Bear (Cozamin deal fails) 25% → 20% \$3,262 / \$3,200 / \$3,200 \$41.03 / \$40.00 / \$40.00 \$3.84 / \$3.80 / \$3.80 \$2,041 / \$2,000 / \$2,000 [\$0.93 / \$0.91] C\$0.00
Base (Cozamin closes) 45% → 56% \$4,582 / \$4,500 / \$4,500 \$69.54 / \$68.13 / \$68.13 \$5.87 / \$5.86 / \$5.86 \$3,002 / \$2,951 / \$2,951 [\$1.36 / \$1.34] C\$1.38
Bull (Cozamin closes) 25% → 20% \$6,500 / \$6,500 / \$6,500 \$112.05 / \$110.00 / \$110.00 \$8.00 / \$8.00 / \$8.00 \$4,200 / \$4,200 / \$4,200 [\$1.91 / \$1.91] C\$4.46
Blue Sky (+10% vs. Bull) 5% → 4% \$7,150 / \$7,150 / \$7,150 \$123.26 / \$121.00 / \$121.00 \$8.80 / \$8.80 / \$8.80 \$4,620 / \$4,620 / \$4,620 [\$2.10 / \$2.10] C\$6.17
2. Physical Realization, Streams & Contingent Copper Triggers (company_adjusted)
Standalone Operations (Campo Morado + Tahuehueto, vs. Q2 2026 Realized Baseline of \$4,514/oz Au, \$73.37/oz Ag, \$6.03/lb Cu, \$3,439/t Zn):
Gold (21.49 koz/yr payable at 92% net realization): C\$0.0281m (US\$0.0198m) annual EBITDA per \$1/oz change in Gold.
Silver (548 koz/yr Campo Morado unstreamed at 92% + 521 koz/yr Tahuehueto Empress-streamed at 20% cash price): C\$0.8639m (US\$0.6086m) annual EBITDA per \$1/oz change in Silver (with the full US\$39.78m / C\$56.48m Empress stream fair-value liability deducted once in other_claims_mm).
Copper (7.85 Mlbs/yr payable at 90% concentrate capture): C\$10.0320m (US\$7.0668m) annual EBITDA per \$1.00/lb change in Copper.
Zinc (11,516 t/yr payable at 85% concentrate capture): C\$0.0139m (US\$0.0098m) annual EBITDA per \$1/mt change in Zinc.
Conditional Cozamin Mine (Base, Bull, Blue Sky where acquisition closes):
Adds 38.0 Mlbs/yr payable Copper (25% hedged/capped at Base 1Y \$5.87/lb in Years 1–3), 1.50 Moz/yr payable Silver (net of the combined 65% Wheaton silver stream at 10% spot cash price
→
→ 41.5% effective realization), and 3,500 t/yr by-product Zinc.
Capstone Copper-Price Contingent Earnout (2027–2029): Automatically deducts US\$0m/yr in Base (Cu = \$5.87/lb < \$7.00/lb), US\$15.0m/yr (C\$21.29m/yr) in Bull (Cu = \$8.00/lb ≥$7.76/lb≥$7.76/lb), and US\$20.0m/yr (C\$28.39m/yr) in Blue Sky (Cu= \$8.80/lb ≥$8.51lb≥$8.51/lb).
Scenario Prior → Post Weight Gold (USD/oz) 1Y / 3Y / 5Y Silver (USD/oz) 1Y / 3Y / 5Y Copper (USD/lb) 1Y / 3Y / 5Y Zinc (USD/mt) [USD/lb] 1Y / 3Y / 5Y 1Y Implied Share Price (CAD)
Bear (Cozamin deal fails) 25% → 20% \$3,262 / \$3,200 / \$3,200 \$41.03 / \$40.00 / \$40.00 \$3.84 / \$3.80 / \$3.80 \$2,041 / \$2,000 / \$2,000 [\$0.93 / \$0.91] C\$0.00
Base (Cozamin closes) 45% → 56% \$4,582 / \$4,500 / \$4,500 \$69.54 / \$68.13 / \$68.13 \$5.87 / \$5.86 / \$5.86 \$3,002 / \$2,951 / \$2,951 [\$1.36 / \$1.34] C\$1.38
Bull (Cozamin closes) 25% → 20% \$6,500 / \$6,500 / \$6,500 \$112.05 / \$110.00 / \$110.00 \$8.00 / \$8.00 / \$8.00 \$4,200 / \$4,200 / \$4,200 [\$1.91 / \$1.91] C\$4.46
Blue Sky (+10% vs. Bull) 5% → 4% \$7,150 / \$7,150 / \$7,150 \$123.26 / \$121.00 / \$121.00 \$8.80 / \$8.80 / \$8.80 \$4,620 / \$4,620 / \$4,620 [\$2.10 / \$2.10] C\$6.17
2. Physical Realization, Streams & Contingent Copper Triggers (company_adjusted)
Standalone Operations (Campo Morado + Tahuehueto, vs. Q2 2026 Realized Baseline of \$4,514/oz Au, \$73.37/oz Ag, \$6.03/lb Cu, \$3,439/t Zn):
Gold (21.49 koz/yr payable at 92% net realization): C\$0.0281m (US\$0.0198m) annual EBITDA per \$1/oz change in Gold.
Silver (548 koz/yr Campo Morado unstreamed at 92% + 521 koz/yr Tahuehueto Empress-streamed at 20% cash price): C\$0.8639m (US\$0.6086m) annual EBITDA per \$1/oz change in Silver (with the full US\$39.78m / C\$56.48m Empress stream fair-value liability deducted once in other_claims_mm).
Copper (7.85 Mlbs/yr payable at 90% concentrate capture): C\$10.0320m (US\$7.0668m) annual EBITDA per \$1.00/lb change in Copper.
Zinc (11,516 t/yr payable at 85% concentrate capture): C\$0.0139m (US\$0.0098m) annual EBITDA per \$1/mt change in Zinc.
Conditional Cozamin Mine (Base, Bull, Blue Sky where acquisition closes):
Adds 38.0 Mlbs/yr payable Copper (25% hedged/capped at Base 1Y \$5.87/lb in Years 1–3), 1.50 Moz/yr payable Silver (net of the combined 65% Wheaton silver stream at 10% spot cash price
→
→ 41.5% effective realization), and 3,500 t/yr by-product Zinc.
Capstone Copper-Price Contingent Earnout (2027–2029): Automatically deducts US\$0m/yr in Base (Cu = \$5.87/lb < \$7.00/lb), US\$15.0m/yr (C\$21.29m/yr) in Bull (Cu = \$8.00/lb ≥$7.76/lb≥$7.76/lb), and US\$20.0m/yr (C\$28.39m/yr) in Blue Sky (Cu= \$8.80/lb ≥$8.51lb≥$8.51/lb).

Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.