
SpaceX (SPCX) 2026+ Catalysts & Risks Institutional Overview
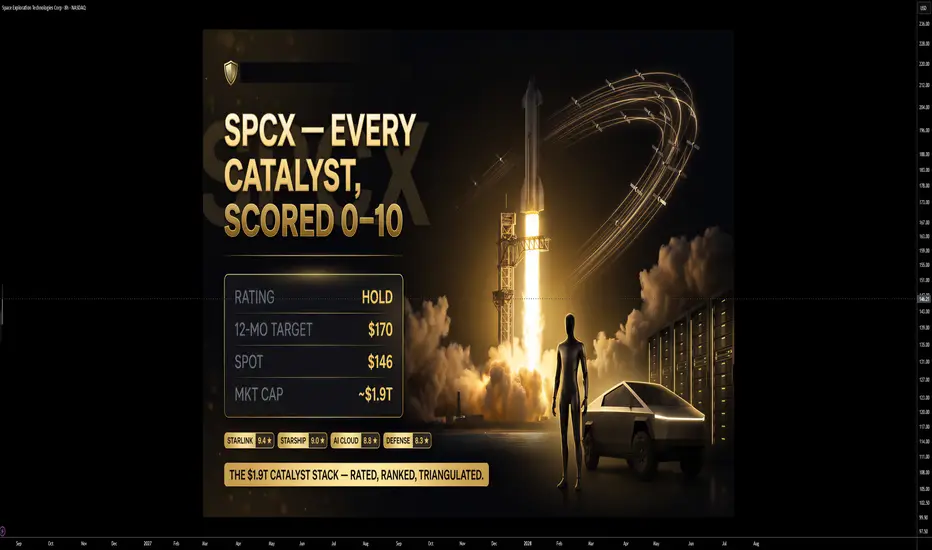
SPCX (2026+) Catalysts, Risks & Financials: Ranked Desk Views
As of August 18, 2026. Stock ~$146. Consensus rating Moderate Buy (~24 of ~32 analysts buy/strong-buy); average 12-month target ~$223 (~+53% upside); range $75 (low) → $600 (high, Morgan Stanley bull). Syndicate Catalysts Desk 12-mo target $170 (HOLD). Next earnings ~early Nov 2026 (Q3 2026). Latest reported quarter: Q2 2026 (ended Jun 30, 2026) — revenue $7.81B (+92% YoY), Connectivity/Starlink $4.29B (+66%) with $1.66B operating profit, AI $2.6B (+247%). Segment valuations, forward revenue and probabilities are Desk estimates.
🔑 Key Catalysts Driving SPCX (2026+)
🛰️ Starlink Franchise + V3 Capacity Unlock (the core engine)
Starlink is the profit engine — FY25 revenue $11.4B (+50%), ~39% operating margin, and the only profitable segment. Subscribers doubled YoY to 12.0M (30 Jun 2026) across ~160 markets. The economic step-change is the V3 satellite (Starship-launched, ~10× V2 capacity), which is what lets ARPU (~$66) stabilise as subs compound toward a modelled 20M+. Direct-to-cell rides ~65 MHz of EchoStar spectrum (~$17B, FCC-approved 12 May 2026). Impact Score: 9.4/10
🚀 Starship Block 3 + Full Reusability (the upgrade cycle)
Starship Block 3 infrastructure is building at Cape Canaveral; the first Florida flight and orbital booster-and-ship reuse are the prerequisite for Artemis lunar landing, point-to-point, V3 Starlink and larger Starshield/AI payloads. A structural ~$2,700–3,000/kg reusable-launch cost is the moat behind every other segment; sub-$100/kg Starship is the aspiration. [Impact if achieved on time.] Impact Score: 9.0/10
🤖 AI / xAI Cloud ARR Ramp (the second engine, and the optionality)
AI revenue +247% YoY to $2.6B in Q2, of which ~$1.6B was new cloud/compute-hosting revenue; adjusted EBITDA turned positive (+$1.1B) for the first time. Google (~$920M/mo) and Anthropic (~$1.25B/mo) cloud contracts run ~$26B/yr; CFO added $6.7B of new contracts and targets a $100B ARR run-rate by year-end 2026. Colossus scaled to 1.4 GW, targeting 10–20 GW by end-2027. The $60B Cursor (Anysphere) deal closed 15 Aug. [MGMT ASPIRATION on the $100B/$1T targets.] Impact Score: 8.8/10
🛡️ Golden Dome / Starshield Defense Stack
~$6.45B of Golden Dome awards in May 2026 — $4.16B SB-AMTI + $2.29B SDN Backbone — plus an 18-mission SBST launch sweep (~$1.6B), together exceeding every rival's combined prototype awards. Near-vertically integrated (builds and launches), with a multi-award pipeline toward a ~600-satellite architecture and prototype milestones through end-2027. Impact Score: 8.3/10
📡 Direct-to-Cell + EchoStar Spectrum
650+ D2C satellites live, T-Mobile service since Oct 2025, and a large nationwide spectrum position. Large TAM against a global space economy projected to reach $1.8T by 2035 (WEF/McKinsey), tempered by the FCC's 23 Apr 2026 block of a separate spectrum bid and urban-coverage limits. Impact Score: 7.5/10
📈 Earnings Cadence & Estimate Revisions
Each of the first public prints is a high-conviction, high-volatility binary; Q2 confirmed +92% growth. Sell-side initiations cluster wide ($210 UBS, $235 Deutsche Bank, $250 Macquarie, $300/$600 Morgan Stanley) around a ~$223 mean, with revision momentum a flow driver. Impact Score: 7.2/10
💵 Capital-Markets / Structural (Index Inclusion + Institutional Accumulation)
Added to the Nasdaq-100 on 7 July 2026 (fast-entry rule; S&P 500 a 2027 candidate). Institutional base includes Alphabet (~$94.2B), Nvidia (~$21B), Fidelity, Saudi PIF, BlackRock, Ontario Teachers', Harvard; 1,500+ institutions disclosed. Impact Score: 7.0/10
🌘 Artemis / Lunar & Commercial Point-to-Point (long-dated optionality)
Human lunar landing (Artemis), commercial point-to-point Earth transport and "AI-in-space" data centres are large but distant, gated on Starship. [AGGRESSIVE MGMT ASPIRATION.] Impact Score: 6.0/10
🔀 Tesla–SpaceX Merger Optionality
WSJ reported (11 Aug 2026) a clause in Musk's ~$1T Tesla pay package that could unlock on a Tesla-into-SpaceX merger; Musk denied it, prediction markets imply ~17.5% by year-end. [REPORTED/UNCONFIRMED — SPEC.] Impact Score: 5.5/10
⚠️ Key Risks & Negative Drivers
🫧 Valuation & Multiple De-Rating
~$1.93T cap at ≈84× trailing sales with negative EPS (–$2.27) and no P/E or EV/EBITDA anchor. Roughly half the valuation rests on unproven AI. The stock already round-tripped from a $225.64 high to a $104.83 low; any guidance wobble → sharp de-rating toward Morningstar's ~$40–$62 core-business estimate. Risk Severity: 8.5/10
🔥 AI Cash Burn & Capital Needs (the SPCX "circular-financing" analog)
Capex was $18.37B in Q2 alone ($15.83B AI), >6× YoY; FY26E ~$65B outruns operating cash, with FCF deeply negative (~–$25B H1'26). KeyBanc flags ~$325B of raises over 18–24 months to fund AI compute — massive dilution risk. Risk Severity: 8.5/10
🔒 Lock-Up / Supply Overhang
Musk's ~6.4B-share June-2027 cliff equals ~4× the ~3–5% public float; ~1.7B more insider shares unlock through Dec 2026. The 6 Aug and index-inclusion days already showed "sell-the-news" behaviour. Risk Severity: 7.8/10
👑 Governance / Key-Man
Musk controls ~82.4% of votes via 10-vote super-voting stock; mandatory arbitration, a ~$52.5B derivative-suit threshold, and a Warren/SEC letter (9 Jun 2026) frame limited minority recourse. Headline/distraction risk spans his empire. Risk Severity: 7.5/10
🎯 Segment Profitability Concentration
Starlink is the only profitable leg; it subsidises Space (Starship R&D) and a loss-making AI segment. A Starlink stumble removes the group's earnings ballast. Risk Severity: 7.3/10
☁️ Cloud-Contract Cancellability
The Google and Anthropic cloud contracts (~$26B/yr) are cancellable on 90 days' notice after 31 Dec 2026 — a durability risk against which >half the AI valuation is underwritten. Risk Severity: 7.0/10
🥊 Competition & 🛰️ Execution
Launch: Rocket Lab (Neutron), Blue Origin (New Glenn), ULA (Vulcan). Starlink: Amazon Leo/Kuiper, Eutelsat-OneWeb, Chinese constellations. AI: Nvidia ecosystem, OpenAI, Anthropic, Google — where Grok holds <5% of the global assistant market. Starship remains in test (Flight 13 abort, 16 Jul); Block 3 unproven. Risk Severity: 6.5/10
📉 Macro / AI-Capex Cycle & Rates + 🔀 Earnings Volatility
Long-duration valuation is acutely rate- and sentiment-sensitive; a turn in the AI-capex cycle hits SPCX like the other mega-cap AI names. First prints have already sold off on capex shock. Risk Severity: 6.5/10
💰 Financial Scorecard (Q2 2026, ended Jun 30, 2026)
Each metric scored 0–10 on strength/quality relative to trajectory.
# Metric Latest Value Trend Strength
F1 Total revenue $7.81B +92% YoY; first public print, consensus beat 9.0
F2 Connectivity/Starlink revenue $4.29B +66% YoY; $1.66B op profit — only profitable segment 9.2
F3 Starlink subscribers 12.0M Doubled YoY; ~160 markets; ARPU ~$66 8.5
F4 Adjusted EBITDA $3.5B +191% YoY 8.0
F5 AI segment revenue $2.6B +247% YoY; adj. EBITDA +$1.1B (first positive) 7.0
F6 Cash & equivalents $93.5B vs $36.8B debt/leases post-IPO — strong liquidity 7.5
F7 Defense awards (2026 YTD) ~$6.45B Golden Dome SB-AMTI + SDN; multi-award pool 7.5
F8 Backlog / contracted cloud ~$47.5B / $14.1B Growing government + cloud commitments 7.0
F9 Net loss –$541M Narrowed from –$1.01B — improving but negative 4.5
F10 Capex $18.37B $15.83B AI; >6× YoY; ~$65B FY26E guide 2.5
F11 Free cash flow ~–$25B (H1'26) Deeply negative; implies dilutive raises 2.0
Financial composite (operating strength, avg of F1–F11): ~6.6/10 — elite top-line growth and a world-class Starlink franchise, offset by a loss-making AI leg, extreme capex intensity and negative free cash flow. (Distinct from the Desk's quality-and-trajectory scorecard of ~5.3/10, which also penalises dilution and sparse disclosure.)
🏆 Master Ranking — Catalysts & Financial Strengths Combined
Positive drivers ranked by score. Risks listed separately below.
Rank Driver Type Score (0–10)
1️⃣ 🛰️ Starlink franchise + V3 capacity unlock Catalyst 9.4
2️⃣ 🏢 Starlink revenue $4.29B (+66%, $1.66B op profit) Financial 9.2
3️⃣ 📊 Total revenue $7.81B (+92% YoY) Financial 9.0
3️⃣ 🤖 AI cloud ARR ramp toward $100B Catalyst 9.0
3️⃣ 🚀 Starship Block 3 + full reusability Catalyst 9.0
6️⃣ 📈 Starlink subscribers 12.0M (doubled YoY) Financial 8.5
7️⃣ 🛡️ Golden Dome / Starshield defense stack Catalyst 8.3
8️⃣ 💵 Adjusted EBITDA $3.5B (+191%) Financial 8.0
9️⃣ 🏦 Cash $93.5B vs $36.8B debt Financial 7.5
9️⃣ 🛡️ Defense awards ~$6.45B (2026) Financial 7.5
11️⃣ 📡 Direct-to-cell + EchoStar spectrum Catalyst 7.5
12️⃣ 📑 Earnings cadence & estimate revisions Catalyst 7.2
13️⃣ 📦 Backlog $47.5B + $14.1B contracted cloud Financial 7.0
13️⃣ 💵 Capital-markets: Nasdaq-100 + institutional accumulation Catalyst 7.0
15️⃣ 🌘 Artemis / lunar & point-to-point optionality Catalyst 6.0
⚠️ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1️⃣ 🫧 Valuation & multiple de-rating (~84× sales, neg. EPS) 8.5
1️⃣ 🔥 AI cash burn & ~$325B capital needs / dilution 8.5
3️⃣ 🔒 Lock-up / supply overhang (6.4B-sh Jun-2027 cliff) 7.8
4️⃣ 👑 Governance / key-man (Musk ~82% voting) 7.5
5️⃣ 🎯 Profit concentration (Starlink only profitable leg) 7.3
6️⃣ ☁️ Cloud-contract cancellability (Google/Anthropic 90-day) 7.0
7️⃣ 🥊 Competition + 🛰️ Starship execution / capex 6.5
7️⃣ 📉 Macro / AI-capex cycle & rate sensitivity 6.5
9️⃣ 📡 Regulatory / spectrum / orbital debris 5.8
🔟 🏛️ Policy / government dependence · 🔀 earnings volatility 5.5
📝 Summary Outlook (August 2026)
SpaceX enters H2 CY2026 as the most consequential public company in the space-and-AI buildout — record $7.81B quarterly revenue (+92%), a 12M-subscriber, ~39%-margin Starlink franchise that is the only profitable leg, an AI segment growing +247% with its first positive adjusted EBITDA, and ~$6.45B of Golden Dome defense wins layered on a structural launch monopoly. The Starlink V3 → Starship Block 3 cadence gives a built-in capacity upgrade cycle, and the Tesla merger is pure — and unconfirmed — optionality.
The bear case is not about demand — it's about how the growth is financed. Capex of $18.4B in a single quarter, deeply negative free cash flow, KeyBanc's ~$325B capital-need estimate, cancellable cloud contracts, and a ~6.4B-share June-2027 lock-up cliff sit against a ~$1.9T cap priced at ≈84× sales. Governance (~82% Musk voting control) leaves minority holders as passengers.
Bottom line: the core franchise is as strong as any in the buildout (operating-strength composite ~6.6/10), but the risk isn't operational execution — it's whether the AI-capex flywheel is self-sustaining or dilution-financed, and whether the June-2027 supply cliff is absorbed. We rate HOLD, $170 target: accumulate <$120, trim >$210. The next Q3 print (capex trajectory, AI ARR conversion, Starship timing) is the next decisive catalyst.
Sources: SpaceX S-1 (20 May 2026), 424B, Q2 2026 shareholder letter & transcript (4 Aug 2026); Musk 13G (30 Jun 2026); Space Systems Command award notices (SB-AMTI 29 May, SDN 26 May 2026); CNBC, Teslarati, BigGo, Yahoo Finance (earnings); Tech Times (SBST); stockanalysis.com, TipRanks (price/targets); UBS, Morgan Stanley, Deutsche Bank, Phillip Securities, KeyBanc, Morningstar (ratings); Reuters/Nvidia 13F (holders); Warren–SEC letter (9 Jun 2026); WSJ (11 Aug 2026, Tesla merger); FCC orders; Sensor Tower/Similarweb (Grok share); WEF/McKinsey ($1.8T space economy); Anysphere/Cursor close (15 Aug 2026).
As of August 18, 2026. Stock ~$146. Consensus rating Moderate Buy (~24 of ~32 analysts buy/strong-buy); average 12-month target ~$223 (~+53% upside); range $75 (low) → $600 (high, Morgan Stanley bull). Syndicate Catalysts Desk 12-mo target $170 (HOLD). Next earnings ~early Nov 2026 (Q3 2026). Latest reported quarter: Q2 2026 (ended Jun 30, 2026) — revenue $7.81B (+92% YoY), Connectivity/Starlink $4.29B (+66%) with $1.66B operating profit, AI $2.6B (+247%). Segment valuations, forward revenue and probabilities are Desk estimates.
🔑 Key Catalysts Driving SPCX (2026+)
🛰️ Starlink Franchise + V3 Capacity Unlock (the core engine)
Starlink is the profit engine — FY25 revenue $11.4B (+50%), ~39% operating margin, and the only profitable segment. Subscribers doubled YoY to 12.0M (30 Jun 2026) across ~160 markets. The economic step-change is the V3 satellite (Starship-launched, ~10× V2 capacity), which is what lets ARPU (~$66) stabilise as subs compound toward a modelled 20M+. Direct-to-cell rides ~65 MHz of EchoStar spectrum (~$17B, FCC-approved 12 May 2026). Impact Score: 9.4/10
🚀 Starship Block 3 + Full Reusability (the upgrade cycle)
Starship Block 3 infrastructure is building at Cape Canaveral; the first Florida flight and orbital booster-and-ship reuse are the prerequisite for Artemis lunar landing, point-to-point, V3 Starlink and larger Starshield/AI payloads. A structural ~$2,700–3,000/kg reusable-launch cost is the moat behind every other segment; sub-$100/kg Starship is the aspiration. [Impact if achieved on time.] Impact Score: 9.0/10
🤖 AI / xAI Cloud ARR Ramp (the second engine, and the optionality)
AI revenue +247% YoY to $2.6B in Q2, of which ~$1.6B was new cloud/compute-hosting revenue; adjusted EBITDA turned positive (+$1.1B) for the first time. Google (~$920M/mo) and Anthropic (~$1.25B/mo) cloud contracts run ~$26B/yr; CFO added $6.7B of new contracts and targets a $100B ARR run-rate by year-end 2026. Colossus scaled to 1.4 GW, targeting 10–20 GW by end-2027. The $60B Cursor (Anysphere) deal closed 15 Aug. [MGMT ASPIRATION on the $100B/$1T targets.] Impact Score: 8.8/10
🛡️ Golden Dome / Starshield Defense Stack
~$6.45B of Golden Dome awards in May 2026 — $4.16B SB-AMTI + $2.29B SDN Backbone — plus an 18-mission SBST launch sweep (~$1.6B), together exceeding every rival's combined prototype awards. Near-vertically integrated (builds and launches), with a multi-award pipeline toward a ~600-satellite architecture and prototype milestones through end-2027. Impact Score: 8.3/10
📡 Direct-to-Cell + EchoStar Spectrum
650+ D2C satellites live, T-Mobile service since Oct 2025, and a large nationwide spectrum position. Large TAM against a global space economy projected to reach $1.8T by 2035 (WEF/McKinsey), tempered by the FCC's 23 Apr 2026 block of a separate spectrum bid and urban-coverage limits. Impact Score: 7.5/10
📈 Earnings Cadence & Estimate Revisions
Each of the first public prints is a high-conviction, high-volatility binary; Q2 confirmed +92% growth. Sell-side initiations cluster wide ($210 UBS, $235 Deutsche Bank, $250 Macquarie, $300/$600 Morgan Stanley) around a ~$223 mean, with revision momentum a flow driver. Impact Score: 7.2/10
💵 Capital-Markets / Structural (Index Inclusion + Institutional Accumulation)
Added to the Nasdaq-100 on 7 July 2026 (fast-entry rule; S&P 500 a 2027 candidate). Institutional base includes Alphabet (~$94.2B), Nvidia (~$21B), Fidelity, Saudi PIF, BlackRock, Ontario Teachers', Harvard; 1,500+ institutions disclosed. Impact Score: 7.0/10
🌘 Artemis / Lunar & Commercial Point-to-Point (long-dated optionality)
Human lunar landing (Artemis), commercial point-to-point Earth transport and "AI-in-space" data centres are large but distant, gated on Starship. [AGGRESSIVE MGMT ASPIRATION.] Impact Score: 6.0/10
🔀 Tesla–SpaceX Merger Optionality
WSJ reported (11 Aug 2026) a clause in Musk's ~$1T Tesla pay package that could unlock on a Tesla-into-SpaceX merger; Musk denied it, prediction markets imply ~17.5% by year-end. [REPORTED/UNCONFIRMED — SPEC.] Impact Score: 5.5/10
⚠️ Key Risks & Negative Drivers
🫧 Valuation & Multiple De-Rating
~$1.93T cap at ≈84× trailing sales with negative EPS (–$2.27) and no P/E or EV/EBITDA anchor. Roughly half the valuation rests on unproven AI. The stock already round-tripped from a $225.64 high to a $104.83 low; any guidance wobble → sharp de-rating toward Morningstar's ~$40–$62 core-business estimate. Risk Severity: 8.5/10
🔥 AI Cash Burn & Capital Needs (the SPCX "circular-financing" analog)
Capex was $18.37B in Q2 alone ($15.83B AI), >6× YoY; FY26E ~$65B outruns operating cash, with FCF deeply negative (~–$25B H1'26). KeyBanc flags ~$325B of raises over 18–24 months to fund AI compute — massive dilution risk. Risk Severity: 8.5/10
🔒 Lock-Up / Supply Overhang
Musk's ~6.4B-share June-2027 cliff equals ~4× the ~3–5% public float; ~1.7B more insider shares unlock through Dec 2026. The 6 Aug and index-inclusion days already showed "sell-the-news" behaviour. Risk Severity: 7.8/10
👑 Governance / Key-Man
Musk controls ~82.4% of votes via 10-vote super-voting stock; mandatory arbitration, a ~$52.5B derivative-suit threshold, and a Warren/SEC letter (9 Jun 2026) frame limited minority recourse. Headline/distraction risk spans his empire. Risk Severity: 7.5/10
🎯 Segment Profitability Concentration
Starlink is the only profitable leg; it subsidises Space (Starship R&D) and a loss-making AI segment. A Starlink stumble removes the group's earnings ballast. Risk Severity: 7.3/10
☁️ Cloud-Contract Cancellability
The Google and Anthropic cloud contracts (~$26B/yr) are cancellable on 90 days' notice after 31 Dec 2026 — a durability risk against which >half the AI valuation is underwritten. Risk Severity: 7.0/10
🥊 Competition & 🛰️ Execution
Launch: Rocket Lab (Neutron), Blue Origin (New Glenn), ULA (Vulcan). Starlink: Amazon Leo/Kuiper, Eutelsat-OneWeb, Chinese constellations. AI: Nvidia ecosystem, OpenAI, Anthropic, Google — where Grok holds <5% of the global assistant market. Starship remains in test (Flight 13 abort, 16 Jul); Block 3 unproven. Risk Severity: 6.5/10
📉 Macro / AI-Capex Cycle & Rates + 🔀 Earnings Volatility
Long-duration valuation is acutely rate- and sentiment-sensitive; a turn in the AI-capex cycle hits SPCX like the other mega-cap AI names. First prints have already sold off on capex shock. Risk Severity: 6.5/10
💰 Financial Scorecard (Q2 2026, ended Jun 30, 2026)
Each metric scored 0–10 on strength/quality relative to trajectory.
# Metric Latest Value Trend Strength
F1 Total revenue $7.81B +92% YoY; first public print, consensus beat 9.0
F2 Connectivity/Starlink revenue $4.29B +66% YoY; $1.66B op profit — only profitable segment 9.2
F3 Starlink subscribers 12.0M Doubled YoY; ~160 markets; ARPU ~$66 8.5
F4 Adjusted EBITDA $3.5B +191% YoY 8.0
F5 AI segment revenue $2.6B +247% YoY; adj. EBITDA +$1.1B (first positive) 7.0
F6 Cash & equivalents $93.5B vs $36.8B debt/leases post-IPO — strong liquidity 7.5
F7 Defense awards (2026 YTD) ~$6.45B Golden Dome SB-AMTI + SDN; multi-award pool 7.5
F8 Backlog / contracted cloud ~$47.5B / $14.1B Growing government + cloud commitments 7.0
F9 Net loss –$541M Narrowed from –$1.01B — improving but negative 4.5
F10 Capex $18.37B $15.83B AI; >6× YoY; ~$65B FY26E guide 2.5
F11 Free cash flow ~–$25B (H1'26) Deeply negative; implies dilutive raises 2.0
Financial composite (operating strength, avg of F1–F11): ~6.6/10 — elite top-line growth and a world-class Starlink franchise, offset by a loss-making AI leg, extreme capex intensity and negative free cash flow. (Distinct from the Desk's quality-and-trajectory scorecard of ~5.3/10, which also penalises dilution and sparse disclosure.)
🏆 Master Ranking — Catalysts & Financial Strengths Combined
Positive drivers ranked by score. Risks listed separately below.
Rank Driver Type Score (0–10)
1️⃣ 🛰️ Starlink franchise + V3 capacity unlock Catalyst 9.4
2️⃣ 🏢 Starlink revenue $4.29B (+66%, $1.66B op profit) Financial 9.2
3️⃣ 📊 Total revenue $7.81B (+92% YoY) Financial 9.0
3️⃣ 🤖 AI cloud ARR ramp toward $100B Catalyst 9.0
3️⃣ 🚀 Starship Block 3 + full reusability Catalyst 9.0
6️⃣ 📈 Starlink subscribers 12.0M (doubled YoY) Financial 8.5
7️⃣ 🛡️ Golden Dome / Starshield defense stack Catalyst 8.3
8️⃣ 💵 Adjusted EBITDA $3.5B (+191%) Financial 8.0
9️⃣ 🏦 Cash $93.5B vs $36.8B debt Financial 7.5
9️⃣ 🛡️ Defense awards ~$6.45B (2026) Financial 7.5
11️⃣ 📡 Direct-to-cell + EchoStar spectrum Catalyst 7.5
12️⃣ 📑 Earnings cadence & estimate revisions Catalyst 7.2
13️⃣ 📦 Backlog $47.5B + $14.1B contracted cloud Financial 7.0
13️⃣ 💵 Capital-markets: Nasdaq-100 + institutional accumulation Catalyst 7.0
15️⃣ 🌘 Artemis / lunar & point-to-point optionality Catalyst 6.0
⚠️ Risk Ledger (severity-ranked)
Rank Risk Severity (0–10)
1️⃣ 🫧 Valuation & multiple de-rating (~84× sales, neg. EPS) 8.5
1️⃣ 🔥 AI cash burn & ~$325B capital needs / dilution 8.5
3️⃣ 🔒 Lock-up / supply overhang (6.4B-sh Jun-2027 cliff) 7.8
4️⃣ 👑 Governance / key-man (Musk ~82% voting) 7.5
5️⃣ 🎯 Profit concentration (Starlink only profitable leg) 7.3
6️⃣ ☁️ Cloud-contract cancellability (Google/Anthropic 90-day) 7.0
7️⃣ 🥊 Competition + 🛰️ Starship execution / capex 6.5
7️⃣ 📉 Macro / AI-capex cycle & rate sensitivity 6.5
9️⃣ 📡 Regulatory / spectrum / orbital debris 5.8
🔟 🏛️ Policy / government dependence · 🔀 earnings volatility 5.5
📝 Summary Outlook (August 2026)
SpaceX enters H2 CY2026 as the most consequential public company in the space-and-AI buildout — record $7.81B quarterly revenue (+92%), a 12M-subscriber, ~39%-margin Starlink franchise that is the only profitable leg, an AI segment growing +247% with its first positive adjusted EBITDA, and ~$6.45B of Golden Dome defense wins layered on a structural launch monopoly. The Starlink V3 → Starship Block 3 cadence gives a built-in capacity upgrade cycle, and the Tesla merger is pure — and unconfirmed — optionality.
The bear case is not about demand — it's about how the growth is financed. Capex of $18.4B in a single quarter, deeply negative free cash flow, KeyBanc's ~$325B capital-need estimate, cancellable cloud contracts, and a ~6.4B-share June-2027 lock-up cliff sit against a ~$1.9T cap priced at ≈84× sales. Governance (~82% Musk voting control) leaves minority holders as passengers.
Bottom line: the core franchise is as strong as any in the buildout (operating-strength composite ~6.6/10), but the risk isn't operational execution — it's whether the AI-capex flywheel is self-sustaining or dilution-financed, and whether the June-2027 supply cliff is absorbed. We rate HOLD, $170 target: accumulate <$120, trim >$210. The next Q3 print (capex trajectory, AI ARR conversion, Starship timing) is the next decisive catalyst.
Sources: SpaceX S-1 (20 May 2026), 424B, Q2 2026 shareholder letter & transcript (4 Aug 2026); Musk 13G (30 Jun 2026); Space Systems Command award notices (SB-AMTI 29 May, SDN 26 May 2026); CNBC, Teslarati, BigGo, Yahoo Finance (earnings); Tech Times (SBST); stockanalysis.com, TipRanks (price/targets); UBS, Morgan Stanley, Deutsche Bank, Phillip Securities, KeyBanc, Morningstar (ratings); Reuters/Nvidia 13F (holders); Warren–SEC letter (9 Jun 2026); WSJ (11 Aug 2026, Tesla merger); FCC orders; Sensor Tower/Similarweb (Grok share); WEF/McKinsey ($1.8T space economy); Anysphere/Cursor close (15 Aug 2026).
Ghi chú
SpaceX: The Ultimate 10X BetSpaceX is evolving from a rocket company into an integrated civilization platform—AI, global connectivity, compute, energy, chips, defense, finance and space manufacturing. Starlink funds the network, rockets create the moat, AI drives intelligence, and Moon-to-Mars infrastructure creates the long-term upside.

Gold Algo Trading · +1100% YTD · max DD <5%
Syndicate Ultimate · 5 algo systems · 1 bundle
1 payment · lifetime access · no monthly fees
+ FX · NQ/ES · 10+ yr institutional desk
syndicate001.com
Join on Telegram
t.me/aisyndicate001
Syndicate Ultimate · 5 algo systems · 1 bundle
1 payment · lifetime access · no monthly fees
+ FX · NQ/ES · 10+ yr institutional desk
syndicate001.com
Join on Telegram
t.me/aisyndicate001
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Gold Algo Trading · +1100% YTD · max DD <5%
Syndicate Ultimate · 5 algo systems · 1 bundle
1 payment · lifetime access · no monthly fees
+ FX · NQ/ES · 10+ yr institutional desk
syndicate001.com
Join on Telegram
t.me/aisyndicate001
Syndicate Ultimate · 5 algo systems · 1 bundle
1 payment · lifetime access · no monthly fees
+ FX · NQ/ES · 10+ yr institutional desk
syndicate001.com
Join on Telegram
t.me/aisyndicate001
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.