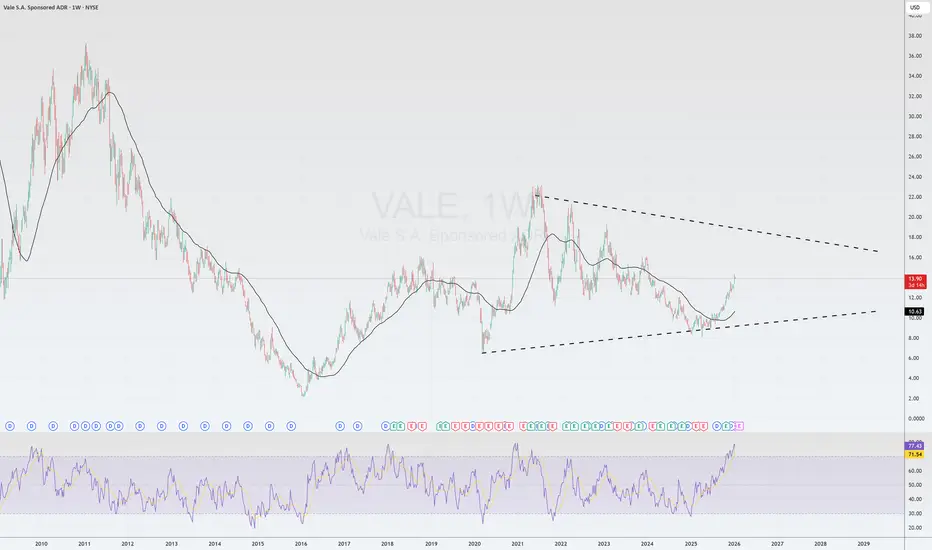
 VALE: Thesis for 2026
1. Strategic Pivot: From Iron Ore Proxy to Base Metals Leader
The most significant development for Vale in 2026 is the transformation of its base metals segment (nickel and copper) from a secondary unit into a primary profit engine.
Nickel Supply Shock: Indonesia, which controls over 50% of global supply, has implemented a 34% production cut for 2026. This has already triggered a >25% price surge within a month.
EBITDA Outperformance: This supply-side pressure could increase Vale’s consolidated EBITDA by ~8%. Current projections suggest the non-ferrous division could exceed $4 billion in EBITDA for 2026, significantly outperforming market consensus of $3 billion.
Copper Growth: Vale’s copper production is forecasted to grow at a 7% CAGR through 2035, outstripping global peers. Strategic moves, such as the Glencore joint venture in the Sudbury Basin, solidify this growth trajectory.
2. Operational Excellence and Cost Leadership
🔎

Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.