
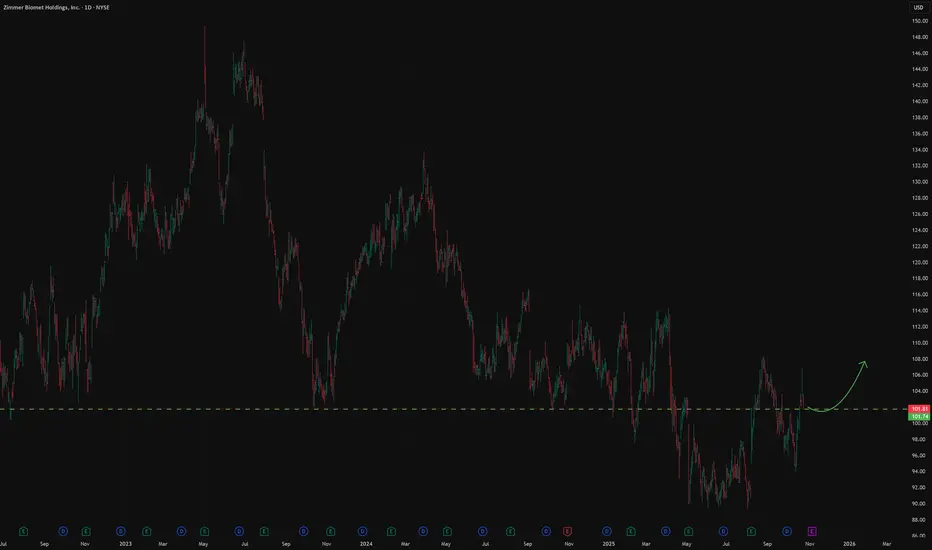
🌎Zimmer Biomet specializes in musculoskeletal systems. The company is highly diversified both geographically (operations in over 25 countries, sales in over 100 countries) and in its product line.
Core business areas include:
Orthopedic reconstructive products: Joint replacement (hip, knee).
Products for sports medicine, biopharmaceuticals, extremities, and traumatology.
Solutions for spine treatment, bone fusion, craniofacial and thoracic surgery.
Dental Implants and Surgical Instruments
After a decline in 2020 caused by the pandemic (when many elective surgeries were postponed), the company is showing revenue growth, reaching $7.83 billion in the trailing 12 months (TTM).
Operating profit is showing growth, more than doubling compared to 2020 levels.
At the end of its most recent reporting quarter, the company reported net income of $903.7 million for the trailing 12 months (LTM).
In August 2025, Zimmer Biomet reported earnings per share (EPS) of $2.07, exceeding the analyst consensus estimate of $1.98 by $0.09.
Operating profit continues to grow, reaching $1.528 billion in 2024.
A key driver of investor interest is the stock's undervaluation. The forward P/E ratio is 12.1, significantly below the market average.
The company maintains a consistent dividend policy.

Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.
Thông báo miễn trừ trách nhiệm
Thông tin và các ấn phẩm này không nhằm mục đích, và không cấu thành, lời khuyên hoặc khuyến nghị về tài chính, đầu tư, giao dịch hay các loại khác do TradingView cung cấp hoặc xác nhận. Đọc thêm tại Điều khoản Sử dụng.